

Quick Answer: Federal credit repair law exempts 501(c)(3) nonprofits from its rules, and Michigan’s state credit repair law contains the identical carve-out. So the exemption is real, and it reaches further than the federal statute alone suggests. It is also not a free pass: every federal appeals court that has ruled requires an organization to actually operate as a nonprofit, with the burden of proof on the organization, and general consumer-fraud laws contain no such carve-out — which is why the lawsuit described below is pleaded under one. Here is how each piece works, so you can check any organization yourself.
This came up because of a lawsuit I published this week. Working through the complaint sent me back to the statute itself, and I found a sentence that still made me stop after reading consumer credit law since 1994.
The federal law written to protect you from credit repair companies lifts an entire category of company out of its reach. Not a narrow carve-out. A complete exemption. And the thing that earns it is not honesty, not results, not how customers are treated.
It is a tax status.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 11): You drive to the dealership to pick up the car. There is no car. There was never a car.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
The obvious question is whether that is a clever loophole — a real door someone can walk through — or a dead end that only looks like a door. I went and read the law, the cases and the filings to find out. What follows is what I found, so you can weigh it yourself.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Why it looks clever
The Credit Repair Organizations Act governs companies selling services to improve your credit. It bans lying about results. It bans taking money before the work is done. It requires disclosures and a written contract. It lets you sue.
Then 15 U.S.C. § 1679a(3)(B)(i) says “credit repair organization” does not include:
“any nonprofit organization which is exempt from taxation under section 501(c)(3) of title 26”
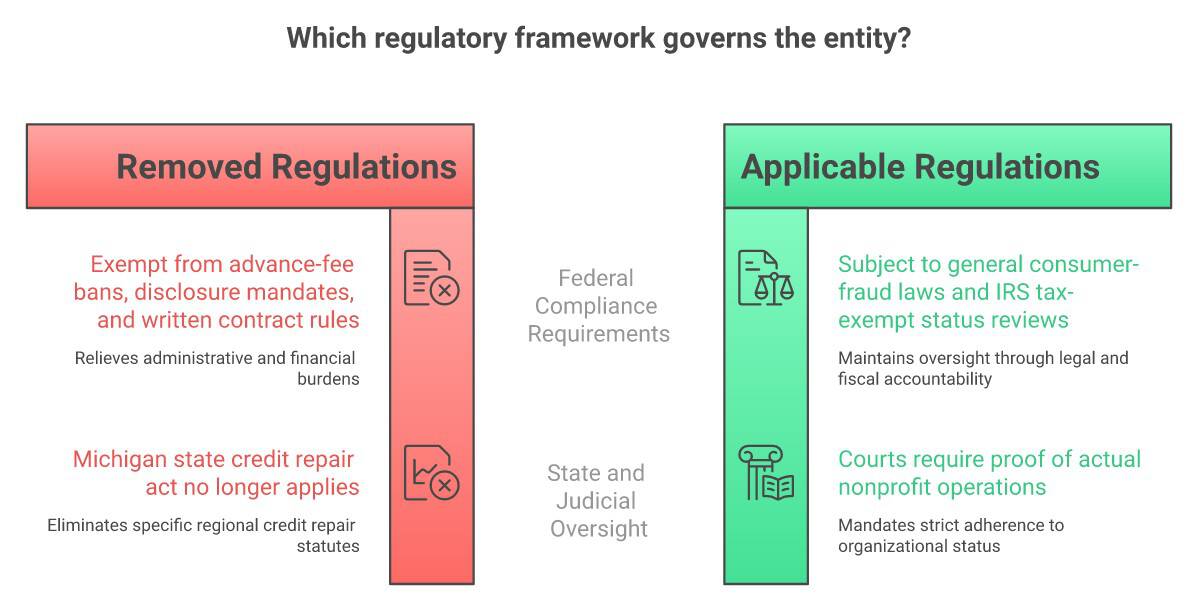
Read literally, a 501(c)(3) walks free of § 1679b(b), the advance-fee ban — the rule most credit repair operators break — plus the ban on misleading claims, the disclosure requirements, and the contract rules.
Charge $90 a month up front for disputes anyone can file free? On that reading, legal. File the paperwork with the IRS once and the statute stops applying to you forever. That is why it gets called a loophole.
So that is the theory. Here is what actually happens to it — four separate places where it meets resistance.
First: what the courts have said about it
Judges reached this argument a long time ago and did not buy it.
In Zimmerman v. Cambridge Credit Counseling Corp., 409 F.3d 473 (1st Cir. 2005), the First Circuit held the exemption did not apply “simply because they had registered as section 501(c)(3) entities.” To qualify, an organization:
“must actually operate as a nonprofit organization and be exempt from taxation under section 501(c)(3).”
The emphasis is the court’s. The same court reaffirmed it in Zimmerman v. Puccio, 613 F.3d 60 (1st Cir. 2010).
And here is the part that matters most: the burden sits on the organization. A consumer does not have to prove a charity is fake. The charity has to prove it is real — with its books open, in front of a federal judge.
That is the opposite of what a good loophole does. A good loophole ends the argument. This one starts one, on the defendant’s dime, about the exact subject the defendant least wants examined.
The honest limit: those are First Circuit decisions, covering New England and Puerto Rico. I could not find a Sixth Circuit case adopting the same test, and the lawsuit below was filed in Michigan, which sits in the Sixth. So this is persuasive there, not automatically binding. Anyone who tells you the question is settled nationwide is telling you more than the case law does.
Second: where the FTC fits, and why that got complicated
Here I have to correct something I assumed when I started, because the honest answer is more interesting than the one I expected.
I assumed the FTC Act simply reached everybody. It does not. The FTC’s authority under 15 U.S.C. § 44 covers a corporation “organized to carry on business for its own profit or that of its members.” For years the working understanding was that this let the FTC reach sham nonprofits — outfits incorporated as charities but run for someone’s profit — and the agency brought exactly those cases.
Then in August 2024, in FTC v. Grand Canyon Education, a federal judge in Arizona read that sentence more narrowly: the statute asks how an entity is organized, not how it is operated. On that reading, an entity holding a valid nonprofit charter and IRS recognition sits outside the FTC’s reach even if it behaves like a business. In August 2025 the FTC dismissed that case rather than take the question up on appeal, so the ruling was never tested by a higher court.
That leaves an unresolved question, and it cuts the opposite way from CROA. Under CROA, courts look through the paperwork to how you actually operate. Under the FTC Act — at least in that one decision — the paperwork may be what counts.
Two cautions before anyone builds on that. Grand Canyon is a single district court opinion, not an appeals ruling, and other courts need not follow it. And the FTC Act gives consumers no private right of action anyway — you personally cannot sue under it. So a narrowing of FTC reach hands consumers no weapon; it removes a watchdog and puts nothing in its place.
So this is a wall that has developed a crack. It did not stop the FTC historically. Whether it slows the FTC going forward is genuinely open.
Third: general consumer-fraud law is a different door
There is a distinction here that decides real cases, and it is worth getting straight. A state’s credit-repair-specific law may copy the federal carve-out — Michigan’s does, as I show below. A state’s general consumer-fraud law usually does not. The vast majority of states have unfair-and-deceptive-practices statutes that courts apply to nonprofits engaged in commercial conduct, though a minority limit or exclude charitable activity, so it is worth checking how your own state handles it.
That is the route the plaintiff below took. Her second count is brought under the New Jersey Consumer Fraud Act, a general consumer-fraud statute with no credit-repair nonprofit carve-out in it.
A loophole that only closes one of the several doors into a courtroom is not much of a loophole.
Fourth: the contract clause that tries to lock it in
This is the piece that most often gets a company into trouble rather than out of it.
If a company believes it is exempt, the tempting next move is to write that into the contract — a clause saying CROA does not apply here. But 15 U.S.C. § 1679f says any waiver of a CROA protection is void, and that any attempt to obtain such a waiver is itself treated as a violation of the statute.
Think about what that does. If the organization genuinely is exempt, the clause is unnecessary. If it is not exempt, the clause hands the plaintiff an extra argument — and § 1679f(c) addresses contracts that fail to comply with the law.
I should be careful here, because this is not settled. A court could distinguish between a consumer surrendering a right and a company asserting in good faith that the statute does not cover it, and I am not aware of an appeals court squarely holding that a disclaimer of coverage is a waiver. But it is a fight the clause invites and does not win.
The clever move only pays off in the world where you did not need it.
The part that makes it bigger than one statute: Michigan copied it
This is the piece I did not expect, and it is the reason I stopped calling this a simple dead end.
Most states have their own credit repair law sitting alongside the federal one. The lawsuit below was filed in Michigan, so I read Michigan’s. The Credit Services Protection Act, MCL 445.1822, defines who it governs, and then lists who it does not. Item (ix) on that list:
“Credit services organization does not include … a nonprofit corporation that is exempt from taxation under section 501c(3) of the internal revenue code, 26 USC 501c(3).”
Word for word, the same carve-out. So in Michigan a 501(c)(3) sits outside the federal credit repair law and outside the state credit repair law.
Michigan is the one I read line by line, so it is the one I will vouch for. But it is not unusual: state credit services statutes tend to carry a standard set of exclusions — licensed attorneys, banks and credit unions, and 501(c)(3) nonprofits — and the nonprofit exclusion shows up repeatedly across them. If you want to know where you stand, look up your own state’s credit services act rather than assuming the federal rule is the whole picture.
The point is that CROA is not the only place this exclusion lives. At least one state legislature wrote the identical sentence into its own credit repair law, which makes the exemption wider than a reader of the federal statute alone would assume — and worth checking in your own state rather than guessing.
Which raises the obvious question: then what is left?
General consumer-fraud law is what is left, and this is the whole reason the case below looks the way it does. It is a private lawsuit brought by one consumer, not a government enforcement action — and remember, the FTC Act gives her no private right of action to use. So she has two doors: CROA, where the defendant will argue the exemption, and a general state consumer-fraud statute, where there is no credit-repair carve-out to argue about at all. She walked through both, and her second count is the New Jersey Consumer Fraud Act.
That is the practical shape of this thing. The nonprofit label does not make an organization untouchable. It strips away the statutes written specifically for credit repair — the ones with the advance-fee ban and the disclosure rules — and leaves the general ones. It does not end the fight. It changes which law the fight happens under, and makes a consumer work harder to get there.
So how big is it, really?
Somewhere between the two, and I think that is the useful answer rather than a disappointing one.
It is more than a technicality. It is written into federal law, reproduced word for word in at least one state’s credit repair act, and it genuinely removes the rules built specifically for this industry — the advance-fee ban, the disclosures, the contract requirements.
But it is a long way from immunity. Every federal appeals court to address it has required genuine nonprofit operation, with the burden on the organization. General consumer-fraud law carries no such carve-out. The IRS can examine the status the whole structure rests on. And the contract clause used to claim the exemption starts an argument rather than ending one.
What it reliably does is change which law a dispute happens under, and make a consumer work harder to get there. Two things follow from that which no court touches:
Friction. A defense does not have to win to work. Raising the exemption forces a consumer to litigate past it. Most people who paid $90 a month and got nothing will never file a federal lawsuit at all. The strategy can fail in court and still succeed in the 99% of cases that never reach one.
Trust you did not mean to extend. This is the real one, and no statute governs it. “Nonprofit” and “foundation” arrive pre-loaded. They quiet the part of your brain that asks skeptical questions, at exactly the moment you need it awake. That happens on the sales call, years before a judge is involved.
Which is why I think the most useful place to look is not the statute at all. In the law, this is contested ground with real limits on both sides. In the moment someone reads the word “nonprofit” on a website and relaxes, there is no contest at all.
The lawsuit that sent me looking
The case is Watts v. Youth Financial Literacy Foundation, Case No. 2:26-cv-12656, filed July 31, 2026 in the U.S. District Court for the Eastern District of Michigan. A New Jersey consumer named Theresa Watts sued a Michigan organization that does business as United Credit Education Services.
I have reproduced the entire complaint on this site, word for word, with nothing summarized — because you should be able to read the allegations in the plaintiff’s own words rather than take mine for them. The docket is also public on CourtListener.
Everything below is an allegation. Nothing has been proven, the organization has not yet filed a response, and it may dispute all of it. I am summarizing what the complaint says, not what a court has found.
What the complaint alleges happened
According to the complaint, Watts was trying to improve her credit and came across the organization in about August 2021. She says it told her it would get items removed from her credit report by disputing them with the credit bureaus, and that her score would improve as a result. She alleges it promised the negative information would come off, and that results would arrive within a few months.
The allegation that matters most, to my eye, is this one: she says the organization represented it could remove information from her credit reports regardless of whether that information was accurate. Nobody can do that lawfully. Accurate, current, negative information stays. If that representation was made, it was a promise that could not be kept by anyone.
She says she was never required to sign a contract, but was pointed to terms and conditions — and that those terms indicated the organization was a 501(c)(3) and therefore exempt from the Credit Repair Organizations Act. She alleges she paid money up front, before any work was done, and then $90 a month after that, for roughly a year.
What she says she got: no removals, no score improvement, and dispute letters she was expected to send herself, which she alleges did not work. She says she cancelled because she could no longer justify almost $100 a month for nothing, and that she was not refunded for services she alleges were never performed.
That last sequence is why this case is a clean illustration rather than just a story. Paying before the work is done is precisely what § 1679b(b) forbids — if the law applies. Which is exactly what the nonprofit question decides.
Want to see this for yourself? Do not rely on my summary. Read Watts v. Youth Financial Literacy Foundation, Case No. 2:26-cv-12656 — I have published every numbered paragraph of the complaint, the claims for relief and the remedies sought, exactly as filed. It takes about ten minutes, and it is the clearest picture of how this argument gets made that I can give you.
How the case maps onto everything above
The complaint runs two counts, and between them they touch every piece described earlier.
Count I is the Credit Repair Organizations Act. It alleges the organization used its 501(c)(3) status to claim exemption while not genuinely operating as a nonprofit — the Zimmerman question exactly. It alleges advance fees under § 1679b(b), misleading representations about what the service could deliver under § 1679b(a)(3)-(4), missing disclosures under § 1679c, contract failures under § 1679d, and — the waiver problem — that the contract “seeks to disclaim the entire applicability of the CROA,” which § 1679f treats as a violation in itself.
Count II is the New Jersey Consumer Fraud Act. A general consumer-fraud statute, with no credit-repair nonprofit carve-out in it. That is the other door, and the reason it is there is the whole point of this article.
So the case will likely turn on a threshold question before anyone argues about credit scores at all: is this organization, in fact, operating as a nonprofit? If yes, Count I may never reach the merits. If no, the exemption evaporates and every one of those CROA claims becomes live.
What its own filings say
The complaint’s money allegations are pleaded “upon information and belief,” which is lawyer for we believe this but have not proven it. Thin on its own. But a 501(c)(3) files a public Form 990 every year, so anyone can go look.
Its EIN is 80-0056165 and it has been tax-exempt since December 2003. Its stated purpose, in its own words on its Form 990, is:
“THE PURPOSE OF THE YOUTH FINANCIAL LITERACY FOUNDATION IS TO PROMOTE FINANCIAL UNDERSTANDING AND KNOWLEDGE AND INSTILL HABITS FOR SOUND MONEY MANAGEMENT AND LIFELONG LEARNING.”
Financial education. The filing says nothing about credit repair, disputes or credit reports. Its IRS category is Arts, Culture and Humanities / Printing, Publishing.
Here I have to be careful, because the obvious number is a trap. The Form 990 line for officer and key-employee compensation shows $3,403,551 in fiscal 2019 — but that same year reports $0 in other salaries, while neighbouring years report $1.9m to $3.1m. That is a reporting artifact: compensation booked onto one line, not a sudden six-fold raise. So the honest comparison is total reported compensation:
| Fiscal year | Total revenue | Officers & key employees | Other salaries | Total compensation |
|---|---|---|---|---|
| 2017 | $4,749,485 | $394,030 | $1,927,698 | $2,321,728 |
| 2018 | $5,352,694 | $577,291 | $2,430,353 | $3,007,644 |
| 2019 | $6,464,517 | $3,403,551 | $0 | $3,403,551 |
| 2020 | $13,456,358 | $899,458 | $3,072,810 | $3,972,268 |
| 2021 | $6,961,038 | $961,920 | $3,106,220 | $4,068,140 |
| 2022 | $2,261,001 | $92,336 | $1,781,060 | $1,873,396 |
| 2023 | $1,965,549 | $175,000 | $668,732 | $843,732 |
The complaint alleges compensation “over $500,000.00” annually. On the officer and key-employee line alone, the filings report more than that in 2018, 2019, 2020 and 2021.
The plaintiff says she signed up around August 2021. That year the organization reported $6,961,038 in revenue and $4,068,140 in total compensation — about 58 cents of every dollar it took in going to the people who worked there.
Two fairness points. Paying people well is not illegal, and a large organization can carry large salaries honestly. And the recent picture differs: for fiscal 2025 the organization reported revenue of $3,344,008 with executive compensation of $179,028, its president at $101,923, its treasurer and secretary at zero.
The figure I keep returning to is another one. In fiscal 2023 the organization reported one program service, which spent $2,458,895 and brought in $1,965,549 of revenue. That is a fee-for-service operation — people paying for something — rather than a charity distributing funds. Of that $2.46 million in program spending, $59,513 went out as grants: four college scholarships.
None of that proves the lawsuit. It is context, and nobody needed permission to look at it, including me.
What happened in the earlier federal case
Youth Financial Literacy Foundation was a named defendant in Federal Trade Commission v. Financial Education Services, Inc., filed in the same district in May 2022 and terminated in August 2024 — the party list is public. That case ended in a $324 million judgment and lifetime bans on credit repair and multi-level marketing for the defendants it covered. I covered the FTC case when it was filed and the $10.9 million refunded to 443,000 people this March.
I want to be exact about that outcome rather than leave an impression. In its August 2024 announcement the FTC stated that “Defendant Parimal Naik, along with Financial Education Services, Inc., United Wealth Services, Inc., VR-Tech, LLC, Youth Financial Literacy Foundation, and LK Commercial Lending LLC will be permanently prohibited from numerous forms of unlawful activities related to credit repair services and pyramid schemes,” required to turn over $5.5 million and to run a compliance monitoring system. The settlements were entered without any defendant admitting the allegations.
So the tax-exempt status did not keep this foundation out of a federal enforcement action, or out of the conduct prohibitions that ended it. Whether the agency could bring that same case as easily today, after Grand Canyon, is exactly the open question above.
A caution, because names in this corner of the industry are genuinely confusing: Financial Education Services and United Credit Education Services are different names and I am not asserting they are one business. What the public record shows is that Youth Financial Literacy Foundation appears as a defendant in that action.
What I would actually do with this
I am not telling you to avoid nonprofits. I ran one. Some of the most decent people I have known in this field spent careers inside one, doing unglamorous work with no upside for themselves. This is the same trap I have written about in nonprofit credit counseling and in what the IRS data shows about that sector: the label does a great deal of persuading and very little promising.
Drop the reflex, not the category:
- Read the Form 990 before you sign. Search the name on ProPublica’s Nonprofit Explorer. Free, two minutes. Compare revenue against compensation, and see how much actually leaves as charity.
- Compare the stated mission to the sales pitch. If the 990 says financial education and the phone call sells monthly credit disputes, you have found the question worth asking. The IRS activity category is self-reported — it tells you what the organization said about itself, not what anyone verified.
- Look at Schedules L and R of the 990. That is where money moving to related for-profit companies and interested persons has to be disclosed. A charity routing large sums to affiliates with overlapping officers is the “does it operate as a nonprofit” question answered in cash.
- Treat a CROA disclaimer as a red flag, not a fact. Under § 1679f, trying to get you to waive those rights is itself a violation. Run any contract through my free Contract Decoder.
- Never pay in advance for credit repair, whatever the tax status. If you already did and got nothing for it, here’s how to get your money back.
- The FTC keeps bringing these cases. Its case against a $200 million credit repair operation accused of targeting military servicemembers through Google ads alleges exactly the advance-fee pattern described above.
- Remember disputes are free — and nobody can remove accurate, current information, charity or not.
- You can report a charity you believe is a front. IRS Form 13909 is the tax-exempt organization complaint form. Not being a regulator does not make you powerless.
Frequently Asked Questions
Is the nonprofit exemption in the credit repair law a real loophole?
It is real, but narrower than it looks. The carve-out exists in federal law, and at least one state has copied it verbatim — Michigan’s Credit Services Protection Act contains the same 501(c)(3) exclusion — so it does remove the rules written specifically for credit repair. But every federal appeals court to address it requires an organization to actually operate as a nonprofit, with the burden on the organization, and general consumer-fraud statutes contain no such carve-out. It changes which law a case is brought under rather than preventing one.
Does the Credit Repair Organizations Act apply to nonprofit organizations?
15 U.S.C. § 1679a(3)(B)(i) excludes nonprofits exempt under section 501(c)(3). But in Zimmerman v. Cambridge Credit Counseling Corp., 409 F.3d 473 (1st Cir. 2005), the First Circuit held an organization “must actually operate as a nonprofit organization and be exempt from taxation under section 501(c)(3)” — registration alone is not enough, and the organization carries the burden of proving it qualifies.
Can a contract say the Credit Repair Organizations Act does not apply?
It can say so, but 15 U.S.C. § 1679f makes any waiver of a CROA protection void and unenforceable, and treats any attempt to obtain such a waiver as a violation of the statute in its own right. Section 1679f(c) also addresses contracts that fail to comply with the law.
How can I check whether a nonprofit operates like one?
Read its Form 990 — every 501(c)(3) files one annually and they are public. ProPublica’s Nonprofit Explorer is free and searchable by name. Look at revenue against compensation, how much goes out as grants or assistance, and whether the stated mission matches what you were sold.
How long do I have to bring a claim under the credit repair law?
Under 15 U.S.C. § 1679i, within five years of the violation — or, where a credit repair organization materially and willfully misrepresented information it was required to disclose, within five years of the date you discovered the misrepresentation.
One last thing
If you are reading this because you already paid an organization like this and nothing changed: that was not a stupid decision. You were sold certainty by an operation wearing the most trustworthy word in the English language — and the statute itself half-agrees the word means something. Wanting your credit fixed is not a character flaw.
Look forward rather than spending five years repairing the past. What you paid is gone. What you do next is not.
As always, this is my input, not my instruction. I am not your lawyer and I do not know your situation. If you think you have a claim, talk to a consumer attorney who does — the National Association of Consumer Advocates can help you find one.
If you know someone about to hand money to a “nonprofit” credit repair outfit, send them this before they sign. That is the entire reason I wrote it down.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



