

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed August 4, 2026 • Every claim below links to a primary source.
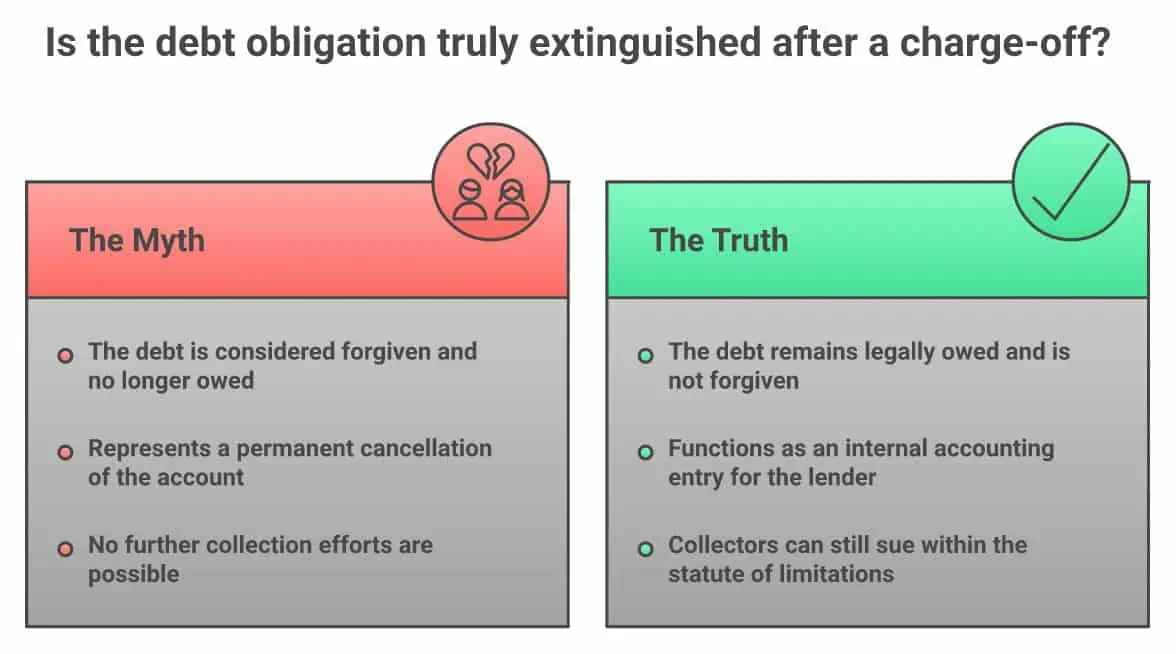
The verdict: Myth. A charge-off is the lender’s own bookkeeping entry, not a legal release of your debt — you still owe every dollar, and the account is routinely sold to a debt buyer who can pursue you in court within your state’s statute of limitations. The federal Uniform Retail Credit Classification and Account Management Policy sets the 120/180-day rule that forces the charge-off — and it’s purely a bank-bookkeeping standard, silent on whether you’re still on the hook. As the CFPB puts it plainly: a debt doesn’t generally expire or disappear until it’s paid.
Well, Actually…
I hear a version of this belief constantly: “They charged it off, so it’s their loss now — not mine.” I understand exactly why it sounds true. “Charged off” sounds final. It sounds like the bank gave up and moved on. And if you log into your account and the balance is gone, or a collector stops calling for a while, it can feel like the debt evaporated.
Here’s the part nobody explains: a charge-off is an internal accounting move, not a legal one. Federal banking regulators direct banks and thrifts to classify a loan as a loss on their books once it’s badly delinquent — 120 days past due for a closed-end loan like a car loan or personal loan, and 180 days past due for an open-end account like a credit card (mortgages and home-equity loans follow their own separate, collateral-based version of this rule) — under the Uniform Retail Credit Classification and Account Management Policy, the joint standard issued by the Federal Reserve, OCC, and FDIC (the OTS also signed on before it was folded into the OCC in 2011; credit unions were never covered — NCUA opted not to adopt it). That policy states it plainly: “Closed-end retail loans that become past due 120 cumulative days and open-end retail loans that become past due 180 cumulative days from the contractual due date should be classified Loss and charged off.”
Notice what that rule is actually protecting: the bank’s own financial statements, and by extension the safety of the banking system. It has nothing to do with whether you legally still owe the money. You do. The account usually gets sold — often for just a few cents on the dollar (the FTC’s own study of the debt-buying industry found buyers paid an average of about 4 cents per dollar of face value, and roughly 2 cents for debt six to fifteen years old) — to a debt buyer, who now owns the legal right to collect the full balance, plus whatever fees and interest your original agreement and state law allow. Or the original creditor keeps trying to collect directly, or refers it to a collection agency, or sues you. Charging it off just means the original lender stopped carrying it as an asset. It didn’t stop being your debt.
Once they charge it off, I don’t owe it anymore — they wrote it off their books, so it’s gone.
Charging off a debt is the creditor’s own accounting decision, forced by banking regulators after months of nonpayment — it is not forgiveness and it does not touch your legal obligation to pay. The debt is routinely sold to a debt buyer or referred to a collection agency, and it can still be pursued in court, including through a lawsuit, as long as it’s within your state’s statute of limitations.
Uniform Retail Credit Classification and Account Management Policy, Federal Reserve FRRS 3-1502
There’s a related mix-up worth flagging here, because it involves a completely different clock. The seven-year credit-reporting window and the statute of limitations on being sued are two separate rules, and mixing them up is one of the most common and most expensive mistakes I see. Under the Fair Credit Reporting Act, a charged-off account generally must come off your credit report seven years after your original delinquency date — that’s a reporting rule, and it has zero effect on whether you’re still legally on the hook. Separately, your state’s statute of limitations limits how long a collector has to sue you, typically three to six years, and it runs on its own schedule. A debt can fall off your credit report and still be perfectly suable. It can also become time-barred for a lawsuit and still exist and still be reportable. I’ve written a full, separate breakdown of that myth here: They Said Once a Debt Falls Off Your Credit Report, You Don’t Owe It Anymore. Not True.
Why You Were Told This
I don’t think anyone is deliberately spreading this myth to profit from it — if anything, believing it works against you. The confusion comes honestly from the word itself. “Charged off” is bank-examiner language borrowed from accounting, and it leaked into everyday conversation carrying a meaning it was never meant to have. When your online banking balance disappears or your statements stop showing up, the intuitive read is “this is over.” I get why that feels true.
But here’s who the confusion actually helps: whoever buys your debt next. Debt buyers purchase charged-off accounts in bulk, often for a few cents on the dollar, precisely because so much of that debt is still fully collectible — the original balance, sometimes still accruing interest and fees depending on your state and contract. A borrower who believes the debt vanished is a borrower who doesn’t open the next collection letter, doesn’t respond to the next lawsuit summons, and ends up with a default judgment they never contested. The myth doesn’t protect you. It sets you up to be caught flat-footed.
What to Actually Do
- Assume you still owe it. A charge-off is a status, not a payoff. Verify the account, the balance, and who currently owns the debt before you do anything else.
- Check your state’s statute of limitations before you respond to anyone. Use the free Statute of Limitations Checker to see whether the debt is still within the window a collector could sue you.
- Never make a payment or a written promise to pay on old debt without knowing the rules first. In some states, even a small payment or a written acknowledgment that you owe the debt can restart the statute of limitations clock and expose you to being sued again, per the CFPB.
- Pull your credit reports and check the dates. The charge-off should generally drop off about seven and a half years after your original delinquency date — the FCRA’s seven-year clock doesn’t start until 180 days after your first missed payment, per 15 U.S.C. §1681c(a)(4), (c)(1) — not from when the debt was sold or resold. If a debt buyer is re-reporting a newer date to keep it alive longer, that’s a disputable error.
- Know your real options before you negotiate anything. Because charged-off debt is often bought for a fraction of its face value, there’s frequently room to settle for less — but forgiven debt is generally taxable income, and creditors report cancellations of $600 or more to the IRS on Form 1099-C. Real exceptions exist: canceled debt is excluded if you were insolvent, and it’s excluded entirely if the debt is wiped out in bankruptcy. Run the numbers with the free Do You Owe Tax From a 1099-C? calculator before you agree to anything.
- If you’re already sued, don’t ignore it. A summons for a charged-off debt is real and answering it matters — see my guide on being sued for debt for your deadlines and defenses.
- If multiple accounts have charged off, look at the whole picture, not just this one. The Find Your Path quiz and the free debt relief options comparison can help you see whether settlement, a payment plan, or bankruptcy actually serves your future best — without anyone trying to sell you something.
- Want the full walkthrough? I go deeper on the credit report timeline, how to dispute a charge-off error, and what a “paid charge-off” notation actually does for you in What Is a Charge-Off? It Doesn’t Mean the Debt Disappears.
Steve’s Take
I’ve watched this exact misunderstanding blow up in people’s faces more times than I can count. Someone stops opening their mail because they’ve decided, reasonably enough given the language, that a charged-off account is a closed chapter. Eighteen months later they’re served with a lawsuit summons for the full balance plus interest, and they had no idea it was even still alive. That’s not bad luck — that’s a vocabulary problem with real financial consequences.
Here’s my honest read: a charge-off is actually useful information, if you understand what it’s telling you. It tells you the original creditor has written the account off as a loss and, more often than not, the account is about to change hands — to a debt buyer, a collection agency, or a lawyer, even while the original creditor may keep trying to collect too. That’s the moment to figure out your real options, not the moment to relax. Know your statute of limitations. Know whether the debt is worth fighting, settling, or including in a bankruptcy filing if things are bigger than just this one account. Deal with it deliberately instead of hoping it quietly disappeared, because it almost certainly didn’t.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
Frequently Asked Questions
Free Tool — 1099-C Tax Calculator: Received a 1099-C for cancelled debt? The free 1099-C Tax Calculator runs the exact IRS insolvency math from Publication 4681 Worksheet 2 — and covers the partial insolvency case most people miss. Run the Calculator →
Do I still legally owe a debt after it’s charged off?
Yes. A charge-off is the creditor’s internal accounting decision to write the debt off as a loss for financial reporting purposes — it does not release you from the obligation to pay. The debt is commonly sold to a debt buyer or handed to a collection agency, and it can still be pursued, including in court, within your state’s statute of limitations.
Why do lenders charge off debt at 120 or 180 days?
Federal banking regulators direct it. Under the Uniform Retail Credit Classification and Account Management Policy, closed-end loans (like auto or personal loans) should be classified as a loss and charged off at 120 cumulative days past due, and open-end accounts (like credit cards) at 180 cumulative days past due. (Mortgages and home-equity loans follow their own separate, collateral-based 180-day rule.) It keeps a bank’s financial statements accurate — it has nothing to do with releasing you from the debt.
Can a debt collector still sue me after my account is charged off?
Yes, as long as the debt is still within your state’s statute of limitations — typically three to six years according to the CFPB, though it varies by state. The CFPB notes collectors can still contact you, resell the debt, and sue you for a judgment even after the statute of limitations runs — a court can still enter judgment against you if you don’t show up and raise the time-barred defense yourself.
What’s the difference between the 7-year credit reporting rule and the statute of limitations?
They’re separate rules that don’t reset each other. The Fair Credit Reporting Act limits how long a charged-off account can appear on your credit report to seven years, measured from 180 days after your original delinquency date (15 U.S.C. §1681c(a)(4), (c)(1)) — roughly seven and a half years total. The statute of limitations limits how long a collector has to sue you, which is a state-law question and often a different length of time. A debt can be gone from your report and still legally suable, or time-barred for a lawsuit and still show up on your report.
Will making a payment on a charged-off debt restart the clock?
In some states, yes. Making even a partial payment, or acknowledging in writing that you owe an old debt, can restart the statute of limitations, giving a collector a fresh window to sue you. A few states treat a verbal acknowledgment the same way, but most require it in writing — which is exactly why you check your state’s rule before you say anything to a collector. Confirm your state’s rules before you pay anything on an old, charged-off account — see the CFPB’s guidance on old debts.
Does paying off a charge-off remove it from my credit report?
Not automatically. Paying changes the notation to “paid charge-off,” which some lenders view slightly more favorably, but the negative mark generally stays on your report until the seven-year-plus reporting window expires. Some collectors will agree to a “pay for delete,” but most original creditors won’t — their data-furnishing agreements with the credit bureaus generally don’t allow deleting an accurate tradeline just because it was paid, and the CFPB warns that anyone promising to remove accurate, negative information is likely running a credit repair scam. Never pay based on that promise alone — get any such agreement in writing first.
If my debt gets sold after a charge-off, does the new owner have the same right to collect?
Yes. A debt buyer takes over the original creditor’s rights and can pursue the balance. But it can only add interest, fees, or other charges if your original agreement or state law expressly allows it. That limit comes from the Fair Debt Collection Practices Act (15 U.S.C. §1692f(1)), and the FTC says the same thing in plain language: collectors “can’t try to collect interest, fees, or other charges on top of the amount you owe, unless the original contract or a law says they can.” It’s still worth verifying the debt and asking for documentation before paying anyone who contacts you claiming to own it.
This reflects what I’ve learned helping people navigate debt since 1994 — it’s one informed perspective, not a legal opinion about your specific situation. Only you and, where the stakes are high, a licensed attorney in your state can weigh the whole picture and decide what’s right for you.
The bottom line: A charge-off is the bank’s paperwork, not a pardon — you still owe the money, and it can still come after you in court. If someone you know just breathed a sigh of relief because a debt “got charged off,” send them this before they find out the hard way.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



