

Quick Answer: Damon Day — the debt advisor I recommend more than anyone else, and the guy I started The Penny Stupid Project with back in 2022 — posted a new video where he narrates chasing the last $76 of his $500 weekly gig-work goal, out loud, in real time. He took one shop that broke his own usual rules to get there faster. He turned down several that didn’t come close. And he quit $25 short of the number rather than keep grinding for it. That’s what happened to him on that one Sunday — not a typical hourly rate, and not a promise of what you’d make. The real value is watching a goal change his math, live, before your eyes.
Debt is math wrapped in emotion — and so is a number you’ve decided matters. Watch what “I’m almost there” does to good math, even for someone who does this for a living.
If you read my first write-up of Damon’s DoorDash video or the one about the offers he rejected, you already know the backstory. If this is the first one you’ve landed on: Damon and I started something called The Penny Stupid Project together in 2022 — a public, no-BS test of side hustles where neither of us sold anything. My half was retail arbitrage and Amazon FBA. Damon’s half was gig delivery. He’s run with it since, and his channel is still called The Penny Stupid Project on YouTube. I tell you I helped start it every time I feature his videos, because you deserve to know where I stand before you take my recommendation.
His newest video, posted August 5, 2026, is titled “I Needed $76 to Hit My $500 Goal—Would I Chase Bad Orders?” The setup is simple and honest: it’s Sunday evening, he’s $424 into a self-set weekly goal of $500, and he decides to go chase the last $76 before the night’s over. What follows is a real-time test of whether a number in his head changes what he’s willing to accept.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 11): You drive to the dealership to pick up the car. There is no car. There was never a car.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
What the $76 Chase Actually Looked Like
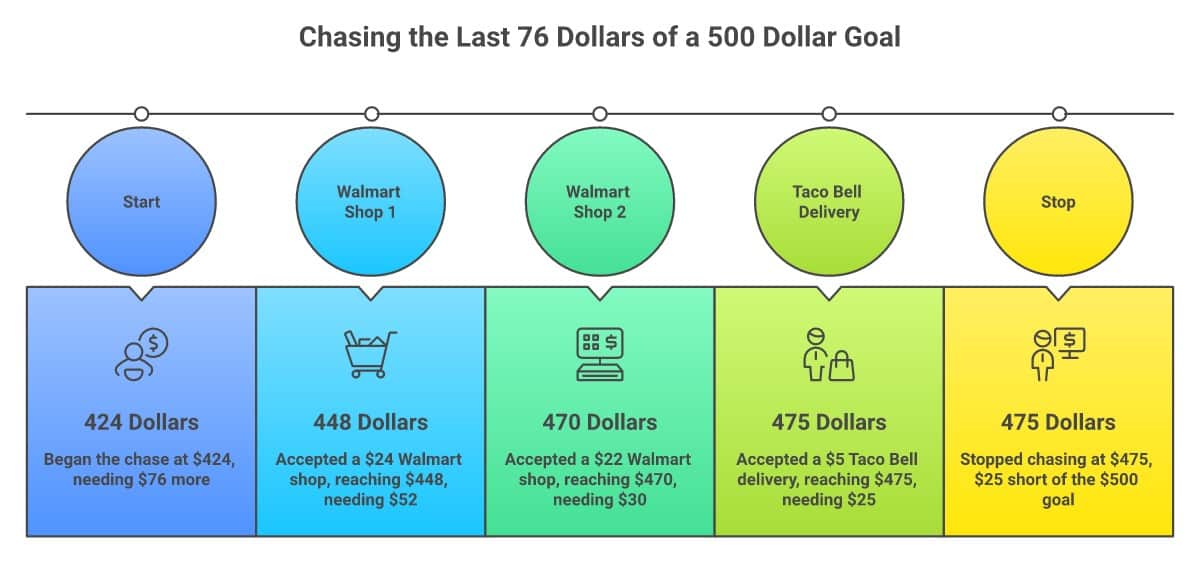
Damon turns his apps back on around 6:15 p.m., $76 short of $500 for the week. Here’s the order of what happened, offer by offer:
- Accepted — $24 Walmart shop. He admits on camera he didn’t even fully check it before taking it: it turned out to be 18 items going about 6 miles, more than he’d normally take. He admits afterward that needing the $76 is the only reason he took it. Running total: $448. Needed: $52.
- Declined — $12 Uber offer, 13 miles. No hesitation.
- Declined — pickup at a restaurant, 8.8 miles, 22 minutes total. He passes without hesitation.
- Declined — $7.25 Chipotle pickup, 4.4 miles. This one he talks himself out of in real time — more on it below.
- Accepted — $22 Walmart shop, 10 items, 5 miles, still inside his normal delivery zone. This one clears his bar. Running total: $470. Needed: $30.
- Declined — $11 Uber offer, 20 miles. He doesn’t treat it as a serious offer.
- Accepted (deliberately, as a demonstration) — $5 Taco Bell delivery, half a mile. More on this one below too. Running total: $475. Needed: $25.
- Quit. Rather than keep working for the last $25, he calls it and drives home.
Short of his self-set $500 weekly goal when he turned his apps back on
Earned in about 1 hour 51 minutes of chasing it
Short of the goal when he decided it wasn’t worth chasing any further
Figures are what Damon logged on this one outing — not typical pay, an average, or a projection.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The Chipotle Lesson: “It’s Close” Isn’t the Same as “It’s Worth It”
This is the single best teaching moment in the video, and it’s worth slowing down on. A $7.25 offer comes in: pick up at Chipotle, 4.4 miles away. Damon’s first instinct, spoken out loud, is almost a talk-himself-into-it moment — he starts to say it isn’t that bad. Then he stops himself mid-sentence and corrects it: it is bad. The offer covers the 4.4 miles to the pickup, but he has to drive back too, so he is really being asked to drive close to nine miles for $7.25. Once he says the round-trip number out loud, he declines it.
Why the Round Trip Is the Real Number
An app shows you the miles to the pickup. It doesn’t show you the miles back. A “4.4-mile” offer that starts and ends near your own location is really an 8.8-mile round trip once you count the drive home — and $7.25 for 8.8 miles works out to about 82 cents a mile of revenue. The IRS’s own 2026 standard mileage rate is 76 cents a mile as of July 1 — a figure the IRS calculated from what gas, maintenance, tires, insurance and depreciation actually cost per mile. That leaves roughly 6 cents a mile — about 53 cents total across the whole trip — to pay Damon for his time, the wear the IRS rate doesn’t fully capture, and the risk of driving at all. That’s the math an offer that “looks close” is hiding.
The $5 Order He Took on Purpose
Later, a $5 Taco Bell delivery pops up — half a mile away. Damon doesn’t take it because he thinks it’s good money. He says so before he even accepts it — he is taking it specifically to demonstrate why he normally won’t. It’s a deliberate demonstration, not a real bet.
It happens to go fast — about six minutes door to door, because the restaurant and the drop were both right in his path. He jokes about how great it would look if you annualized that one quick run out into an hourly rate — and then immediately undercuts his own joke, noting sarcastically that of course they always work out that way. He’s calling out the trap on himself in real time: one lucky, fast $5 order doesn’t turn $5 orders into good math. He follows it with the old line about how even the sun shines on a dog some days. One unicorn doesn’t change the herd.
When “Almost There” Changes Your Math
Damon says the quiet part out loud when he takes that first $24 Walmart shop despite it running longer and going farther than he’d normally accept. He acknowledges that some of the offers he’s taking are below what he’d usually do, because his goal at that moment is simply to reach the $76 — not to maximize what he earns per hour.
That’s an honest, specific admission that a number he’d set for himself — not the market, not his own usual floor, just a target in his head — temporarily loosened his rules. I see this exact pattern constantly in people managing debt, not just gig offers: “I’m only $200 from paying off this card” leads to skipping the emergency fund. “I’m so close to my savings goal” leads to picking up a payday loan to cover a gap instead of missing a deposit. The number itself starts making decisions that your actual math wouldn’t make on its own. Damon’s honest about it happening to him in a $24 shop. It’s worth noticing when it happens to you in something bigger.
Knowing When to Stop
The flip side of that same video is Damon not letting the goal win. After the $5 Taco Bell run puts him $25 from $500, he keeps declining — a spam non-offer from his usual Walmart store, nothing worth taking. And then he stops chasing it — he decides he isn’t going to sit out there nickel-and-diming his way to a round number, because the last $25 doesn’t change anything that matters. He drives home.
Both things are true in the same 20-minute stretch of his life: the goal pulled him into one shop he wouldn’t normally take, and the same goal did not pull him into wasting another hour chasing a round number that, by his own admission, didn’t actually matter. Recognizing which pull you’re feeling — and whether it’s worth listening to — is the whole skill.
Why I’m Not Giving You a Dollar-Per-Hour Number
I want to be direct about this before you take anything in that video as a plan. The $51 he made chasing his last $76, the $475 he logged for the whole week, the $34-an-hour weekly average he says out loud at the end — all of it is what happened to one driver, on one Sunday, in one market (Phoenix-area, in 105-degree August heat he mentions himself, during what he calls the slowest month of his year), on whichever offers that evening’s algorithm happened to show him. It is not a typical hourly rate. It is not an average. It is not what you should expect to make. Gig-delivery and gig-shopping pay varies enormously by city, time of day, day of the week, how many other drivers and shoppers are online, and plain luck in what shows up on your screen.
Any site that shows you a gig-work video and lets you walk away thinking “so I could make about $500 a week doing this” has done you a disservice. The value in Damon’s video isn’t the income figure. It’s the method: catching yourself mid-rationalization on the Chipotle offer, running the round-trip math instead of the one-way number, and being honest on camera about the moment a goal — not the market — changed what he was willing to accept. That’s math literacy you can use no matter what your local market looks like when you try it.
Is Gig Work a Real Tool When You’re Behind on Bills?
I get some version of this question constantly: should I drive or shop for these apps to catch up on debt? My honest answer is the same one I give about every option on this site — it depends on your specific numbers, and most people never actually run them the way Damon does on camera.
Gig work can be a legitimate way to generate quick cash when you need money now and don’t have savings to draw on. You can often start today and get paid within days. That immediacy is real and valuable if you’re closing a short-term gap — a car payment, a medical bill, a shutoff notice. But before you count on it as ongoing income, run your own version of the math Damon runs in this video:
- Mileage costs money whether or not you write it off. The IRS’s own 2026 standard mileage rate is 76 cents a mile as of July 1. Count the round trip, not just the miles the app shows you to the pickup — Damon’s Chipotle offer only turned into a clear “no” once he added the drive back in.
- You owe self-employment tax on top of income tax. Gig platforms pay you as an independent contractor. Nobody withholds anything for you. Set money aside, or the IRS bill next April will wreck the very budget you were trying to fix.
- Watch for your own version of “almost there.” If a target number — a weekly goal, a bill total, a payoff amount — is making you say yes to something you’d normally decline, stop and separate the target from the offer in front of you. The target doesn’t make the offer better.
- Know your own stopping point before you need it. Damon decided that being $25 short didn’t make a difference. Decide your own version of that line before you’re tired, it’s dark, and the number is staring at you.
“Run your own numbers before you count on it” isn’t a cop-out. It’s the same advice I’d give about any debt option on this site. Gig work is a tool, not a rescue plan, and it works best as one piece of a bigger decision — not the whole strategy.
More From the Side Hustle Archive
Damon and I have been writing about this experiment since it started in 2022. A few from the archive that pair well with this video:
- Quick Cash for Bills: Myth vs Reality — the honest version of “I need money fast”
- Online Arbitrage Mistakes: Myth vs Reality — my own rookie mistakes, the flip side of Damon’s rules-first discipline
- Side Hustles: When They Help and When They Hurt — the honest boundaries of what a side hustle can actually fix
- Side Hustle Success: What It Means and What to Do — the mindset piece behind the math
- Damon Day Runs the Penny Stupid Project Now — my write-up of his first video in this series, on the $11 order that wrecked a good hour
- Six Offers Rejected Before Taking One — his rules for saying no fast
- AI Is Changing Work Fast: Side Hustles, Cybercabs, and Protecting Your Financial Future — Damon and I talk through what Tesla’s Cybercab landing in his own gig market means for anyone counting on gig income
Key Takeaway
Damon Day’s newest Penny Stupid Project video shows a target number — his own $500 weekly goal — quietly loosening his rules for one shop, then watches him hold the line on a bad Chipotle offer once he counted the return miles, then take a $5 order on purpose just to prove why $5 orders are bad math. He ended the chase $25 short of his goal and decided that was fine. The $51 he made in under two hours, and the $475 he logged for the week, are what happened to him — not a promise, and not a plan. The real value is watching exactly when and how a goal changes good math, and when it doesn’t.
This is what I’ve seen after more than 30 years of helping people with money and debt. This is one video, one driver, one Sunday — take it as input for your thinking, not a directive. Only you know your full financial situation, what your car actually costs you to run, and whether your time is better spent on this or something else. Nobody gets to tell you what to do with your time or your money. Not me, not Damon, not anyone.
If you know someone who lets a target number talk them into a bad decision — gig work or otherwise — send them this. Watching someone else catch himself doing it, on camera, is worth more than any lecture about discipline.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Common Questions
Who is Damon Day, and why does Steve feature his videos?
Damon Day is a debt advisor I’ve worked with and mentored for years, and the debt advisor I recommend to readers most often, because he builds solutions around a person’s actual situation rather than a one-size-fits-all script. Read the full explanation in Why Do You Recommend Damon Day as a Debt Advisor? His own debt-advice site is damonday.com, listed first in the description of his Penny Stupid Project YouTube channel.
What is the Penny Stupid Project?
The Penny Stupid Project is a side-hustle testing effort Damon and I started together in 2022 at pennystupid.com. Damon has run with it since — it’s his work now rather than a joint operation, and I disclose that I helped start it every time I feature his videos so you know where I stand. Neither of us sells anything through it; the point was, and still is, to test income opportunities in public and report the real results, including the offers not worth taking.
Did Damon actually hit his $500 weekly goal?
No. He ended the week at $475 — $25 short — and decided that gap didn’t make a difference rather than keep working past a reasonable hour to close it. He said it himself on camera: it would have been nice to see the round number, but not nice enough to justify another hour of chasing it.
Is $475 a week, or $34 an hour, typical gig-work pay?
No. Both are what one gig worker logged in one specific week in one market, during what he described as the slowest month of his year. Gig pay varies by city, time of day, platform demand, and plain luck in what offers appear on your screen — don’t treat any single video’s total, weekly or hourly, as a guarantee or an average.
Why did Damon almost take the Chipotle offer, then decline it?
Because his first instinct only counted the miles to the pickup, not the miles back. Once he added the return trip, an offer that looked “close enough” became $7.25 for roughly 8.8 total miles of driving — barely enough to cover what the IRS estimates a mile of driving actually costs, let alone pay him for his time. Counting the full round trip, not just the one-way distance shown on the offer, is the lesson.
Why did he take the $5 Taco Bell order if it was bad math?
He said so directly before accepting it: to demonstrate, on camera, why $5 orders are a bad habit — even though this particular one happened to go fast because the pickup and drop were both on his existing route. He called it out as a lucky exception immediately afterward, not proof that $5 orders are worth taking as a rule.
What’s the biggest lesson in this video for someone managing debt, not gig work?
Watching a self-set number — his $500 weekly goal — quietly loosen Damon’s own usual rules for one order. The same pull shows up in debt decisions: “I’m so close to paying this off” or “I’m almost at my savings goal” can talk people into a worse decision than the one they’d make without a number staring at them. Noticing the pull is the first step to deciding whether to follow it.
What He Works Through On Camera
YouTube’s auto-generated captions garble names and numbers badly enough that I won’t put them in quotation marks and call them his words — the captions turn Lyft into “Lift” and Fry’s into “fries.” So what follows is my paraphrase of the beats in the video, not a transcript. Watch it above for what he actually says.
His floor rule for shops. Early on he lays out the rule he works by: a shop order has to clear twenty dollars. His point isn’t the specific number — it’s that you set rules and then actually keep them. Exceptions should be rare, and they should obviously make sense at the moment you make one.
Talking himself out of the Chipotle offer. He starts to rationalize it, then catches himself mid-sentence doing exactly that. The offer covers four miles out — but he has to drive the four miles back too. Once he says the round-trip number out loud, the offer is plainly bad. The lesson isn’t the arithmetic; it’s that he had to hear himself say it before he saw it.
Taking a five-dollar order on purpose. He accepts one specifically to demonstrate why he normally won’t — and then it happens to go fast. He immediately names the trap rather than taking the win: one order that works out is not evidence the rule is wrong. That’s the whole lesson in about ten seconds, and it’s the most useful thing in the video.
Why the goal loosened his own rules. He says plainly that at that point he is chasing the seventy-six dollars to hit his number, not trying to make the most per hour. Those are two different objectives, and he names the switch out loud while it’s happening to him.
Calling it quits short of the goal. He decides not to grind out the remainder, on the grounds that the gap doesn’t change anything real. The round number would have been satisfying. It wasn’t worth another hour of taking offers he’d already decided were bad.
His own math for the week. He totals up the week, calls it slightly under where he likes to be, and puts that down to it being summer — the slowest stretch of the year for this work. That is one worker, one week, one market, and it is before a dollar of gas, vehicle wear, or taxes comes out. It is not a wage, and it is not a forecast for anyone else.



