

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed August 5, 2026 • Every claim below links to a primary federal source.
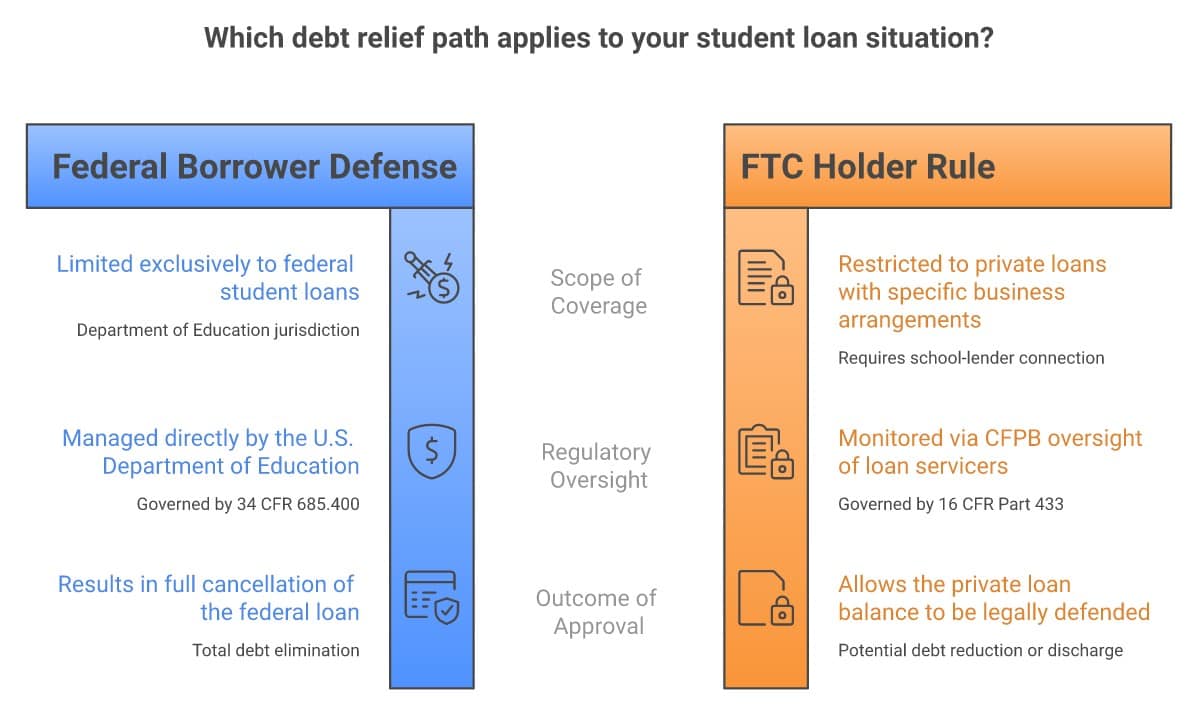
The verdict: Half true — and the half nobody mentions is worth checking tonight. Federal Borrower Defense to Repayment genuinely doesn’t reach private loans, and there is no private equivalent of it — no application, no agency queue, no centralized process. That part of what you were told is correct, and I won’t pretend otherwise. What gets left out is that some private student loan contracts — typically the ones arranged through your school or a “preferred lender” it steered you to — carry a contractual escape hatch, a clause the CFPB says may be required by the FTC’s Holder Rule (16 CFR Part 433), that lets you raise your school’s fraud as a defense against whoever now holds your loan. The CFPB found private student loan servicers were flatly telling borrowers no such option existed — when their own promissory notes said otherwise.
Well, Actually…
I keep running into a version of this on forums where people talk about for-profit colleges that lied about job placement rates, faked accreditation, or flat-out closed with students mid-program. The advice that circulates is always some version of: “Borrower Defense will wipe out your federal loans, but if you had to take out private loans too, you’re just stuck paying those no matter what the school did.” It sounds right — Borrower Defense to Repayment really is a federal program, and the U.S. Department of Education really has discharged $28.7 billion for 1.6 million borrowers — as of May 1, 2024 — who were cheated by their schools, saw their schools abruptly close, or were covered by related court settlements, using only its own federal-loan authority under 34 CFR §685.400 — the same authority behind the automatic federal discharges reported in Sweet v. McMahon — I covered that ruling and its reported scope separately. That part of the belief is completely accurate.
Here’s the part that gets left out. In December 2024, the CFPB published a special report after examining private student loan servicers directly, and it said something borrowers rarely hear: “the Borrower-Defense-to-Repayment regulation does not apply to private student loans” — true — but “other legal protections may allow borrowers to seek to have their private student loans discharged based on school misconduct.” The mechanism is the FTC’s Holder-in-Due-Course Rule, a regulation that’s been on the books since 1975. It is a trade-regulation rule the FTC enforces — not, by itself, a separate right to sue for damages — and it makes it an illegal practice for a school to accept the proceeds of certain loans unless the loan contract contains a specific notice stating that whoever ends up holding the loan — even if it’s been sold three times to a servicer you’ve never heard of — is subject to “all claims and defenses which the debtor could assert against the seller.” Translate that out of legalese: if your school defrauded you, that clause can let you raise the fraud as a defense against your loan, not just against the school.
The CFPB didn’t just find the clause exists. Examiners found private loan servicers telling borrowers in writing that no discharge program was available to them — while the promissory note they’d signed guaranteed the opposite. The CFPB called that a deceptive practice among the private student loan servicers it examined and directed those entities to fix their claims-review process. So the honest verdict isn’t “private loans are covered just like federal ones.” It’s “a real path exists for many private loans, and examiners have caught servicers pretending it doesn’t.”
“Borrower Defense only works for federal loans — if you took out private loans for that for-profit school, you’re stuck paying no matter what the school did.”
The federal Borrower-Defense-to-Repayment regulation genuinely doesn’t reach private loans — the CFPB says so directly. But some private student loan promissory notes — most often those originated through the school or a lender it recommended — carry a contractual guarantee, which the CFPB says may be required by the FTC’s Holder Rule — that lets a borrower assert “any claim the borrower has against their school” against whoever currently holds the loan, including a claim of fraud. In plain terms: your private lender or its debt-collecting successor can be legally on the hook to consider — and potentially wipe out — the loan because of what your school did, not what you did. It’s primarily a shield, not a source of extra cash: the Rule’s own notice language caps what you can recover at the amount you’ve already paid on that loan, so it stops you from owing the balance rather than paying you back more than you put in.
CFPB, Supervisory Highlights: Special Edition Student Lending, Issue 36 (Dec. 2024), § 2.3 & 16 CFR § 433.2 (FTC Holder Rule)
“Okay, so my private loan is automatically covered the same way, right?”
Not automatically, and not every private loan qualifies. The Holder Rule notice requirement generally attaches when the lender is “affiliated” with the school — the school referred you to that specific lender, or there’s a business arrangement between them — the classic setup with in-house or “preferred lender” loans at for-profit colleges, including the in-house loan programs the CFPB sued over at now-defunct ITT Educational Services (ITT Tech) and Corinthian Colleges, before both schools collapsed. A private loan you shopped for independently from an unrelated bank, with no school referral involved, may not carry that clause at all. And even where the clause exists, the CFPB found servicers failed to consider most borrowers’ challenges unless the borrower had hired an attorney — meaning having the right on paper and actually getting it honored are two different fights.
16 CFR § 433.1(d), (f), (g) (definitions: “purchase money loan,” “business arrangement”) & CFPB Supervisory Highlights, Issue 36, § 2.3.2
“If my note doesn’t have that Holder Rule clause, there’s nothing else I can do.”
There can still be other doors. First, bankruptcy: not every private student loan even counts as a protected “student loan” under the Bankruptcy Code. Section 523(a)(8) has three separate ways a loan can be shielded from ordinary discharge — one covers government- or nonprofit-backed loans, one covers an “obligation to repay funds received as an educational benefit, scholarship, or stipend,” and one covers any other loan that’s a “qualified education loan” as defined in the tax code. In Homaidan v. Sallie Mae, the Second Circuit held that the “educational benefit” category doesn’t cover ordinary private student loans at all — it read that phrase to mean conditional grants like ROTC tuition payments, not loans with an unconditional obligation to repay. That still leaves the third category, “qualified education loan,” which the lender in that case never even argued applied — likely because the loan there was paid directly into the borrower’s bank account and exceeded his school’s cost of attendance, facts that can knock a loan out of that third category too. In other words: a private loan that was disbursed straight to you rather than certified by the school, or that exceeded your cost of attendance, has a real argument for falling outside all three protected categories and being dischargeable in an ordinary Chapter 7 case without the tougher “undue hardship” showing — but this isn’t settled the same way in every part of the country, and it takes a bankruptcy attorney to evaluate your specific loan and your circuit — I walked through this same fight in more detail in what SoFi itself told the SEC about discharging private student loans, and in the broader myth that student loans can never be discharged in bankruptcy. Second, every state has its own unfair-and-deceptive-practices law, which can give you or your state attorney general an independent way to challenge a loan that was induced by fraud — separate from anything federal.
Homaidan v. Sallie Mae, Inc., No. 20-1981 (2d Cir. July 15, 2021) & 11 U.S.C. § 523(a)(8) & 26 U.S.C. § 221(d)(1)
Why You Were Told This
Nobody sat down and invented this myth to hurt anyone — it’s just what happens when a federal program with a famous name (Borrower Defense) drowns out a quieter, older, contract-based right almost nobody advertises. The Department of Education runs press conferences about mass federal discharges. No private lender runs a press conference announcing that its own promissory note lets you fight back. And per the CFPB’s own findings, some servicers went further than silence — they affirmatively told borrowers no such option existed, in writing, while sitting on a contract that said otherwise. I don’t think every servicer employee doing that understood they were violating federal law. I do think the company they worked for benefited every single month a borrower kept paying instead of asking the right question.
What to Actually Do
- Keep paying unless a lawyer tells you otherwise. This is the most important sentence on the page. The Holder Rule gives you a defense — something you raise when you are sued, or in negotiation. It does not pause your loan, and nothing here entitles you to stop paying while you work it out. Stopping on your own invites default, acceleration, late fees and credit damage, and it can weaken the position you are trying to argue from. Build the case first; keep the account current while you do.
- Pull your actual promissory note, not a summary of it. Look for language stating that any holder of the contract is subject to claims and defenses the borrower could assert against the seller (your school). That’s the Holder Rule notice. If your loan was originated through the school — an in-house tuition plan, a “preferred lender” the school steered you to — the odds it’s there go up.
- Check whether the U.S. Department of Education or a court already found your school committed fraud, misconduct, or misrepresentation. In its supervision of the private lenders and servicers it examined, the CFPB directed those firms — where they had actual notice of that kind of finding — to suspend collections until they gave the borrower a detailed, individualized reason their private loan isn’t covered by the same misconduct, rather than a form denial. Be clear-eyed about what that is: a supervisory finding binding on the firms the Bureau examined, not a universal right you can demand from any lender. It tells you what good practice looks like and it is worth citing, but it is not a statute you can sue under. Point your servicer to that finding directly.
- Submit a written claim to your servicer citing the school misconduct, and keep everything in writing. The CFPB found servicers took borrowers seriously mainly when an attorney was involved — a free or low-cost consultation with a consumer attorney before you file your claim can change the outcome.
- File a complaint with the CFPB at consumerfinance.gov/complaint if your servicer denies the claim without explanation or tells you no such program exists — that denial itself matches the exact practice the CFPB documented among the private student loan servicers it examined.
- Ask a bankruptcy attorney whether your specific private loan even qualifies as protected student debt. If it was disbursed straight to you rather than certified and sent to the school, or exceeded your cost of attendance, it may not be a “qualified education loan” at all — a completely separate question from school fraud. A consumer bankruptcy attorney through the National Association of Consumer Bankruptcy Attorneys can evaluate this.
- If bankruptcy isn’t on the table, a non-bankruptcy consumer attorney can help you fight the debt directly. The National Association of Consumer Advocates maintains a directory of attorneys who handle exactly this kind of claim.
- Don’t pay a company that promises to “get your private loans discharged for a fee.” Nothing above requires paying anyone upfront — filing a claim with your servicer, the CFPB, or a legitimate attorney referral costs nothing to start. It’s the exact same red flag I wrote about when companies charge a fee to “get your federal student loans forgiven faster” — the private-loan version of that pitch is just as unnecessary.
Steve’s Take
I’ve seen this exact confusion play out with people who did everything right — they researched their federal options, applied for Borrower Defense, got their government loans wiped out, and then just quietly kept paying the private loan for the same worthless degree because someone told them “that one doesn’t qualify.” It genuinely might not. But before you accept that, pull your note and read the fine print yourself, because the company collecting that private loan has zero incentive to tell you it might not be collectible. Debt is math wrapped in emotion, and this is a case where the math is sitting in a document you already signed — you just have to go find the clause.
Frequently Asked Questions
Can private student loans be discharged for school fraud?
Sometimes, yes. The federal Borrower Defense to Repayment program only covers federal loans, and there is no private equivalent of it. But some private student loan contracts — most often those arranged through your school or a lender it recommended — contain a clause — which the CFPB says may be required by the FTC’s Holder Rule (16 CFR § 433.2) — that lets a borrower raise their school’s fraud or misconduct as a defense against whoever holds the loan. It depends on whether that clause is in your specific note.
What is the FTC Holder Rule?
It’s a 1975 Federal Trade Commission regulation (16 CFR Part 433) that makes it an illegal practice for a school affiliated with a lender — one it refers borrowers to, or has a business arrangement with — to accept loan proceeds unless the loan contract includes a notice stating the loan holder is subject to any claim or defense you could raise against the seller (your school). Fraud by the school is exactly the kind of claim that notice preserves.
Does this apply to every private student loan?
No. It generally applies where the lender has a referral or business relationship with the school — common with in-house or “preferred lender” loans at for-profit colleges. A private loan from an unrelated bank you found on your own may not carry the same clause. Check your actual promissory note.
What did the CFPB find about private student loan servicers?
In a December 2024 report, the CFPB found servicers misled borrowers by telling them no discharge option existed, and failed to properly consider most borrowers’ school-misconduct claims — even though provisions in the borrowers’ own loan contracts guaranteed that right. The CFPB directed servicers to fix their claims-review processes.
Can I discharge a private student loan in bankruptcy instead?
Possibly, through a different legal route than school-fraud claims. Not every private loan meets the legal definition of a protected “qualified education loan.” In Homaidan v. Sallie Mae, the Second Circuit found certain private loans aren’t automatically shielded from ordinary bankruptcy discharge. This varies by circuit and by loan — a bankruptcy attorney needs to review your specific note.
What should I do if my servicer tells me there’s no discharge program for my private loan?
Ask them, in writing, to point to the specific reason your loan’s Holder Rule clause (if your note has one) doesn’t apply to your school misconduct claim. If they can’t or won’t, file a complaint with the CFPB and consider a free consultation with a consumer attorney.
Does it matter if my school already lost a Borrower Defense case or a lawsuit?
Yes — it strengthens your position. If the Department of Education or a court already found your school committed fraud, misconduct, or misrepresentation, that finding is powerful evidence to put in front of your lender. Be precise about what it is, though: in its supervision of the private lenders and servicers it examined, the CFPB directed those firms — where they had actual notice of such a finding — to pause collections until they explained in detail why your loan isn’t covered by the same misconduct. That is a supervisory expectation binding on the firms the Bureau examined, not a universal right you can demand from any lender. Cite it, but don’t assume it compels every servicer.
This is one informed perspective based on what I’ve seen in over 30 years of doing this work — not a substitute for reviewing your own loan documents with a qualified attorney. Only you and your attorney can decide what applies to your specific situation. Take this as input, not instruction.
The bottom line: Federal Borrower Defense really is federal-only, and nothing replaces it on the private side — but some private student loan contracts, most often the ones arranged through your school, carry their own fraud defense, and the CFPB caught the industry hiding it. If you believed your private loan was simply unfixable because of what your school did, pull your note and check before you accept that. If someone you know is still paying a private loan for a school that defrauded them, send them this.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



