

Written by Steve Rhode, consumer debt expert since 1994 • Last updated August 6, 2026
Quick Answer: A nursing home bill after your parent’s death is almost always a claim against your parent’s estate — not a debt you personally owe. Federal law (42 U.S.C. §1395i-3(c)(5)(A)(ii) and its Medicaid twin, 42 U.S.C. §1396r(c)(5)(A)(ii)) bars a Medicare- or Medicaid-participating facility from requiring anyone but the resident to personally guarantee payment as a condition of admission. Before you pay a dollar from your own account, get the actual signed admission agreement and find out whether you signed as your parent’s agent or as a personal guarantor — those are legally different things, and regulators have found that some admission agreements use language that has the effect of making families believe they took on more than they actually agreed to. Don’t ignore the mail either — some situations (filial responsibility states, a genuine personal guarantee) really can reach you.
State Law Varies — Read This Before You Relax: The federal protection above is real, but it isn’t absolute. It does not override a personal guarantee you knowingly and voluntarily signed as a separate document, and it does not erase a state filial-responsibility law that lets a facility pursue an adult child directly. One state in particular, Pennsylvania, has actually enforced its filial responsibility law against an adult child over a large nursing home bill — see below. Know which category you’re in before you assume none of this applies to you.
What Just Happened to You
Somewhere in the pile of admission paperwork you signed when your parent moved into the facility — often while you were exhausted, scared, and being handed a clipboard in a hallway — was a section labeled something like “Responsible Party,” “Designated Representative,” or “Financial Agent.” You signed it because you had to sign something to get your parent admitted that day. Now the facility (or a collection agency working for it) is sending a bill with your name on it, sometimes implying you agreed to personally cover whatever Medicare, Medicaid, or your parent’s own money didn’t.
Here’s the mechanism: federal law says a facility cannot require a third party to personally guarantee payment as a condition of letting your parent in the door. But the same law lets a facility ask someone with legal access to the resident’s own money — a power of attorney, an executor, a rep payee — to sign an agreement to pay the facility from the resident’s funds, without that person taking on personal liability. Those two roles look almost identical on the signature line. CMS’s own revised surveyor guidance (QSO-25-14-NH, revised March 10, 2025) adds specific examples of noncompliant admission-agreement language for exactly this reason — regulators have found that “responsible party” language, even without the word “guarantee” anywhere in it, has the effect of making family members believe they agreed to pay personally when they only signed as their parent’s agent.
If You Held Power of Attorney for Your Parent — Stop: A financial power of attorney ends automatically the moment the person who granted it dies. Yours ended when your parent died. Using it now to pay this bill, move money, or close an account is not authorized — even if the bank or facility still has it on file — and it can create personal liability for you. Only a court-appointed executor or personal representative (or, where your state allows one, a small-estate process) can lawfully pay debts out of your parent’s estate now. If you don’t yet know who that is, or whether anyone has been appointed, ask the probate clerk in the county where your parent lived.
The Mistake You’re About to Make: You pay the bill out of your own checking account because it has your name on it, or because someone at the billing office told you that you’re “the responsible party.” Don’t. That phrase gets used loosely and often incorrectly. Before you pay anything personally, find out exactly what you signed — agent for the resident’s funds, or personal guarantor. The two words that matter are on that document, not on the invoice.
Your Options Right Now
What to Do in the Next 48 Hours
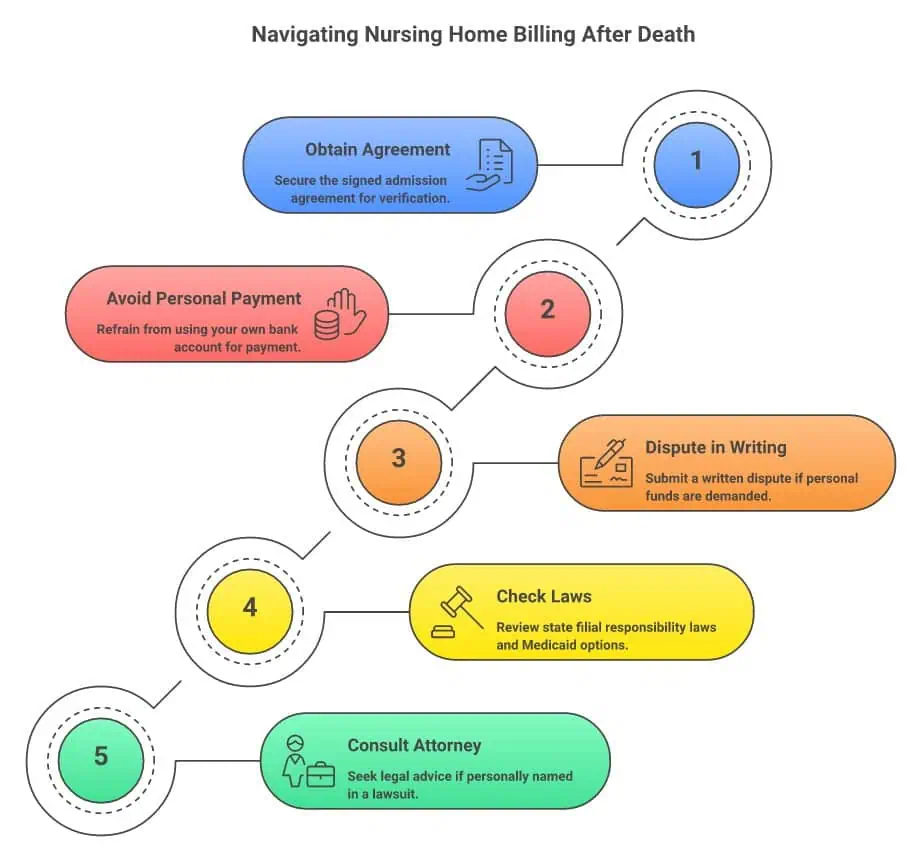
- Get the actual signed admission agreement, not just the invoice. Call or email the facility’s business office and request a copy of everything you signed at intake, specifically the section addressing “responsible party,” “designated representative,” or “financial agreement.” You cannot know what you owe until you know what you signed.
- Do not pay from your own bank account yet. A legitimate balance is a claim against your parent’s estate — paid from whatever money and property your parent left behind — unless you personally guaranteed the debt in writing or a state law creates a separate obligation (see below).
- Put your response in writing if the bill demands your personal money. If you signed only as your parent’s agent and the facility (or its collector) is treating that as a personal guarantee, send a written dispute citing the federal ban on third-party guarantees — 42 U.S.C. §1395i-3(c)(5)(A)(ii) and 42 CFR §483.15(a)(3). Keep a copy and send it certified mail, return receipt requested.
- Check whether your state has a filial responsibility law — and whether Medicaid, not the facility, actually holds the claim. Roughly 29 states have old filial responsibility statutes that could reach you separately from the admission agreement; see the complete state-by-state guide for whether yours is one of them and how rarely they’re actually enforced. If your parent was on Medicaid, the government’s own repayment tool is Medicaid Estate Recovery (MERP). It recovers from your parent’s estate, not from you personally as a debt — but many states define “estate” broadly enough to include assets that pass outside probate, including a bank account you held jointly with your parent, so don’t assume a joint account is automatically off-limits. Check your own state’s rules.
- If you might end up as your parent’s executor, don’t distribute anything until you check the creditor-claim deadline. See the probate section below before you write checks to heirs.
- If a collector gets involved or a lawsuit is filed with your name on it, talk to an attorney before you say anything else. NACBA can connect you with a bankruptcy attorney if debt is piling up on top of this, and NACA can connect you with a consumer attorney for the collection or lawsuit itself. Damon Day is an independent debt coach, and my co-host on the Get Out of Debt Guy Podcast — you can hear him there. I want you to know that before you decide whether to call him for his free consultation. I receive no payment for this referral.
How to Actually Stop It — Your 4 Paths
- Confirm you signed as agent, not guarantor — and say so in writing. If the paperwork shows you signed to authorize payment from your parent’s own funds, not to personally guarantee the balance, that gives you a strong defense against these demands. Federal law bars a facility from requiring a personal guarantee as a condition of admission, and that’s a powerful argument — but it’s a defense someone has to raise, not an automatic shield that voids a guarantee by itself. If you genuinely, knowingly signed a separate personal guarantee as a voluntary document, that can still be argued to hold. And if you are ever served with court papers over this, respond by the deadline no matter how weak you think their claim is — a default judgment entered because you ignored a lawsuit is far harder to undo than a weak claim is to defeat.
- Direct the claim to the estate through probate, even an informal one. If your parent left any money or property, the facility’s bill gets paid (or doesn’t) through the normal estate-claims process, in line with whatever other debts and the available assets allow — not by you writing a personal check to make it go away.
- If you’re in a filial responsibility state, understand the real odds before you panic — except in Pennsylvania. Enforcement against adult children is rare almost everywhere these laws are on the books, and usually reserved for cases where a facility went unpaid for months with no estate or Medicaid application in progress. Pennsylvania is the documented exception: its courts have actually enforced the law against an adult child, holding a son liable for roughly $93,000 of his mother’s nursing home bill (Health Care & Retirement Corp. of America v. Pittas, 46 A.3d 719 (Pa. Super. Ct. 2012)). See the full state guide for what actually triggers these claims and how to head them off.
- What won’t work: ignoring every letter and hoping it disappears. If you did sign a genuine personal guarantee, or your state’s filial law truly applies and the facility follows through, silence can turn into a default judgment. Read what you signed, respond in writing, and get help — don’t just stop opening the mail.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
What You Need to Know About Who Actually Owes This
A Medicare- or Medicaid-participating facility cannot require anyone but the resident to personally guarantee payment as a condition of admission or continued stay.
Have an old filial responsibility law that could create a separate obligation — enforcement against adult children is rare almost everywhere except Pennsylvania, which has actually enforced it. See if yours is one.
The date CMS surveyors began applying revised guidance (QSO-25-14-NH, the March 10, 2025 revision of guidance first issued that January as QSO-25-12-NH) that flags admission-agreement language demanding a personal guarantee as noncompliant — not a deadline CMS gave facilities to rewrite their contracts.
Medicaid’s Estate Recovery Program (MERP) targets your parent’s Medicaid estate, not a debt you personally owe — but many states define “estate” broadly enough to reach jointly held accounts and other non-probate assets, so a joint account with your parent is not automatically safe.
The federal Nursing Home Reform Act applies to any facility that accepts Medicare or Medicaid — the overwhelming majority of nursing homes in the country. It draws a hard line: the facility can require someone with legal access to the resident’s income or resources (a power of attorney, a rep payee, an executor) to sign an agreement to pay from those resources, but it cannot make that person personally, financially liable as a condition of getting the resident admitted. In January 2025, the Centers for Medicare & Medicaid Services went further, issuing revised surveyor guidance — originally QSO-25-12-NH, revised as QSO-25-14-NH on March 10, 2025 — that specifically flags admission-agreement language holding a “responsible party” liable for things like an incomplete Medicaid application or a missed payment, even without the word “guarantee” anywhere in the contract, as noncompliant, and adds examples of exactly what counts. Surveyors began using that guidance to check facilities for compliance on April 28, 2025 — that’s the date inspectors started applying the standard, not a deadline CMS handed facilities to fix their paperwork. Read the memo yourself: QSO-25-14-NH (PDF). The CFPB and CMS first flagged this exact billing practice back in 2022 — see my earlier post, Nursing Home Debt: When You’re Liable and When Not, for that original joint action.
| Scenario | Are You Personally Liable? | Who Can Actually Be Pursued |
|---|---|---|
| Federal baseline — you signed as agent/representative | No | Your parent’s estate only |
| You knowingly signed a separate, explicit personal guarantee | Possibly — get it reviewed by an attorney | You, up to the terms you actually signed |
| Filial responsibility state, facility pursues you directly | Possibly — rare outside Pennsylvania | You, under state law — see the state guide |
| Parent was a Medicaid recipient, balance covered by Medicaid | Not as a personal debt — but check joint accounts | The estate, via Medicaid Estate Recovery (MERP), which in many states can also reach non-probate assets like jointly held accounts |
If you’re a Medicaid family, keep the facility’s private bill separate in your mind from Medicaid Estate Recovery. They’re different creditors with different rules: the facility’s own bill is a private debt claim against the estate (or, unlawfully, sometimes pushed onto you); MERP is the state Medicaid agency’s own repayment process. Federal law (42 U.S.C. §1396p(b)(4)) lets states define “estate” more broadly than just the probate estate, and many states use that authority to reach assets that pass outside probate — including a bank account you held jointly with your parent — not just what goes through the probate court. Required hardship waivers and protections still apply when a spouse, minor, or disabled child survives. Check your own state’s Medicaid estate recovery definition before assuming a joint account is safe. See Medicaid.gov’s official Estate Recovery page for the federal rules your state must follow.
If you are, or might become, your parent’s executor or personal representative, two probate rules matter more than “just let the estate handle it.” First, if you distribute what’s left of the estate to heirs before resolving valid creditor claims — including a legitimate nursing home bill — you can become personally liable to that unpaid creditor, up to the value of what you distributed too soon. Second, every state has a creditor-claim deadline (a “nonclaim statute”) — often just a few months after notice to creditors is published or after you’re appointed — after which a creditor’s claim against the estate can be barred for good. These rules vary by state. Call the probate clerk in the county where your parent lived and ask two questions: what is the creditor-claim deadline, and has notice to creditors been published yet? Don’t distribute anything to heirs until you know the answer.
If a debt collector — not the facility itself — is now calling you, file a complaint with the CFPB and your state attorney general. The CFPB has specifically warned that collectors who represent an invalid nursing home debt as something you personally must pay can violate the Fair Debt Collection Practices Act. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, and I remember exactly what it feels like to get a bill that makes your stomach drop before you’ve even opened the envelope. Losing a parent is hard enough without a stranger in a billing office implying you’re personally on the hook for their final months of care. You’re not a bad son or daughter for asking “wait, do I actually owe this?” That’s not dodging responsibility — that’s doing the math instead of reacting to the shame. In thirty years of this work, the families who did better were the ones who read the paperwork first and reacted second.
Frequently Asked Questions
My parent died in a nursing home and I got a bill with my name on it — do I have to pay it?
Not automatically. Federal law prohibits a Medicare- or Medicaid-participating facility from requiring you to personally guarantee your parent’s bill as a condition of admission (42 U.S.C. §1395i-3(c)(5)(A)(ii)). Unless you signed a separate, explicit personal guarantee, or a state filial responsibility law applies to your situation, the bill belongs to your parent’s estate — not to you personally.
I signed the admission agreement as my parent’s “responsible party” — does that make me personally liable?
Not necessarily. “Responsible party” language is exactly what CMS’s revised surveyor guidance targets — QSO-25-14-NH, the March 10, 2025 revision of QSO-25-12-NH (originally issued January 16, 2025), which adds specific examples of noncompliant admission-agreement language, with surveyors applying it on inspections starting April 28, 2025. Facilities can require someone with legal access to the resident’s funds to sign an agreement to pay from those funds, but cannot make that person personally liable as a condition of admission. Get the actual signed document and see whether it names you as an agent for your parent’s resources or as a personal guarantor; those are different legal roles even when the label on the form is the same.
The facility says Medicaid didn’t cover everything — am I on the hook for the balance?
Usually not as a personal debt. An unpaid Medicaid balance is a claim against your parent’s estate, or it may fall under Medicaid Estate Recovery (MERP). MERP isn’t a personal debt collector coming after you — but many states define “estate” broadly enough to reach assets that pass outside probate, including money in an account you held jointly with your parent, so a joint account isn’t automatically protected. Check your state’s Medicaid estate recovery rules, and see Medicaid.gov’s Estate Recovery page for the federal baseline.
What if there’s no money left in my parent’s estate?
Then, in most cases, the debt goes unpaid — the same way any creditor’s claim against an insolvent estate goes unpaid. You are not required to use your own money to cover a shortfall in your parent’s estate unless you personally guaranteed the debt or a filial responsibility law creates a separate obligation in your state.
I live in a state with a filial responsibility law — should I panic?
No, but you should pay attention — especially if you live in Pennsylvania. Roughly 29 states have these laws on the books, dating back centuries in some cases, and enforcement against adult children remains rare almost everywhere. Pennsylvania is the documented exception: a Pennsylvania court held an adult son liable for roughly $93,000 of his mother’s nursing home bill under the state’s filial responsibility law (Health Care & Retirement Corp. of America v. Pittas, 46 A.3d 719 (Pa. Super. Ct. 2012)). See the complete state-by-state guide for whether your state is one of them and what actually triggers a claim.
A collector, not the nursing home, is calling me about this now — what are my rights?
You have the same protections as with any debt collector, plus the CFPB has specifically flagged nursing home collections as an area of concern — a collector representing an invalid third-party debt as something you must personally pay can violate the FDCPA. If a collector is contacting you about a deceased relative’s debt generally, see my crisis guide on collectors calling about a dead relative’s debt for exactly what to say.
Can the nursing home refuse to release my parent’s body or belongings until I pay?
Facilities sometimes imply this, but it isn’t how the law works, and a legitimate hospice, nursing facility, or funeral home should never condition release of remains or personal belongings on payment of an unrelated billing dispute. If a facility does this, that’s worth raising directly with your state attorney general and, if you believe the debt itself is invalid, the CFPB.
Should I just pay it to make this go away?
Only after you’ve confirmed what you actually signed. Paying quickly out of guilt or exhaustion is understandable, but it can mean covering a debt that was never legally yours in the first place. Get the signed agreement, figure out agent versus guarantor, and check the estate and filial-responsibility angles before any money leaves your own account.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or my podcast co-host Damon Day offers a free consultation about your situation — I receive no payment for that referral.
Key Takeaway: A nursing home bill after your parent’s death almost always belongs to their estate, not to you personally — federal law bars facilities from requiring a family member to personally guarantee payment as a condition of admission. Get the actual signed agreement, confirm whether you signed as agent or guarantor, and check your state’s filial responsibility status before you pay anything from your own pocket. Talk to an attorney this week if a collector or lawsuit names you personally.
The Bottom Line
You didn’t do anything wrong by signing paperwork to get your parent admitted to care. The confusion between “agent for my parent’s money” and “personal guarantor” is baked into how a lot of admission agreements are written, and federal regulators have been cracking down on exactly that confusion. The families who come out of this best are the ones who get the actual signed document, read it carefully, and respond in writing instead of paying out of guilt or panic. If someone you know just lost a parent and is getting billing letters that feel threatening, send them this page — it may save them money they never legally owed. For the deeper dive on state filial responsibility laws, see the complete state-by-state guide, and for the broader picture of what you do and don’t owe after a family member’s death, see Debt After Death: The Complete Family Guide. The Find Your Path quiz can help if this crisis is piling on top of debt that was already a problem before your parent passed.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



