

A Get Out of Debt series · Reading the filings so you don’t have to
What They Told Wall Street
FORM 10-QSYNCHRONY FINANCIAL (SYF)FILED 07/23/2026Q2 ENDING 06/30/2026CIK 0001601712
Two days before this filing, Synchrony’s earnings release told investors that the CFPB’s $8 credit card late fee cap was vacated by a court in April 2025 — I wrote about that here. What the earnings release didn’t have room for is the number: what actually happened to late fees this quarter. The full 10-Q, filed two days later, has it.
When a court struck down the $8 late fee cap in April 2025, the obvious fear was that fees would climb back toward the old $30–$41 range card issuers charged before the rule. I said as much in my last piece on this filing. So I went back to Synchrony’s full quarterly report — the 10-Q, not the earnings press release — to see what its own numbers say happened. They don’t say what I expected.
The fear, since April 2025
With the $8 cap gone, credit card late fees would climb back toward the pre-rule $30–$41 range and cardholders would pay more.
What Synchrony’s 10-Q shows
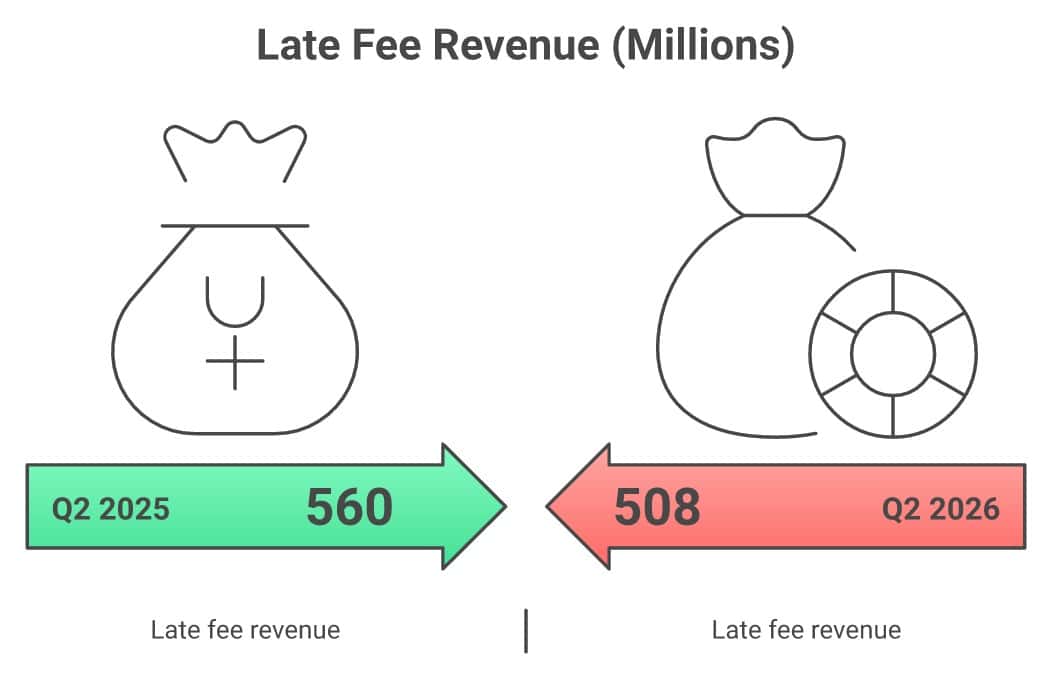
Late fee revenue fell to $508 million this quarter, down from $560 million a year earlier — and the company says lower “late fee incidence” helped pull its loan yield down, not up.
I’m not walking back what I wrote two days ago about the $8 cap being gone — that’s still true, and it still matters, because the legal protection is gone whether or not a company happens to be assessing fewer fees this particular quarter. But I promised in that piece to keep reading these filings so you don’t have to, and the fuller 10-Q landed with a number the earnings release skipped: late fee dollars actually collected went down. Here’s what the filing says, and what I think it does and doesn’t mean for you.
The warning I already covered
“…product, pricing and policy changes related to the Consumer Financial Protection Bureau’s (the “CFPB”) final rule on credit card late fees, which was vacated in April 2025; the sufficiency of our allowance for credit losses and the accuracy of the assumptions or estimates used in preparing our financial statements…”
What I think they’re really saying
This is the same boilerplate line Synchrony ran in its earnings release two days earlier, word for word — I already decoded it: the fee protection Congress and the CFPB tried to build was struck down in court, and Synchrony is telling investors that whatever it charges you now is a business decision, not a regulated ceiling. If you skipped that piece, read it here before you go further — it covers what late fees can legally run today. What’s below is new: the actual numbers from the same quarter.
What the earnings release didn’t show you
An 8-K earnings release is a highlight reel. A 10-Q is the full report, with the platform-by-platform math behind the highlights. Buried in that math is a line the press release never printed.
“The loan receivables yield decreased 11 basis points to 21.43% for the three months ended June 30, 2026 primarily driven by lower benchmark rates and lower assessed late fees, partially offset by the impacts of our product, pricing and policy changes.”
What I think they’re really saying
Whatever the yield gained from “product, pricing and policy changes” — a phrase that can include raising a fee schedule — it was more than offset by two things the filing names: lower benchmark interest rates and fewer late fees actually being assessed. That’s Synchrony’s own explanation for why its yield went down, not up, this quarter, and I don’t want to credit the late-fee half alone when the filing names both.
“Interest income on loan receivables includes fees on loans, which primarily consist of late fees on our credit products, of $508 million and $560 million for the three months ended June 30, 2026 and 2025, respectively, and $1.1 billion for both of the six months ended June 30, 2026 and 2025.”
What I think they’re really saying
This is company-wide, not one platform: the dollars Synchrony collected in late fees (plus other loan fees) fell $52 million, or about 9%, in the April–June quarter compared with the same quarter last year — more than a year after the $8 cap was already gone. If the vacated rule were pushing fees higher, this line should be climbing. In my reading of the filing, it isn’t — though one quarter cannot establish that by itself.
One caveat I owe you, because the same footnote has it: for the full six months of 2026, late fees were about $1.1 billion in both years — flat, not down. And over that longer six-month window, Synchrony says its loan yield actually rose 18 basis points, driven mainly by “product, pricing and policy changes,” with lower late fees only a partial offset. The decline I’m describing here is a second-quarter result, not a six-month trend, and I’m not going to inflate three months of numbers into more than they are.
Two platforms say the same thing
Synchrony doesn’t organize itself into separate financial-reporting segments — it discloses it operates as a single reporting unit. But it does break out supplemental results by “sales platform,” and it has five: Home & Auto (Lowe’s, Ashley HomeStores, and similar), Digital (Amazon, PayPal, Venmo, and similar), Diversified & Value (Sam’s Club, JCPenney, TJX, and similar), Health & Wellness (CareCredit), and Lifestyle. Two of those five spell out the same driver by name.
“The increase in loan receivables yield reflects the impact of product, pricing and policy changes, partially offset by lower late fee incidence.”
“…decreases in loan receivables yield primarily reflecting lower benchmark rates and lower late fee incidence.”
What I think they’re really saying
“Incidence” means how often a fee gets charged, not how big it is. Synchrony isn’t telling investors it lowered its late fee amount — it’s telling them fewer of its cardholders got hit with one this quarter, in two of its five sales platforms (Home & Auto and Diversified & Value — not the Digital platform that carries Amazon and Venmo, which isn’t mentioned either way on late fees). That’s a different statement than “fees are cheaper now,” and I don’t want to blur the two.
The number that probably explains it
“Over-30 day loan delinquencies as a percentage of period-end loan receivables decreased 2 basis points to 4.16% at June 30, 2026 from 4.18% at June 30, 2025. The net charge-off rate decreased 27 basis points and 61 basis points for the three and six months ended June 30, 2026, respectively, to 5.43% for both periods… Our allowance coverage ratio (allowance for credit losses as a percentage of period-end loan receivables) decreased to 10.09% at June 30, 2026, as compared to 10.59% at June 30, 2025.”
What I think they’re really saying
A late fee only gets charged when a payment is late. If fewer accounts are 30-plus days delinquent and fewer dollars are being charged off, there are simply fewer opportunities to assess a late fee in the first place — regardless of what the fee amount is set at. My read: this looks less like a company choosing to charge smaller fees and more like a cardholder base that, this quarter, is paying on time slightly more often than it was a year ago. I can’t prove intent either way from a filing; I can only tell you what the numbers line up with.
Why two SEC filings, two days apart, about the same quarter
In plain English
An 8-K is a short “here’s what happened” notice — companies often furnish one within a day or two of announcing earnings, usually with an investor presentation attached, hitting the headline numbers. A 10-Q is the full, legally required quarterly report, filed a few days later, with the platform-level detail, footnotes, and management discussion the 8-K skips. Reporters and AI summaries mostly work from the 8-K because it’s faster to read. The 10-Q is where the real story about who’s paying what usually lives.
Late fee incidence vs. late fee amount
In plain English
Incidence is how often a fee gets charged — the share of accounts that trigger one in a given period. Amount is how much each fee costs when it hits. Synchrony’s filing discusses incidence going down. It says nothing in this filing about lowering the dollar amount of any individual late fee. With the $8 federal cap gone, the fee amount reverts to the pre-2024-rule framework: a safe-harbor range of roughly $30 to $41 (adjusted annually for inflation) that an issuer can charge without extra justification — and that’s a floor of protection, not a ceiling. A “safe harbor” only means the issuer doesn’t have to separately justify a fee within that range; nothing in the regulation stops an issuer from charging more if it can show the higher amount is tied to its actual collection costs. Don’t read “incidence fell” as “the fee got cheaper” — those are two different facts, and only one of them is in this filing.
What this does not mean
The claim this filing might tempt you to make: “Synchrony backed off late fees because of the bad press over the CFPB rule being vacated.”
The reality: Nothing in this 10-Q says that. The filing attributes the yield decline to “lower benchmark rates and lower assessed late fees” and, separately, credits “product, pricing and policy changes” with pushing yield up elsewhere in the same document — including over the full six months, where late fees were flat and pricing changes did most of the work. Companies don’t publicly narrate a decision to charge customers less out of goodwill in a securities filing — they report what happened and let analysts draw conclusions. One good quarter for cardholders, company-wide, also isn’t a promise about next quarter, and it says nothing about what happens to any individual reader’s account. It’s also worth knowing the CFPB itself signaled in July 2026 that it may revisit late-fee rulemaking, so this isn’t a closed subject on the regulatory side either.
What this means for you
Don’t let a company-wide quarterly trend substitute for looking at your own statement. The $8 fee protection is still gone, whatever this quarter’s aggregate number says, and Synchrony — along with every other major issuer — is legally free to charge up to the old safe-harbor range if it chooses to. If you carry a Synchrony-branded card (Lowe’s, Amazon, CareCredit, Venmo, Dick’s Sporting Goods, and hundreds of others), the number that matters is the one printed on your own statement, not the company average.
What I’d do — Pull your most recent statement or your Schumer Box (“Summary of Credit Card Terms”) and write down your actual late fee, your APR, and your minimum payment. If you’re carrying a balance, run the minimum-payment payoff math most statements disclose — it’s usually the number that changes how people think about the debt. If falling behind is already a real risk, here’s what I’d do if you can’t make minimum payments anymore, and if an account has already gone to collections, don’t assume a charge-off means the debt disappeared — it doesn’t.
Steve’s bottom line
The $8 late fee cap being vacated is still real, and it’s still worth knowing. But the fear that followed — that fees would spike now that the legal ceiling is gone — isn’t what Synchrony’s own numbers show happened this quarter. Late fee dollars went down. Fewer accounts got hit with one. That’s genuinely good news, and I’m not going to bury it just because it complicates a scarier headline.
What it doesn’t do is protect you going forward. A quarter of company-wide numbers moving your way is not a guarantee, and it’s not a substitute for knowing your own account’s actual terms. Read the filing. Then read your statement — that’s the one that’s actually about you.
Frequently asked questions
Did Synchrony raise its late fees after the CFPB’s $8 cap was struck down?
Its 10-Q for the quarter ended June 30, 2026 doesn’t say it raised per-fee amounts. It says the opposite happened to its aggregate late fee revenue: fees fell from $560 million to $508 million compared with the same quarter a year earlier, and it attributes part of its yield decline to “lower assessed late fees” and “lower late fee incidence.” But read the longer window before you call it a trend: over the full six months the same filing puts late fees at about $1.1 billion in both 2026 and 2025 — flat, not down — and says the six-month loan receivables yield rose 18 basis points, driven mainly by “product, pricing and policy changes.” One quarter is not a direction. The filing does not disclose what any specific late fee amount is.
Is the CFPB’s $8 credit card late fee cap still vacated?
Yes. Synchrony’s 10-Q, filed July 23, 2026, repeats the same language from its earlier earnings release: the CFPB’s final rule capping credit card late fees at $8 “was vacated in April 2025.” That has not changed as of this filing.
What does “late fee incidence” mean?
It refers to how often a fee gets charged — the share of accounts triggering a late fee in a given period — not the dollar amount of any individual fee. Synchrony’s filing discusses incidence falling in two of its five sales platforms (Home & Auto and Diversified & Value); it says nothing about lowering the size of any specific fee.
Why did Synchrony file both an 8-K and a 10-Q about the same quarter?
The 8-K, furnished July 21, 2026, was the earnings-release notice with headline financial results. The 10-Q, filed two days later, is the full legally required quarterly report, with the platform-level detail and management discussion the earnings release didn’t include — including the late fee figures this piece is built on.
Does a lower late-fee quarter mean cardholders are safe from higher fees?
No. The $8 federal cap that would have limited late fees is still gone, and nothing in this filing changes that. A company-wide quarterly trend also isn’t a promise about future quarters or about any individual account. Check your own card’s Schumer Box or most recent statement for the actual late fee that applies to you.
Read it yourself — the primary source
Synchrony Financial — Form 10-Q, quarter ended June 30, 2026 (SEC.gov) →
Filed with the SEC on July 23, 2026. The late-fee figures are in Item 2, Management’s Discussion and Analysis; the credit-quality figures are in the Loan Quality section of the same Item. To find any company’s filings yourself, search the company name at sec.gov/edgar/search.
How to read this
Two different things appear above, kept separate on purpose. Every quote in a gray box is fact — Synchrony’s own words, from its own SEC filing, public record filed under penalty of law, quoted verbatim and linked. The plain-English explanations are my interpretation, offered to help you read a dense filing — not Synchrony’s position, and not a statement about what any individual cardholder will be charged.
Nothing here says Synchrony did anything wrong. A quarter of lower aggregate late fee revenue is not a policy announcement, a promise, or an admission — it’s one data point from one 10-Q, and I’m reading it the same way I’d read anyone else’s. This is general information and my opinion after more than 30 years helping people with debt, not financial or legal advice. Your own card’s terms control what you’re actually charged; when in doubt, call the number on the back of your card or read your cardholder agreement.
Know someone who assumed their card’s late fees only go one direction? Please forward this to them — the full numbers are more complicated, and more useful, than either headline alone.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
“What They Told Wall Street” reads the SEC filings of the companies that handle your money and translates what they admitted — one filing at a time. Sourced entirely from public SEC records. · See the whole series →



