

Written by Steve Rhode, consumer debt expert since 1994 • Last updated August 7, 2026
Quick Answer: A debt collector is demanding money on a debt you already paid off. That’s not just annoying — federal law bars a collector from misrepresenting what you owe (15 U.S.C. § 1692e), and if your paid account was sold or handed to a new collector, a second rule may apply to whoever passed it along (Regulation F, 12 CFR § 1006.30(b)(1) bars a debt collector from selling, transferring for consideration, or placing for collection a debt it knows or should know was already paid, settled, or discharged in bankruptcy). Either way the first move is the same: gather your proof of payment and dispute it in writing within 30 days of receiving the collector’s validation notice — the letter that tells you you have 30 days to dispute — under 15 U.S.C. § 1692g — that is the window that forces them to stop and verify — and don’t pay again just to make the calls stop. Don’t ignore it either — it can escalate to a lawsuit or a fresh mark on your credit report.
What Just Happened to Your Paid-Off Debt
You paid the debt. Maybe you have the cancelled check, the bank statement, or a “paid in full” letter to prove it. And now a collector — sometimes a totally different company than the one you paid — is calling, texting, or mailing you demanding money on the exact same account. This happens more than you’d think. Of the roughly 207,800 debt collection complaints the CFPB received in 2024, “attempts to collect debt not owed” was the most common issue — and among the people who said the debt wasn’t owed, 10% said the reason was that the debt was already paid (CFPB FDCPA Annual Report 2025).
How does this happen if you truly paid? A few common ways: the original creditor’s records never got updated after your payment posted. The account was already sold to a debt buyer before your payment cleared, and nobody told the new owner. Or an old account you already settled got sold again to a different collector years later, long after you’d forgotten about it — this is sometimes called zombie debt. None of these are your fault, and none of them make you liable for money you already paid.
The Mistake You’re About to Make: Telling the collector “I already paid this” over the phone and assuming that settles it. A phone call doesn’t create a paper trail, and the person on the other end has no obligation to update anything based on your word. The other common mistake is paying it again just to make the calls stop — that doesn’t fix a records error, it just teaches the collector that pressure works. Do this in writing instead, and don’t send a second payment out of fear.
One check before you send anything: make sure this is genuinely the same account you paid, not an older debt with a similar balance or a similar name. If you aren’t certain, don’t make a payment and don’t put in writing that the debt is yours — in many states, paying on or acknowledging an old unpaid debt can restart the clock a collector needs to sue you. Dispute it and ask them to verify instead; that costs you nothing. To be clear about the difference, because it matters: sending proof that you already paid a specific account is not the same as admitting you currently owe money. Revival turns on what you actually do, not on how certain you feel — and what counts varies by state. A partial payment restarts the clock in many states; some require a signed writing acknowledging the debt before anything restarts; a few will act on less. So if this debt might be old enough to be time-barred, keep the first letter bare: dispute it, demand verification, and don’t say the debt is or was yours. If you know you paid it and it isn’t an old account you might be confusing it with, send the proof.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
Your Options Right Now
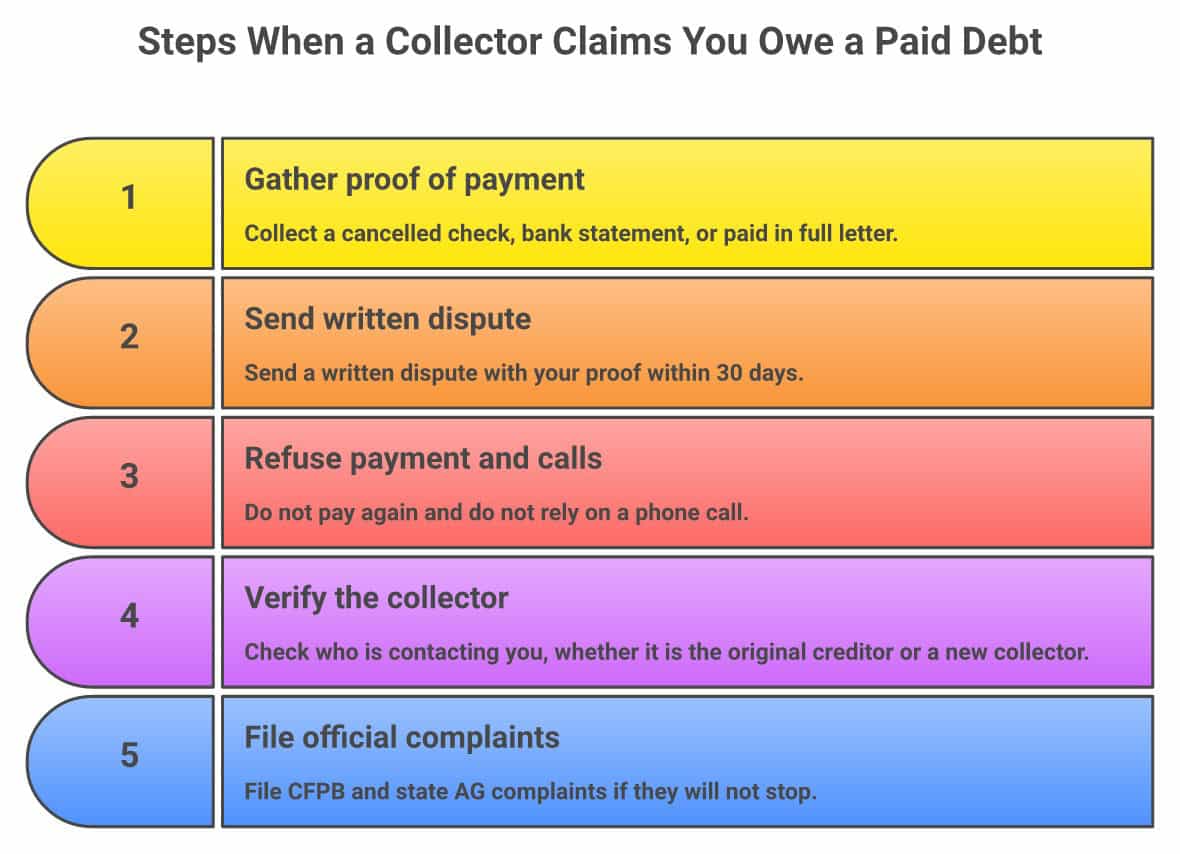
What to Do Right Away
- Pull together your proof of payment. A cancelled check, a bank or credit card statement showing the payment posted, an online payment confirmation, or a “paid in full” or “zero balance” letter from the original creditor. Make copies — never mail your only original.
- Send a written dispute within 30 days of receiving the collector’s validation notice — that’s the letter that spells out your right to dispute, not necessarily the first thing they mailed you. The clock runs from when it reaches you, not from the date printed on it, and you may have to prove that date — so note the day it arrived and keep the envelope. Which version you send depends on one thing:
• If you’re certain this is the account you paid — include your proof of payment.
• If any real doubt remains that the account is even yours — send the dispute without proof, require them to verify the debt, and don’t write anything that sounds like admitting it’s yours until they show you what they’re actually collecting on.
Under 15 U.S.C. § 1692g(b), a written dispute sent inside that 30-day window requires the collector to stop collecting until it obtains verification of the debt and mails you a copy. Miss the window and you keep every other right — you just lose that automatic pause, so dispute in writing anyway. Use the free Debt Validation Letter Generator and send it by certified mail so you have proof it was received. - Do not send another payment, and don’t rely on a phone call to fix this. If they say “just pay it and we’ll clear it up,” that’s the mistake this guide warns about — get it resolved in writing first.
- Figure out who’s actually contacting you. Is it the original creditor, or a different company than the one you paid? If your paid account got sold or placed with a new collector, that transfer itself may be illegal — see the section below on Regulation F’s limit on selling or placing a debt the collector knows was already paid. (That rule binds debt collectors — and debt buyers only where they meet the statutory “debt collector” definition — not your original bank or hospital.) Check them out on the Scam-O-Meter first.
- If they won’t stop, or threaten a lawsuit or your credit, get help. NACA can connect you with a consumer attorney — many take FDCPA cases on contingency, because the law makes a losing collector liable for your attorney’s fees in an amount the court finds reasonable. You can also talk to Damon Day for free about your overall situation.
Free Tool — Debt Validation Letter Generator: Being contacted by a debt collector? The free Debt Validation Letter Generator creates a personalized FDCPA validation letter in seconds — forcing the collector to prove the debt is real before they can continue. Generate My Letter →
How to Actually Stop It — Your 4 Paths
- Written dispute + proof of payment (fastest, works most of the time). This is almost always the right first move. It forces the collector to stop collecting until it mails you verification. Sending you that verification is allowed; going back to demanding payment before it does is not. And it puts your evidence on the record — which matters if this ever ends up in front of a judge.
- File complaints with the CFPB and your state attorney general. This doesn’t just document the problem — it puts the collector’s regulator on notice, and companies respond to regulatory pressure differently than they respond to a customer on the phone.
- Get a consumer attorney involved if they won’t stop. A collector that keeps demanding money on a debt it knew or should have known was paid may owe you statutory damages — up to $1,000 in an individual lawsuit under 15 U.S.C. § 1692k(a)(2)(A) (that ceiling is on statutory damages for the whole case — not a per-call bonus, and not a cap on what else you can recover; class actions run on a different formula under § 1692k(a)(2)(B)), plus your actual losses and, if you win, attorney’s fees the court finds reasonable.
- What WON’T work: ignoring it and hoping it goes away. Debt that’s technically already paid can still get re-sold, re-reported, or turned into a lawsuit if nobody corrects the record. Silence doesn’t fix a paperwork error — only a written dispute does.
What You Need to Know About Your Rights
“attempts to collect a debt not owed” has been the predominant debt collection complaint issue since the CFPB began taking them in 2013
of consumers who told the CFPB in 2024 that a debt wasn’t owed said the reason was that it had already been paid
from receiving the collector’s validation notice, to dispute in writing and force them to stop until they verify
the ceiling on statutory damages in an individual FDCPA lawsuit — your actual losses are recoverable on top and aren’t capped by it
Two different federal rules apply here, and which one is yours depends on what actually happened.
If your paid account got sold, transferred, or handed to a new collector: 12 CFR § 1006.30(b)(1) (Regulation F, which implements the FDCPA) says a debt collector “must not sell, transfer for consideration, or place for collection a debt if the debt collector knows or should know that the debt has been paid or settled or discharged in bankruptcy.” The rule opens “Except as provided in paragraph (b)(2)” and does carve out some transfers — back to the debt’s owner, back to a previous owner where the original contract allows it, or as part of a merger or sale of the business. In plain terms: passing your paid-off account along to somebody new isn’t just sloppy record-keeping — it can be a violation on its own, separate from whatever happens when they contact you. Note the limits: this binds debt collectors, and it turns on what they knew or should have known.
If it’s the same collector that just never updated its records: no sale or transfer happened, so § 1006.30(b)(1) isn’t the rule doing the work — § 1692e is. That distinction matters if you ever put your complaint in writing to a regulator or an attorney, because citing the wrong provision is an easy way to be waved off.
On top of that, 15 U.S.C. § 1692e(2)(A) bars a collector from falsely representing “the character, amount, or legal status of any debt,” and § 1692e(8) bars communicating credit information the collector knows or should know is false — and reporting a debt you already paid as still owed is exactly that. One important limit: the FDCPA generally applies to third-party collectors, and to debt buyers that meet the statutory “debt collector” definition — not to your original bank, hospital, or landlord collecting in its own name — though several states close that gap.
| Jurisdiction | Who’s Covered | Notes |
|---|---|---|
| Federal (FDCPA) | Third-party collectors, and debt buyers that meet the statutory “debt collector” definition | Generally does not reach your original creditor collecting under its own name; a company collecting debts it bought for its own account isn’t automatically covered either |
| California (Rosenthal Act) | Original creditors AND collectors | Civ. Code § 1788.17 imports the FDCPA’s rules and remedies and applies them to the original creditor too |
| Texas (TDCA) | Original creditors AND collectors | Tex. Fin. Code Chapter 392 covers the bank or provider that extended the credit, not just a hired agency |
| Massachusetts | Creditors AND collectors | 940 CMR 7.00, the Attorney General’s debt collection regulation issued under M.G.L. c. 93A, defines “creditor” to reach a party collecting a debt owed to itself |
If you’re in California, Texas, or Massachusetts and it’s your original bank, hospital, or landlord (not a separate collection agency) still demanding money after you paid, you likely have protections the federal law alone wouldn’t give you. Check with a NACA consumer attorney in your state for how that applies to your situation.
If a collector won’t correct the record after you’ve sent proof, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, and I know what it feels like when debt won’t let go even after you’ve done everything right. Getting a call demanding money on something you already paid isn’t really a math problem — it’s someone hoping panic will make you pay twice instead of checking the paperwork. Don’t let fear write a second check. Get your proof together, put it in writing, and make them prove their records instead of trusting yours. That’s not you being difficult. That’s you being right.
Frequently Asked Questions
I already paid this debt — can they still legally come after me for it?
If you truly paid it, you don’t owe it. 12 CFR § 1006.30(b)(1) bars a debt collector from placing a paid debt for collection at all if it knew or should have known it was paid, and 15 U.S.C. § 1692e(2)(A) bars misrepresenting the debt’s status. Once they have your proof, continuing to demand payment can become a real legal problem for them rather than just a mistake — though liability turns on what the collector knew or should have known, so get their confirmation in writing rather than assuming the matter is closed. What a dispute letter does not do is make a lawsuit physically impossible — a collector can still file, and if there’s a genuine argument about whether your payment covered the whole balance, that’s worth running past a consumer attorney. Never ignore court papers.
Do I have to prove I paid it, or is that on them?
Technically, the collector has to be able to substantiate the debt if you dispute it. Practically, sending your own proof of payment — a statement, cancelled check, or paid-in-full letter — is the fastest way to shut this down, because it forces the issue instead of leaving it to their internal review.
What if I don’t have the original receipt anymore?
You usually don’t need it. Most banks and credit card companies let you pull old statements online going back years, and you can request a “paid in full” or “zero balance” letter directly from the original creditor. A cleared check image from your bank works too.
Can I get money from them for putting me through this?
Possibly. If a court finds a real violation, the FDCPA allows up to $1,000 in statutory damages in an individual lawsuit under § 1692k(a)(2)(A) — that’s a ceiling on the statutory piece for the whole case, not $1,000 per call — plus your actual damages and, if you win, your attorney’s fees. That fee-shifting is why many consumer attorneys take these cases on contingency, with no fee up front.
Is this the same problem as a paid collection still showing on my credit report?
No, and it’s worth knowing the difference. This guide is about a collector actively demanding money after you paid. If the debt is paid but a collection account is still sitting on your credit report, that’s a separate credit-reporting fix under a different law — see my companion guide, I Paid Off My Collection — So Why Is It Still on My Credit Report?, for that half of the problem.
What if it’s my original bank or hospital calling, not a collection agency?
The federal FDCPA generally covers third-party collectors — and debt buyers only where they meet the statutory “debt collector” definition — not your original creditor collecting under its own name. But California, Texas, and Massachusetts (among others) extend similar rules to original creditors too. Either way, send your proof of payment in writing and ask for written confirmation the account is closed.
I already told them on the phone that I paid it — isn’t that enough?
No. A phone call doesn’t create a record and doesn’t legally require them to stop. Put your dispute and your proof in writing, ideally by certified mail, so you have proof it was sent and received.
What if they sold my already-paid debt to a totally different collector?
That’s specifically what 12 CFR § 1006.30(b)(1) is meant to stop — selling, transferring, or placing for collection a debt the seller knew or should have known was already paid. One limit worth knowing: that rule binds sellers who are themselves debt collectors under the FDCPA, so if your original creditor — not itself a debt collector — was the one that sold it, the sale itself generally isn’t reached by this provision — though what the buyer does next still is. If that happened to you, it strengthens your dispute and your case if you end up talking to an attorney.
One more thing — everything I share here is based on more than 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A collector demanding money on a debt you already paid is a paperwork problem you can fix, not a debt you actually owe. Gather your proof, put your dispute in writing, and don’t pay twice out of fear. Without a written dispute on the record, nothing obliges the collector to stop or to verify anything — and nothing stops the account from being sued on or reported. The dispute is what puts your objection on file and triggers their duty to verify.
The Bottom Line
You didn’t do anything wrong — you paid what you owed. A records error, a bad debt sale, or a company hoping you won’t check your own paperwork is not the same thing as owing money. The people who resolve this fastest are the ones who get their proof together and put it in writing right away, instead of waiting to see if the calls stop on their own. If someone you know is getting collection calls on a debt they already paid, send them this page — the written-dispute step is the one most people skip, and it’s the one that actually works. For the full picture of your options, see the Find Your Path quiz.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



