

A Get Out of Debt series · Reading the filings so you don’t have to
What They Told Wall Street
FORM 8-KSLM CORPORATION (SLM)FILED 08/05/2026ITEM 7.01 · REGULATION FD DISCLOSURECIK 0001032033
This week Sallie Mae’s parent company filed a routine Regulation FD disclosure with the SEC — just posting its quarterly investor slide deck, the kind of filing that happens four times a year and rarely says anything new. Except this one repeats something Sallie Mae has now told Wall Street three separate times since June: that, in the company’s own account, a category of outside companies is talking its borrowers — people who could actually afford to keep paying — into defaulting on purpose.
One thing to get straight before I go further, because it gets confused constantly — including, I suspect, by whatever scraped this filing first: Sallie Mae is not Navient. The old Sallie Mae split into two separate public companies on April 30, 2014. Navient took the education loan management, servicing, and asset-recovery business, which was mostly federally guaranteed loans. Today’s SLM Corporation kept the Sallie Mae name and kept making private student loans — the loans made directly by a bank to a student and, usually, a cosigner (84% of the loans it approved last quarter had one). This week’s filing says so itself: Sallie Mae calls itself the “Market leader in private education lending.” It doesn’t service federal student loans anymore either — its own annual report shows it sold the last of its federally guaranteed FFELP loan portfolio in late 2024. And across the three filings I read for this piece, I found no support for a figure like “24 million federal borrowers” being tied to Sallie Mae. If you saw that number attached to this story, it’s wrong — drop it.
What the pitch sounds like
Something like: “We can refinance or resolve your Sallie Mae loan for you — just stop making your current payments and let us handle it.” (An illustrative example, not a quote from any real company.)
What Sallie Mae told the SEC
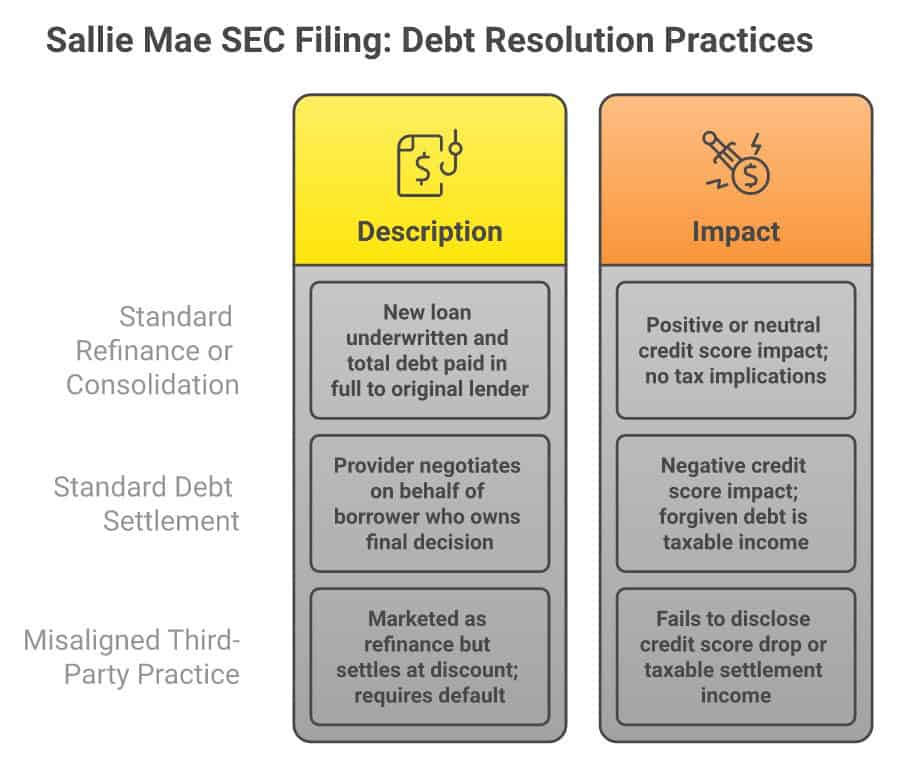
Some of these “third-party debt resolution” pitches aren’t refinancing anything. They’re getting borrowers — including ones who could keep paying — to default on purpose, without disclosing the credit damage or the tax bill that follows.
A public company has to tell investors the truth about what’s happening inside its loan book, because misleading Wall Street is a federal securities violation. It doesn’t have to tell you anything it isn’t required to. That gap is the whole reason this series exists. Usually the “receipt” I find in these filings is something a lender would rather not admit about its own loans. This time it’s different: Sallie Mae is the one blowing the whistle — on a pattern of behavior by companies working its own borrowers, not on itself.
The disclosure
Net Charge-Offs $113M — “Primarily impacted by the previously discussed misaligned third-party debt resolution practices, and related shifts to our recovery strategies, which represents approximately $16M of the year-over-year increase.”
What I think they’re really saying
“Previously discussed” is the tell. This isn’t a new admission — it’s Sallie Mae confirming, for the third filing in a row, that a specific line on its own balance sheet is getting worse because of what a category of outside companies is doing to its borrowers. Read the sentence carefully, though: the roughly $16 million figure is attributed to both the third-party practices and “related shifts to our recovery strategies” — and the June 10 deck lists, under its own “Key Strategic Actions,” “Pausing recovery loan sales & certain settlements.” So an unknown share of that $16 million traces to Sallie Mae’s own business decision, not just to what outside companies are doing to its borrowers. I don’t have a way to split the two apart from what’s public, and you should hold that caveat over every dollar figure in this piece.
“Net charge-offs were $113 million, an increase from the year-ago quarter, which we believe is primarily driven by misaligned third-party debt resolution practices affecting a small, high-ability-to-pay segment of borrowers progressing straight through delinquency to default, and related shifts to our recovery strategies.”
What I think they’re really saying
Read that phrase again: “high-ability-to-pay segment.” Sallie Mae isn’t describing people who ran out of money. It’s describing borrowers who could have kept paying and didn’t — going “straight through” delinquency to default, skipping the usual slow slide. That’s not what happens when someone loses a job. That, as Sallie Mae is describing it, is what happens when someone tells you to stop paying — though the filing is the company’s account of the pattern, and I can’t independently confirm the cause in any individual case.
“MISALIGNED Third-Party Debt Resolution Practices: Marketing a private student loan refinance solution with a loan for the full amount plus fees, while settling with the original lender at a discount. Requiring borrowers to stop making payments and default, even when many have both the willingness and capacity to pay. Failing to communicate that triggering a default will cause a severe, long-lasting drop in their credit score and the settlement may have tax implications since forgiven debt is taxable income to the individual.” — “We believe these practices are resulting in customer harm and unintended outcomes and are not indicative of broader credit deterioration.”
What I think they’re really saying
This is the slide where Sallie Mae spells it out for investors so there’s no ambiguity about what “misaligned” means. Strip out the corporate language and here’s the sequence it’s describing: a company markets itself as arranging a “refinance,” charges the borrower fees on the full balance as if it originated a real new loan, then separately negotiates a discounted payoff directly with Sallie Mae — a discount that, as Sallie Mae describes it, follows the borrower being steered into stopping payment and defaulting. That is not a refinance. A refinance replaces your loan with a new one and pays the old lender in full. What’s described here reads to me like debt settlement wearing a refinance label — and, by Sallie Mae’s own account, it’s being sold to people who didn’t need it. That last part is Sallie Mae’s characterisation of the conduct, not a finding by any court or regulator.
What the law actually says
Sallie Mae’s filing doesn’t name a specific company, and neither will I — there’s no enforcement action naming one, so there’s nothing to point at yet. What I can tell you is what federal law already requires of any company that telemarkets a “debt relief service,” which includes debt settlement pitched over the phone or through a lead-gen call. Under the FTC’s Telemarketing Sales Rule, 16 C.F.R. § 310.4(a)(5)(i):
“It is an abusive telemarketing act or practice and a violation of this part for any seller or telemarketer to engage in the following conduct: … Requesting or receiving payment of any fee or consideration for any debt relief service until and unless: (A) The seller or telemarketer has renegotiated, settled, reduced, or otherwise altered the terms of at least one debt pursuant to a settlement agreement, debt management plan, or other such valid contractual agreement executed by the customer; (B) The customer has made at least one payment pursuant to that settlement agreement, debt management plan, or other valid contractual agreement between the customer and the creditor or debt collector; and…”
The rule has a third condition I have left out of the quote for length: where debts are settled one at a time, § 310.4(a)(5)(i)(C) also dictates how each fee may be calculated — either in the same proportion that the individual debt bears to the whole enrolled balance, or as a percentage of the amount actually saved.
In plain English: it is illegal for a telemarketed debt settlement operation to collect a fee from you before it has actually settled at least one of your debts and you’ve made at least one payment on that settlement. This is called the advance-fee ban, and it’s been federal law since late 2010. Two scope points worth knowing, because they cut in opposite directions: the rule generally does not reach a deal done entirely face to face — but do not assume you lose it just because you placed the call. The Telemarketing Sales Rule normally exempts calls a consumer makes in response to an ad, and 16 C.F.R. § 310.6(b)(5)(i) specifically excludes debt relief services from that exemption by name. Calling the number in the ad does not hand them a free pass. If a company that pitched you a Sallie Mae “refinance” or “resolution” collected money up front — before settling anything — that’s the specific tell the FTC built this rule to catch, and it’s worth reporting to the FTC, your state attorney general, and GOOD’s own Debt Relief Scam Reporter. It’s the same “pay first, promises later” shape I’ve written about with companies charging a fee for faster student loan forgiveness — different pitch, same tell.
The tax piece Sallie Mae’s slide flags is real too, and it’s the part almost nobody explains up front. Under 26 U.S.C. § 61(a)(11) — renumbered from the old § 61(a)(12) by the 2017 Tax Cuts and Jobs Act, so older articles cite it differently — canceled or forgiven debt is generally counted as taxable income to you. The IRS calls it “income from discharge of indebtedness.” Where $600 or more is cancelled, the entity that forgives it is generally required to report the discharge to you and the IRS on a Form 1099-C — though not every negotiated discount trips that trigger, and if your loan was sold the filer may be whoever holds it now, not the original lender. I’ve written a full breakdown of when that tax bill can actually be avoided (insolvency is the big one) — read the 1099-C tax bomb piece before you assume forgiven debt is free money.
Free Tool — 1099-C Tax Calculator: Received a 1099-C for cancelled debt? The free 1099-C Tax Calculator runs the exact IRS insolvency math from Publication 4681 Worksheet 2 — and covers the partial insolvency case most people miss. Run the Calculator →
What Sallie Mae itself already offers
Sallie Mae’s own hardship programs, from the same filing
In plain English
The same Aug. 5 investor deck lists the payment programs Sallie Mae says it makes directly available to borrowers who are struggling — no third party, no fee to a stranger, and none of them require you to default first:
- In-School Payment Assistance — for customers with scheduled payments while still enrolled;
- Early Repayment Assistance — up to 6 months of payment deferment after the grace period that follows leaving school;
- Short-Term Interest-Only — payments drop to interest-only for 12 months after leaving school;
- In-Repayment Forbearance — up to 2 months at a time, up to 12 months over the life of the loan;
- Reduced Payment — interest-only payments for a set period;
- Loan Modification — the filing says this can adjust the contractual interest rate between 2% and 8% temporarily, and in some cases permanently extend the final maturity date, based on need and eligibility.
I’m quoting Sallie Mae’s own description of its own programs here — I have no independent way to confirm how easy any of them are to actually get approved for, and eligibility is Sallie Mae’s call, not mine. But the first call, if you’re struggling with a Sallie Mae loan, should be to Sallie Mae — not to whoever emailed or called you promising to make the loan disappear. One exception worth knowing: if the loan is old enough that you think the window for suing on it may have closed in your state, talk to a consumer attorney first — in some states making a payment or signing a written acknowledgment can restart that clock, though simply calling to ask what programs exist generally does not.
What this means for you
If someone contacts you offering to “refinance,” “resolve,” or “settle” a Sallie Mae loan for a fee, slow down before you agree to anything. A real refinance pays your existing lender in full with a new loan — if the pitch instead involves you stopping payments to Sallie Mae while the company “works on it,” that is not a refinance, whatever it’s called.
What I’d do — Call the number on your actual Sallie Mae statement, or go to salliemae.com directly, and ask what hardship programs you already qualify for before paying anyone else a dime. If a company selling debt settlement over the phone or through a lead-gen call asks for money before it has settled anything, that’s illegal under the FTC’s advance-fee ban — walk away and report it. Run any company through the Scam-O-Meter before you sign. And if the real problem is that this debt, on top of others, is genuinely unmanageable — not just a company trying to talk you into default — know that private student loans can sometimes be discharged in bankruptcy — usually where the loan doesn’t meet the legal definition of a “qualified education loan,” or where you can show undue hardship. It is fact-specific and it is not the common outcome, so treat it as a question to ask rather than a plan to count on. A consumer bankruptcy attorney can tell you honestly whether yours qualifies, without asking you to default first. (If you’re drowning in private student loan debt, that piece walks through the wider picture.)
Steve’s bottom line
Debt is math wrapped in emotion, and the companies that profit from your confusion count on you never seeing the math. What’s notable here is who’s pointing that out: not a regulator, not a competitor — the lender itself, in a filing where it’s legally required to tell the truth. Sallie Mae says a slice of its own borrowers are being talked into defaulting when they didn’t have to, by companies charging fees for something that isn’t what it’s sold as, while leaving out the two things that matter most: what it does to your credit, and what it does to your tax return.
I’m not telling you every private “student loan help” company operates this way — most consumer debt professionals do real work. I’m telling you that if the pitch is “stop paying and let us handle it,” ask what happens to your credit score and your tax bill before you agree to anything, and verify directly with Sallie Mae what it will actually do for you for free.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Frequently asked questions
Is Sallie Mae the same company as Navient?
No. The old Sallie Mae split into two separate public companies on April 30, 2014. Navient took the education loan management, servicing, and asset-recovery business, which was mostly federally guaranteed loans. Today’s SLM Corporation kept the Sallie Mae name and continues to make private student loans directly to borrowers and cosigners.
Does Sallie Mae service federal student loans?
No. Sallie Mae describes itself in its own SEC filings as the “market leader in private education lending,” and its 2025 annual report shows it sold the last of its federally guaranteed FFELP loan portfolio in late 2024. It is a private student loan originator, not a federal loan servicer.
What did Sallie Mae actually tell the SEC?
Across three 2026 filings, Sallie Mae told investors that a “small, high-ability-to-pay segment” of its borrowers is defaulting because of what it calls “misaligned third-party debt resolution practices” — companies marketing a “refinance” that’s really a settlement negotiated after the borrower stops paying, without disclosing the credit or tax consequences.
Is it illegal for a company to charge an upfront fee to “settle” my student loan?
If the service is telemarketed, yes — the FTC’s Telemarketing Sales Rule (16 C.F.R. § 310.4(a)(5)(i)) bans debt relief companies from collecting any fee until they’ve actually settled at least one debt and you’ve made at least one payment on that settlement.
Will forgiven private student loan debt be taxed?
Generally yes. Canceled debt is treated as taxable income under 26 U.S.C. § 61(a)(11) (the old § 61(a)(12) before the 2017 tax law renumbered it). Where $600 or more is forgiven, the entity cancelling it is generally required to report the discharge to you and the IRS on Form 1099-C. There are exceptions, the big one being insolvency — see my full breakdown of when that tax bill can be avoided.
What should I do instead of using a third-party “debt resolution” company?
Contact Sallie Mae directly first and ask about its own hardship programs — in-school assistance, early repayment assistance, interest-only periods, forbearance, and loan modification. If the debt is genuinely unmanageable across multiple accounts, talk to a consumer bankruptcy attorney about whether the loan can be discharged before paying any third party a fee.
Read it yourself — the primary sources
SLM Corporation — Form 8-K, Item 7.01, filed August 5, 2026 (SEC.gov) →
SLM Corporation — Form 8-K, Q2 2026 earnings release, filed July 23, 2026 (SEC.gov) →
The “misaligned third-party debt resolution practices” language appears in all three filings; the Aug. 5 filing is a Regulation FD disclosure of the Q2 2026 investor presentation and explicitly refers back to the two earlier filings as “previously discussed.” All three exhibits are furnished to the SEC under Item 7.01 or 2.02, not “filed” — each one says so, and expressly disclaims Section 18 liability for the furnished material. That’s a lower formal bar than a 10-K or 10-Q, though materially false statements to investors can still carry securities-fraud liability. To find any company’s filings yourself, search the company name at sec.gov/edgar/search.
How to read this
Two different things appear above, kept separate on purpose. The quotes in the gray boxes are fact — Sallie Mae’s own words, from its own SEC submissions, furnished to the SEC and posted for investors as public record, quoted verbatim and linked. The plain-English explanations are my interpretation, offered to help you understand what the filing language means — not Sallie Mae’s position, and not a statement about any specific company or your specific loan. To be exact about it: only the text inside a quote block carrying a live SEC or government-source link is verbatim — that covers Sallie Mae’s filings and the federal regulation quoted further down. The comparison box near the top and the summaries elsewhere are my own words restating the filing, not quotations. And I make no claim about any specific company’s conduct beyond what Sallie Mae itself reports in the filings quoted here.
Sallie Mae’s filing does not name any third-party company, and neither do I — I have no enforcement action or lawsuit to point to naming a specific business, so I’m not accusing one. I’m describing, using the lender’s own words, a pattern of practice it says is affecting its borrowers, and explaining the federal law that already governs it. This is general information and my opinion after more than 30 years helping people with debt, not legal or tax advice. Whether the advance-fee ban or the 1099-C rules apply to your situation depends on your own facts; talk to a consumer attorney or tax professional before acting.
Know someone with a Sallie Mae loan who’s gotten one of these “refinance” calls or emails? Please forward this to them. The company that holds the loan just told Wall Street what it says the pitch really is — that’s worth knowing before anyone signs anything.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
“What They Told Wall Street” reads the SEC filings of the companies that handle your money and translates what they admitted — one filing at a time. Sourced entirely from public SEC records. · See the whole series →



