

Written by Steve Rhode, consumer debt expert since 1994 • Last updated August 10, 2026
Quick Answer: Falling behind on Chapter 13 payments does not automatically end your case — but ignoring it will. In FY2025, more Chapter 13 cases were dismissed than completed — that counts cases exiting in a single fiscal year rather than following one group of filers start to finish — so you are not alone and this is not rare. You have three real paths before dismissal: ask the court to modify your plan under 11 U.S.C. §1329, request a hardship discharge under §1328(b), or convert to Chapter 7 under §1307(a). Call your attorney — or the trustee’s office if you’re pro se — today. Don’t wait for the motion to dismiss to show up in the mail.
What Just Happened to Your Chapter 13 Case
You missed a payment, or several, and now you’re worried the trustee is about to pull the plug. Here’s what’s actually happening behind the scenes: your trustee — the person the court appointed to collect and distribute your plan payments — is required to flag a shortfall. Depending on your district, that can mean an informal letter, a formal notice, or, if it goes far enough, a motion to dismiss for “material default by the debtor with respect to a term of a confirmed plan” under 11 U.S.C. §1307(c)(6).
Nothing about that motion is automatic. A judge has to grant it, after notice and a hearing, and you — or your attorney — get a chance to respond before it happens. But read that phrase carefully, because it does not mean what most people assume. “After notice and a hearing” is a defined term in 11 U.S.C. §102(1), and it guarantees you an opportunity for a hearing, not an actual one — §102(1)(B)(i) lets the court act with no hearing at all if nobody requests one in time. So the deadline printed on the paperwork you were mailed is the thing that matters. Miss it and your case can be dismissed without you ever standing in front of a judge. That gap between “I’m behind” and “my case is dismissed” is where you have the most power to act, and it’s the part almost nobody explains to you.
The Mistake You’re About to Make: Assuming nothing can be done, and either going quiet on your attorney out of embarrassment, or quietly falling behind on your trustee payment while continuing to send your mortgage payment straight to the servicer. If your district runs your mortgage as a “conduit” payment — meaning it flows through the trustee as part of your plan — paying the servicer directly while your plan payment is also short can create a default the servicer counts differently than the trustee does. Talk to your attorney before you change how or where any money moves.
One thing that can turn a wobble into that exact kind of default: taking out new debt — like a title loan — without asking first. Here’s what most trustees require before you sign anything new.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Your Options Right Now
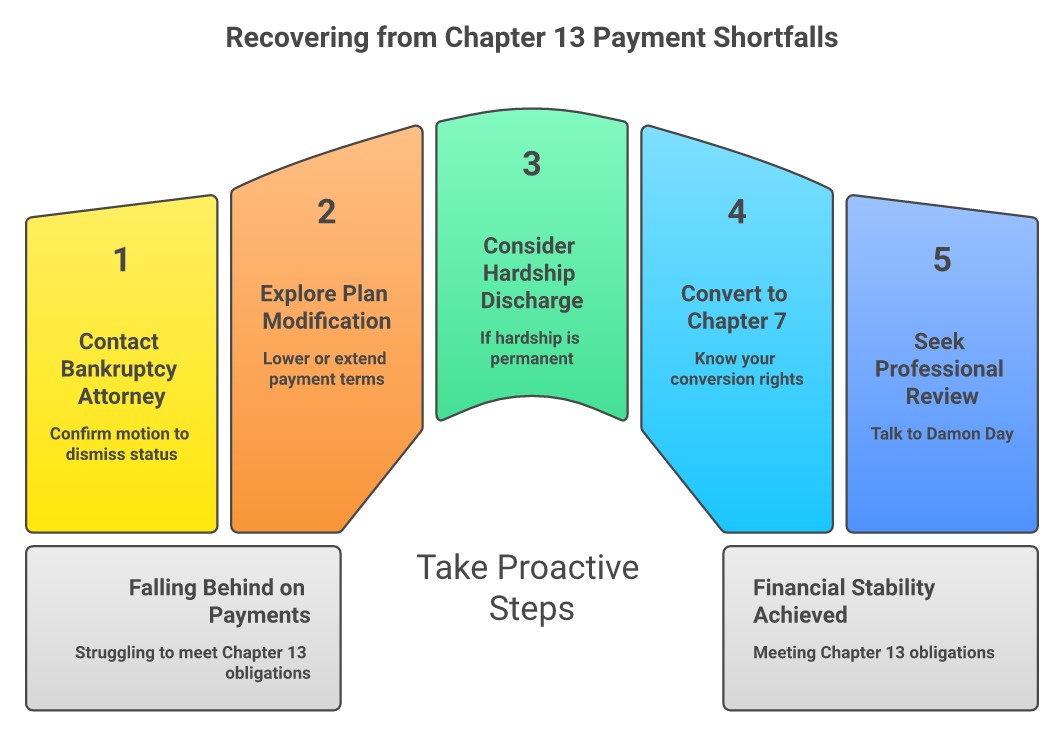
What to Do in the Next 48 Hours
- Call your bankruptcy attorney today — or the trustee’s office if you filed pro se. Ask directly: has a motion to dismiss actually been filed, or is this still a notice? You can also check your case docket through your district’s bankruptcy court.
- Ask about a plan modification under 11 U.S.C. §1329. The debtor, the trustee, or an unsecured creditor can request one “at any time after confirmation of the plan but before the completion of payments” — to lower the payment, extend the time to pay, or both, without starting the case over.
- If your income drop looks permanent, ask about a hardship discharge under 11 U.S.C. §1328(b). It has three conditions, and you need all three — see the comparison table below.
- Know your right to convert to Chapter 7. Under 11 U.S.C. §1307(a), you can convert “at any time” — the trustee and your creditors can’t block it. A handful of courts have denied a conversion in extreme, clearly bad-faith cases, but that point is unsettled and varies by circuit, so don’t assume it applies to you. It’s a different bankruptcy, not a failure. NACBA can connect you with a bankruptcy attorney who handles conversions, and take my 2-minute quiz to see how the math looks either way.
- Talk to Damon Day for free. Damon Day has walked thousands of people through exactly this fork in the road, at no cost to you.
How to Actually Stop It — Your 4 Paths
- Modify the plan (fastest, keeps your case alive). A modification under §1329 can lower the payment or stretch it out — but a modified plan generally can’t run past the applicable commitment period unless the court, for cause, approves a longer period, and it can never exceed five years total.
- Request a hardship discharge. Under §1328(b), the court can discharge you without finishing payments — but only if all three conditions hold. Two things it does not do, and both matter: §1328(c) excepts debts of a kind listed in §523(a), and it also excepts long-term debts your plan was curing and maintaining under §1322(b)(5) — which for most people means the mortgage. A hardship discharge does not save the house. If your plan was catching up arrears, that debt survives intact and the lender can pick up where it left off.
- Convert to Chapter 7. Your right under §1307(a) — no permission from the trustee or your creditors required. Check one thing first, because converting into a dead end is a real risk: you still have to qualify for a Chapter 7 discharge. There are two lookback bars. Under §727(a)(8) you cannot get a Chapter 7 discharge if you already received one in a Chapter 7 or Chapter 11 case filed within the previous eight years. Under §727(a)(9), a prior Chapter 13 discharge from a case commenced within the previous six years blocks it too — but not always: that bar lifts if your payments under the earlier plan came to 100% of allowed unsecured claims, or to 70% under a plan you proposed in good faith that represented your best effort. Because §348(a) says conversion does not change your filing date, both of those clocks run from the day you filed this case, not from the day you convert. Read the complete Chapter 7 guide before you decide.
- What WON’T work: going quiet. Not answering the trustee’s calls, not showing up to the hearing, or hoping the case just disappears. It doesn’t disappear — it gets dismissed under §1307(c), and everything you were protected from comes right back.
What You Need to Know About Where Chapter 13 Cases Actually End Up
Those FY2025 numbers — roughly 180,000 Chapter 13 case exits reported in the U.S. Trustee Program’s FY2025 audited annual trustee reports, 52.1% dismissed, 42.6% completed/discharged, 5.3% converted — are exits recorded in one fiscal year across many different filing cohorts, not a single group of people tracked start to finish, and in that year dismissals outnumbered completions. If you’re behind right now, you’re in the majority of people who ever struggle with a Chapter 13 plan, not some rare failure.
| Option | What Happens | Best When |
|---|---|---|
| Plan modification (§1329) | Payment amount or length changes; case stays open | Income drop is temporary or partial, or a debt was paid off outside the plan |
| Hardship discharge (§1328(b)) | Discharge granted without finishing payments, only if all 3 conditions are met | Permanent hardship (disability, death, job loss with no recovery) AND unsecured creditors already got at least Chapter 7 value AND modification isn’t practical |
| Convert to Chapter 7 (§1307(a)) | Case becomes a liquidation case — but your ORIGINAL filing date still controls (§348(a)), so the means test and exemptions are measured from then, not from the conversion | You can’t sustain any Chapter 13 payment and most of your debt is dischargeable |
| Dismissal (§1307(c)) | Case ends, automatic stay ends immediately (§362(c)(2)(B)), creditors resume collection | Never — this is the default outcome of doing nothing |
If your Chapter 13 runs your mortgage through the trustee (a “conduit” plan), your monthly payment can look dramatically different from someone else’s with the exact same debt — the trustee’s percentage fee is charged on that mortgage money too, and the fee rate varies by district. See the complete guide to Chapter 13 and your mortgage for how that plays out.
If your case is dismissed and your mortgage servicer restarts foreclosure, file a complaint with the CFPB if the servicer isn’t following its own loss-mitigation rules, and check your state attorney general’s office for state-specific protections. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov. The CFPB’s page on what to do if you can’t pay your mortgage explains your servicer’s obligations even outside bankruptcy.
Steve’s Take
I filed bankruptcy in 1990, and I’ve talked to thousands of people who were exactly where you are right now — behind on a Chapter 13 payment, terrified they blew it, embarrassed to call their own attorney back. You didn’t fail. In FY2025 more Chapter 13 cases ended in dismissal than in completion — that is one year’s exits, not a lifetime failure rate, and it is not a number the industry advertises, but it is the government’s own reported math. Debt is math wrapped in emotion, and right now the emotion is doing all the talking. Pick up the phone, get the real facts about your specific case, and make the decision that protects your future — not the one that just avoids an uncomfortable call today.
Free Tool — Bankruptcy Means Test: Wondering if you qualify for Chapter 7 bankruptcy? The free Bankruptcy Means Test checks eligibility based on your state, household size, and income — including state exemptions. Check My Eligibility →
Frequently Asked Questions
I missed a Chapter 13 payment — is my case automatically dismissed?
No. Dismissal for “material default” under 11 U.S.C. §1307(c)(6) requires the trustee or a creditor to file a motion, and the court to grant it after notice and a hearing. You get a chance to respond — often by proposing a plan modification — before that happens.
Can I lower my Chapter 13 payment without losing my case?
Usually yes. Under 11 U.S.C. §1329, you, the trustee, or an unsecured creditor can ask the court to modify your confirmed plan — increasing or reducing payments, or extending the time to pay — at any time before you finish. A modified plan generally can’t run past five years total.
What is a Chapter 13 hardship discharge and do I qualify?
Under 11 U.S.C. §1328(b), a court can discharge you without finishing your payments only if all three things are true: your failure to pay is due to circumstances you shouldn’t be justly held accountable for, your unsecured creditors already received at least what they’d have gotten in a Chapter 7 liquidation, and modifying the plan isn’t practical. It does not discharge debts that were never dischargeable to begin with.
Should I convert my Chapter 13 to a Chapter 7?
It’s worth asking your attorney. Under 11 U.S.C. §1307(a), converting is your right — the trustee and creditors can’t stop you. Some courts have denied conversion in extreme, clearly bad-faith cases, but that is an unsettled question that varies by circuit rather than a routine outcome. It tends to make the most sense when you can’t sustain any realistic Chapter 13 payment and most of your debt is the kind Chapter 7 can wipe out. Read real conversion stories before you decide, and my complete Chapter 7 guide for what changes.
My case was dismissed — can my mortgage company foreclose right away?
The automatic stay ends the moment the case is dismissed under 11 U.S.C. §362(c)(2)(B) — there’s no grace period. A servicer can pick a foreclosure up right where it left off. And it is not only your own creditors: if anyone co-signed a debt with you, the co-debtor protection in §1301 ends at the very same moment — §1301(a)(2) names dismissal in its own text — so a collector can start calling your mother, your ex, or whoever signed alongside you the same day. That’s exactly why acting before dismissal, not after, matters so much.
If my case is dismissed, how fast does refiling protect me again?
It depends on your filing history. If you had one case dismissed in the past year, refiling only gives you 30 days of automatic stay protection unless the court extends it, and the law presumes bad faith in specific situations — like a case dismissed for missed plan payments with no real change in your finances since. If you’ve had two or more cases dismissed in the past year, the stay doesn’t take effect at all unless a judge orders otherwise. There is also a harder bar that stops you refiling at all: under §109(g) you cannot be a debtor for 180 days if your case was dismissed because you willfully failed to obey a court order or to appear, or if you asked for the dismissal yourself after a creditor had moved for relief from the stay. That one is not automatic on every dismissal — a plain missed payment does not trigger it — but it is exactly the trap that closes on people who stopped answering the court. Talk to an attorney about this before you refile, not after.
What happens to the money I already paid into my Chapter 13 plan if it’s dismissed?
Whatever the trustee is holding that hasn’t been distributed to creditors yet is generally returned to you, minus fees already earned. Money already disbursed to your creditors stays paid — it isn’t clawed back to you. Ask your trustee’s office for your case-specific accounting.
Why is my Chapter 13 payment so much higher than someone else’s with similar debt?
Geography, mostly. Where your mortgage runs through the trustee as part of the plan — a majority of trustees nationwide handle it this way — the trustee’s percentage fee gets charged on that mortgage money too, and the fee rate is set district by district under 28 U.S.C. §586(e)(1)(B), up to a 10% cap. Two people with identical debts in different courts can end up with payments that differ by thousands of dollars a month.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: Falling behind on Chapter 13 payments is common, not catastrophic — but it requires action before, not after, a dismissal hearing. Take my 2-minute quiz to see where you stand, and talk to your attorney this week. The longer you wait, the fewer options the court has left to work with.
The Bottom Line
You are not a failure because you fell behind — in FY2025 more Chapter 13 cases were dismissed than completed, counting exits in that year rather than one group followed start to finish — and that’s the government’s own math, not mine. The system built in modification, hardship discharge, and conversion for exactly this moment. The people who come out ahead are the ones who call their attorney the day they realize they’re behind, not the day the dismissal notice arrives. If someone you know is quietly panicking about a Chapter 13 payment they can’t make, send them this page — it might be the thing that gets them to make the call. See the complete guide to Chapter 13 and your mortgage and take the Find Your Path quiz for your next step.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 9): The paycheck advance app said it wasn’t a loan. Connecticut just made it give every fee back.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



