

Written by Steve Rhode, consumer debt expert since 1994 • Last updated August 11, 2026
Quick Answer: A creditor who already won a judgment against you can get a separate court order forcing you to appear and answer questions under oath about your income, bank accounts, employer, and property — commonly called a debtor’s examination, examination proceeding, or supplementary proceeding, authorized by Federal Rule 69 or your state’s equivalent. Missing the hearing — not owing the money itself — is what can trigger contempt of court and a bench warrant. Show up, answer honestly, and know that protected income like Social Security cannot be taken to pay this judgment, no matter what you disclose — though money already sitting in a bank account can still be frozen temporarily until you prove where it came from.
What Just Happened to You
The creditor didn’t just win a lawsuit — they got a judgment, which is a piece of paper saying you owe money, not an ATM that spits out cash on its own. To actually collect, most states let a judgment creditor go back to the same court and ask for a separate order compelling you to show up and answer questions under oath about everything you own, earn, and bank. Federal Rule 69 lets a creditor in a federal case use whatever discovery tool the state where the court sits provides; every state runs its own version of this under a different name — “debtor’s examination,” “examination proceeding,” or “supplementary proceeding” are the most common.
This order almost never comes out of nowhere. It typically follows a judgment you may not have contested — sometimes a default judgment entered because you never responded to the original lawsuit. The creditor’s goal is simple: find something — a bank account, a paycheck, a car — worth pursuing next, whether that means a wage garnishment or a frozen bank account.
The Mistake You’re About to Make: Assuming that because you have no money, there’s no point going — or being too embarrassed to sit across from someone asking about your finances, so you just don’t show up. That single decision is what turns a routine, if uncomfortable, court appearance into a contempt hearing and, if you were personally served by a sheriff, marshal, court-appointed person, or registered process server, a real bench warrant for your arrest. The debt itself almost never lands you in a jail cell. Missing court can.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Your Options Right Now
What to Do in the Next 48 Hours
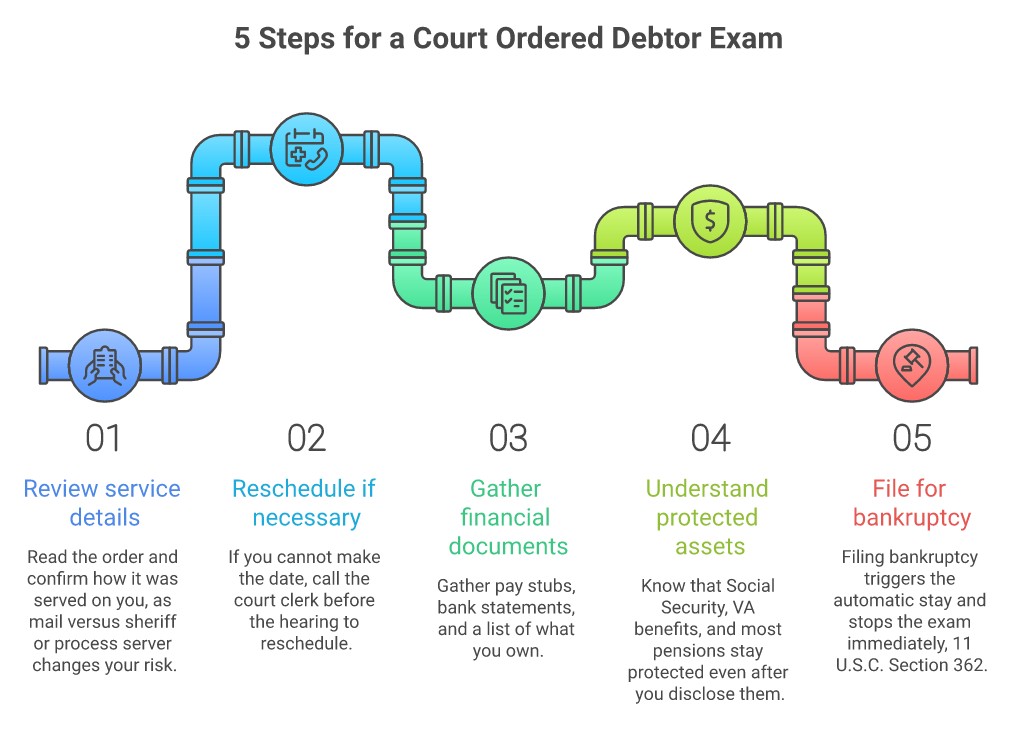
- Read the order carefully and confirm the hearing date and how it was served on you. How it was served matters — in California, for example, a debtor’s exam order served by a sheriff, marshal, registered process server, or someone the court specially appointed carries real bench-warrant risk if you skip it; one served only by mail generally does not. California also requires the order itself to carry a warning — in boldface type, or in capital letters if the form is typed — telling you that failing to appear can expose you to arrest, contempt, and an order to pay the creditor’s attorney’s fees (CCP §708.110(e)). If that block of capital letters is on your paperwork, that is the law talking to you directly — not the collector. Your state court’s self-help center (like California’s) usually explains the process in plain language.
- If you genuinely cannot make the date, act before the hearing — and get it on the docket. Call the court clerk (not the creditor) to ask what that court requires, but know that the clerk cannot grant a continuance. Rescheduling normally takes a filed request, or a written agreement with the creditor that a judge signs off on. A voicemail is not a continuance. Courts often grant a postponement asked for properly and in advance; they almost never forgive a no-show after the fact.
- Pull together basic paperwork: recent pay stubs, bank statements, and a rough list of anything you own of real value. Lying under oath is a separate crime from owing money — accurate answers protect you far better than evasive ones.
- Know your fastest way out, if you need it. Filing bankruptcy triggers the automatic stay the moment you file — 11 U.S.C. §362 stops this exam and every other collection action against you immediately, not weeks later. One caveat that matters if it applies to you: if you had another bankruptcy case dismissed in the past year, §362(c)(3) ends that stay on the 30th day after you file unless the court extends it, and with two or more dismissals in that year §362(c)(4) may mean no stay arises at all unless you ask the court for one. If that is your history, do not skip the hearing assuming you are covered. NACBA can connect you with a bankruptcy attorney, and take my 2-minute quiz to see if the math favors it.
- Talk to Damon Day for free. Damon Day has walked people through exactly this moment more times than he can count, at no cost to you.
How to Actually Stop It — Your 4 Paths
- File bankruptcy — the fastest way to make it stop entirely. For most filers, the moment you file, the automatic stay under 11 U.S.C. §362 halts the debtor’s exam along with every other collection action against you — not eventually, immediately. (The exception is the repeat-filer rule described above: a bankruptcy dismissed within the past year can cut the stay off on the 30th day, and two or more can mean no stay at all unless you ask the court for one.) Federal Reserve Bank of New York research shows people who file bankruptcy recover their financial footing faster than those who keep negotiating around the edges. Take my 2-minute quiz to see how the math looks for you.
- Show up, answer honestly, and lean on what’s exempt. Social Security (42 U.S.C. §407), VA disability and other VA benefits (38 U.S.C. §5301), and employer-sponsored ERISA plans like a 401(k) (29 U.S.C. §1056(d)) stay off-limits to this judgment even after you disclose them under oath. Disclosing an exempt asset is not the same as handing it over. Two honest cautions, though. An IRA is not an ERISA plan — outside bankruptcy its protection comes from your state’s exemption law and varies a great deal, so don’t assume it is shielded the way a 401(k) is. And exempt money can still be frozen: if a creditor learns your account number and levies it, the bank may freeze the balance and leave you to prove the funds came from Social Security or VA benefits to get them released. The benefit is protected; the bank account is not automatically protected, and the burden of showing it lands on you.
- Negotiate on the spot — but get it in writing. Plenty of creditors would rather walk out of that hearing with a signed payment agreement than keep paying an attorney to chase you through the court system. A verbal promise protects nobody. A signed, dated agreement does.
- What WON’T work: ignoring the notice. A 2018 ACLU nationwide investigation reviewed more than 1,000 cases across 26 states in which civil court judges issued arrest warrants over private debt — tens of thousands a year, sometimes to collect amounts as small as $28. The report describes these warrants as issued for people who failed to appear in court, not for the debt itself. (The ACLU is candid that nobody knows the true national total, because courts don’t track these warrants as a category.)
What You Need to Know About Being Ordered to Court
This process is called something different in almost every state, and the consequences for missing it vary with how you were served. That’s exactly why reading your own paperwork carefully — not assuming it works like it does in a TV courtroom — matters more than anything else in this guide.
One thing I won’t pretend away: this process works, and it is supposed to. Answering honestly is both the right call and the safe call — and it is also how a creditor finds the account or the paycheck it goes after next. That’s an argument for knowing exactly what’s exempt before you walk in, and for thinking hard about whether bankruptcy’s automatic stay is the better answer. It is not an argument for hiding anything. The risk of lying under oath is a criminal one. The risk of honesty is a collection step you can usually see coming and plan around.
| Jurisdiction | What It’s Called | Arrest Risk for Missing It |
|---|---|---|
| Federal baseline | FRCP 69 — lets the creditor use the discovery tools of the state where the court sits | The borrowed state procedure governs the exam itself — but a federal court keeps its own independent contempt power over anyone who disobeys its order |
| California | “Debtor’s examination” — CCP §708.110 | Yes, if the order was served by a sheriff, marshal, a person the court specially appointed, or a registered process server (CCP §708.170) |
| New York | Post-judgment disclosure — CPLR Article 52 (§§5223–5224 set the disclosure and subpoena mechanics) | CPLR §5251 makes “refusal or willful neglect of any person to obey a subpoena or restraining notice issued, or order granted, pursuant to this title” and “false swearing upon an examination” each “punishable as a contempt of court” |
| Texas | “Post-judgment discovery” — TRCP 621a | Rule 621a opens the same discovery tools used before trial; enforcement runs through the ordinary discovery-sanctions and contempt process rather than through Rule 621a itself |
| Florida | “Proceedings supplementary” — Fla. Stat. §56.29 | Court can hold you in contempt; under Fla. Stat. §56.29(5) you can’t refuse a fraud-related question on self-incrimination grounds, though that answer can’t be used against you in a criminal case. If anything you’d have to say could expose you criminally, talk to an attorney before the hearing |
If you were personally served by a sheriff, marshal, a court-appointed person, or a registered process server — rather than just mailed the paperwork — treat the hearing date as non-negotiable. That’s the detail that turns “I missed a court date” into “there’s a warrant with my name on it” in states like California. Read the default judgment guide if this exam followed a lawsuit you never answered — it explains how that first miss set this whole chain in motion.
If the creditor or their attorney threatened to have you arrested over the debt itself — not over missing court, but the money — that crosses a line real debt collectors aren’t legally allowed to cross, and it’s worth knowing what to do when a collector says it anyway. File a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, and I remember the fear of sitting across from someone whose entire job was finding out everything I owned. A debtor’s exam feels like the system dragging your whole life into a fluorescent-lit room. But here’s the math: showing up costs you an uncomfortable afternoon. Not showing up can cost you your freedom — for missing a court date, not for owing money. Debt is math wrapped in emotion, and the emotion wants you to hide. Don’t. Show up, tell the truth, know what’s protected, and let the numbers do the talking instead of the shame.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
Frequently Asked Questions
Is it even legal for a debt collector to make me go to court and answer questions about my money?
Yes — but only after they’ve already won a judgment against you. A judgment alone doesn’t let a creditor take anything; it gives them the right to ask the court for a separate order compelling you to disclose your income, bank accounts, employer, and property under oath, authorized by Federal Rule 69 or your state’s own version of the same process.
Can I be arrested for not showing up to a debtor’s exam?
Possibly, yes — but the arrest is for defying a court order, not for the debt. In California, for example, if the order was personally served by a sheriff, marshal, a court-appointed person, or a registered process server and you don’t show up, the court can hold a contempt hearing or issue a bench warrant under CCP §708.170. A 2018 ACLU investigation found this exact pattern playing out in courts across 26 states.
Can I be arrested just because I don’t have money to pay the judgment?
No. Owing money you genuinely cannot pay is not, by itself, a crime, and civil contempt is meant to be coercive, not punitive — a judge is generally supposed to find you have the present ability to comply before jailing you for noncompliance. What actually creates arrest exposure is defying the court’s order to appear, not the size of your bank balance.
Do I have to tell them about my Social Security or VA disability check?
Yes, you have to answer honestly about all your income sources under oath. But disclosing it doesn’t mean the creditor can take it — Social Security and SSI are protected under 42 U.S.C. §407, and VA benefits are protected under 38 U.S.C. §5301, no matter what you disclose at the exam. One practical caveat: those protections stop the creditor from keeping the money, but if it is sitting in a bank account the account can still be frozen while you prove the funds came from an exempt source. Keeping benefits in an account you don’t mix with other money makes that much easier to prove.
What if I show up and honestly have nothing — what happens?
You answer the questions truthfully, the creditor learns there’s nothing collectible right now, and the hearing ends. Showing up with an honest “I don’t have it” is not contempt of court. What can still create a problem is answering incompletely or evasively — that is a separate risk from simply having nothing. Not showing up at all is what creates the legal risk; the exam itself is rarely the dangerous part.
I filed bankruptcy — does that stop the debtor’s exam?
For most people, yes — immediately. The automatic stay under 11 U.S.C. §362 takes effect the moment you file, not weeks later, and it halts the debtor’s exam along with every other collection action against you, including garnishment and further court proceedings on this judgment. The one group that must not assume this: if you had a bankruptcy case dismissed within the past year, §362(c)(3) terminates that stay on the 30th day after you file unless the court extends it, and with two or more dismissals in that year §362(c)(4) can mean no stay arises at all. If that’s your history, file the motion — and still show up for the exam until you know the stay is in place.
What’s different about a California debtor’s exam versus other states?
California requires the order be personally served at least 30 days before your hearing under CCP §708.110, and a bench warrant is only on the table if that service was done by a sheriff, marshal, a person the court specially appointed, or a registered process server. Other states, like New York’s “supplementary proceedings” or Florida’s “proceedings supplementary,” use different names, different notice rules, and different enforcement mechanics — check your own state court’s self-help resources rather than assuming California’s rules apply to you.
Can I just ignore the notice if I think the original judgment was wrong?
No. Disputing the underlying judgment and disobeying a separate, valid court order to appear are two different legal problems. If you believe the original judgment was entered in error — especially a default judgment you never got to contest — talk to an attorney about a motion to vacate it, but still show up (or formally ask to reschedule) for the exam in the meantime.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A debtor’s exam is stressful, but showing up is almost always the safer move than skipping it. Take my 2-minute quiz to see if bankruptcy’s automatic stay would end this permanently, and know what income stays protected before you walk in. The longer you avoid the notice, the more the court’s attention shifts from your money to your absence.
The Bottom Line
You are not a criminal for owing money, and this hearing exists because the civil court system has no other way to find out what you actually have — not because you did something wrong. The law built in real protections here: advance written notice, income that stays exempt no matter what you disclose (even if a bank account holding it can be frozen while you prove the source), and a bankruptcy filing that, for most people, can end the whole thing before you ever sit down. The people who come out of this fine are the ones who show up — not the ones who disappear. If someone you know just got one of these notices and is panicking, send them this page. Knowing the difference between “answer questions” and “go to jail over the debt” might be exactly what keeps them out of real trouble. Take the Find Your Path quiz for your next step, and see what to do if collectors won’t stop even though you’re judgment-proof.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 10): Your phone company is supposed to know who’s handing it those scam calls. Some of them don’t bother.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



