

Quick Answer: The $124 trillion “great wealth transfer” is real, but more than half of it moves between households that are already wealthy — about 2% of American families. What almost nobody says out loud is that the advice those families are paying for is mostly free. Their advisors tell them the money is the least important part, and that what actually survives across generations is communication, deliberate teaching, and a long time horizon. None of that is gated behind a trust fund. You can start using it this week.
Part of a series: This post is part of my Should You Invest or Pay Off Debt? research hub — where I cover the math, psychology, and scams around investing while in debt.
Expert Context: I ran a credit counseling organization, and I have spent over 30 years reading what the debt industry mails to people at the bottom of the economy — the consolidation pitches, the settlement ads, the “one simple call” letters. This week I read the opposite mail: the client newsletter a trust department sends to wealthy families. Same country, same month, two completely different educations. I have never seen the gap laid out so plainly, and the part that stopped me was that the expensive advice turned out to be free.
A trust department’s August client newsletter crossed my desk, written for families with enough money to need an estate plan. It is a genuinely good document. It is also a document that will never be mailed to the people who read my site — and after reading it twice, I think that is the real story, not the $124 trillion headline.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 11): You drive to the dealership to pick up the car. There is no car. There was never a car.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
The Newsletter That Does Not Come to Your Mailbox
You have probably seen the headline. Cerulli Associates projects $124 trillion will transfer through 2048 — roughly $105 trillion to heirs and $18 trillion to charity. It gets written up as a coming windfall, as though a tide is about to lift everyone.
Read one line further into the same research and the picture changes. More than half of that total — about $62 trillion — comes from high-net-worth and ultra-high-net-worth households, and those households are 2% of all American families. The great wealth transfer is, for the most part, wealthy families handing money to their own children.
The Federal Reserve’s own analysis of intergenerational transfers puts numbers on the shape of it. The top 10% of households receive about 56% of transferred wealth. The bottom half receives about 8%. And the individual amounts are not what the headline implies: about 55% of all inheritances are under $50,000, while the 2% that exceed $1 million carry roughly 40% of every dollar transferred.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
That is the K-shaped economy expressed as inheritance. Two families, same country, and the tide only reaches one of them.
Key Terms Defined
Beneficiary designation: The person you name directly on a retirement account, life insurance policy, or annuity. It transfers the asset the moment you die, outside of probate — and it overrides your will. See the IRS explanation of retirement plan beneficiaries.
Payable-on-death (POD) / transfer-on-death (TOD): A form you file with a bank or brokerage naming who receives the account when you die. Costs nothing. Skips probate entirely.
Intestate: Dying without a will. The state then applies its own formula to decide who gets what — a formula that may not resemble your wishes at all.
Family governance: The wealth industry’s term for a family deliberately deciding, out loud and in writing, what its money is for. In practice it means scheduled conversations. It is the most expensive-sounding free thing in personal finance.
The Scare Story Wealthy Families Are Sold
Almost every document like this one opens with the same statistic, and this newsletter was no exception: fewer than 10% of family fortunes survive past the third generation. “Shirtsleeves to shirtsleeves in three generations.” The Vanderbilts get named. Someone quotes the line about inherited wealth being a handicap to happiness.
The Claim: Family wealth reliably self-destructs — 70% of wealthy families lose it by the second generation and 90% by the third — so affluent families need extensive professional structuring to beat the curse.
The Reality: That figure traces to a single consulting-firm study of roughly 3,200 families, and family-wealth researchers have publicly questioned its methodology. Meanwhile the peer-reviewed research on how long advantage actually lasts points the other way — hard. Economists Guglielmo Barone and Sauro Mocetti matched the tax records of Florence, Italy in 1427 to the residents of Florence in 2011 using surnames, and found that the families at the top six centuries ago are still, on average, at the top today. That is roughly twenty generations. Their paper, “Intergenerational Mobility in the Very Long Run: Florence 1427–2011,” was published in The Review of Economic Studies and began as a Bank of Italy working paper.
Both things can be true at once, and the way they fit together is the whole point. An individual pile of money really does get divided among heirs and spent down. But the position — the expectations, the assumptions, the default habits around money — is astonishingly durable. Six hundred years durable.
Which tells you the thing that persists was never the money. It was the practices. And practices do not have a minimum balance.
Why a Raise Disappears
Here is the mechanism nobody explains to people at the bottom of the K, and it was described in 1899.
“In any community where conspicuous consumption is an element of the scheme of life, an increase in an individual’s ability to pay is likely to take the form of an expenditure for some accredited line of conspicuous consumption… The need of conspicuous waste, therefore, stands ready to absorb any increase in the community’s industrial efficiency or output of goods, after the most elementary physical wants have been provided for.”
— Thorstein Veblen, The Theory of the Leisure Class (1899)
Read that again with your own raise in mind. Veblen’s argument is that in a culture organized around visible spending, extra money does not become an asset by default. It becomes a nicer car. The increase gets absorbed before it can turn into anything that compounds.
This is not a character flaw and I am not going to insult anyone by calling it one. It is the water everyone swims in — and the marketing is not evenly distributed. When income rises in a household at the top of the K, an advisor calls and asks where to put it. When income rises in a household at the bottom, a lender calls and asks what to buy with it. Same event, opposite instruction.
The wealthy family’s real advantage is not a secret investment. It is that somebody intercepts the raise before it evaporates, and that somebody is usually a system, not a person with unusual willpower.
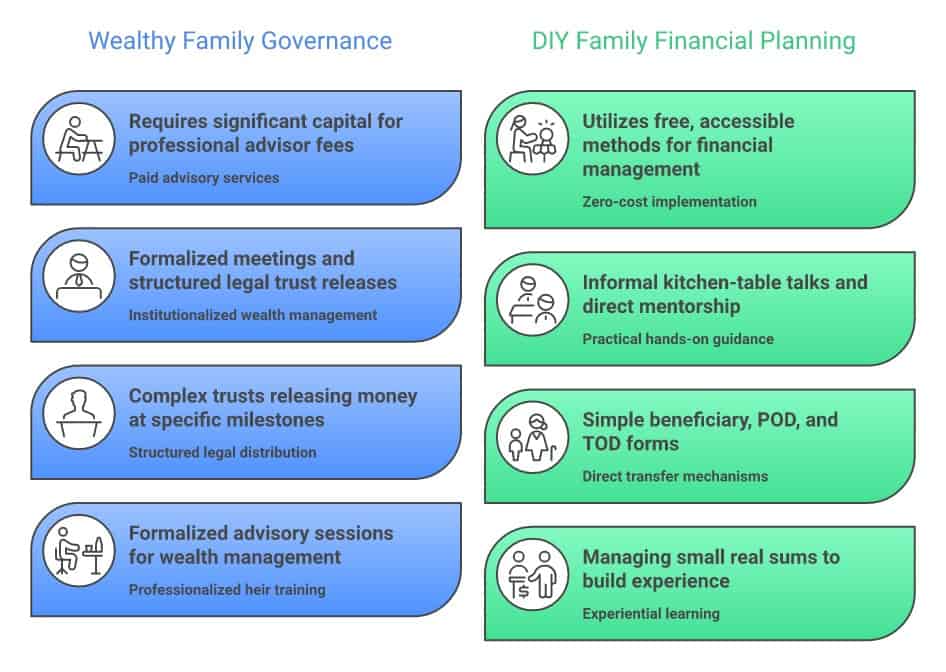
The Playbook — and the Free Version of Every Line in It
Here is what genuinely surprised me. The newsletter is emphatic that the legal machinery is the least important part. Its own words: trusts, LLCs, charitable structures and tax strategies “are simply vehicles,” and the most valuable family asset “is not financial capital; it is human capital.”
So I went through its recommendations one by one and asked what each one costs somebody who is not wealthy. The answer, almost every time, was nothing.
What Wealthy Families Are Told to Do
- Hold family meetings with advisors, bringing children in as observers first
- Give heirs practical experience managing smaller amounts of money before the big transfer
- Structure trusts to release money at real milestones — education, a first home, starting a business, emergencies
- Match children’s retirement savings and charitable giving to reinforce the behavior
- Write a “letter of intent” explaining what the money is for and what you hope it does
- Talk openly about money, because silence creates secrecy and heirs invent their own story
The Version Available to You This Week
- A recurring family money conversation at your own kitchen table. Free.
- Let a teenager manage a real, small amount and make real, small mistakes. Free.
- Beneficiary designations, POD and TOD forms, and a basic will — the milestone logic, minus the trust. Free to a few hundred dollars.
- Your employer’s 401(k) match is the identical mechanic — someone matching you to reinforce the habit. Free money you may already be leaving behind.
- A letter to your kids, written tonight, in your own handwriting. Free.
- Saying the actual numbers out loud to your family instead of protecting them from the truth. Free, and the hardest one on the list.
The single highest-leverage item there is the one people find hardest to believe: your beneficiary designations override your will. If your 401(k) still names an ex-spouse and your will names your children, the ex-spouse receives the account. A will does not fix it. Updating that form takes about ten minutes, costs nothing, and moves more money than most people’s entire estate plan.
If you have never checked, check this week. I would rather you close this page and go do that than finish the article.
The Generational Asset You May Already Own
There is one more thing, and it is the piece of this that belongs on my site rather than in a trust department’s newsletter.
For most working families, the largest asset that will ever pass to their children is not a house and it is certainly not a brokerage account. It is a retirement account. And retirement accounts hold a property almost nothing else does: under 11 U.S.C. § 522, they are protected in bankruptcy. Employer plans like a 401(k) are generally shielded outright, and IRAs are protected up to a cap that is adjusted periodically — currently just over $1.7 million.
Sit with what that means. The single most durable, most transferable asset a normal family can build is also the one asset that survives a total financial collapse. It cannot be taken by a credit card company. It cannot be taken by a hospital. It does not disappear if the worst happens.
Which is why I get genuinely angry when I see people cash out a 401(k) to pay unsecured debt they could have discharged. They are converting the one protected, generation-spanning asset they own into a temporary reprieve on a debt the law would have wiped out. I have watched it happen hundreds of times, and it is the most expensive mistake in consumer finance. If that is the decision in front of you, please read what the research actually says about bankruptcy outcomes before you sign anything, and take the Find Your Path quiz to see your options laid side by side.
And if you are not in crisis — if you are simply somebody whose income finally has a little room in it — then the boring, unglamorous way to start investing is the same one the wealthy family’s advisor recommends. They just have someone whose job is to make sure it happens.
Key Takeaways
- The $124 trillion wealth transfer is real, but more than half of it moves within the wealthiest 2% of households — and 55% of all inheritances are under $50,000
- The “90% lose it by the third generation” statistic comes from one consulting study and has been questioned; peer-reviewed research on Florence 1427–2011 found family advantage persisting for roughly twenty generations
- What persists across generations is practices and expectations, not a pile of money — and practices have no minimum balance
- The wealth industry’s own advice says the legal structures are “simply vehicles” and human capital is the real asset — nearly every recommendation has a free version
- Beneficiary designations override your will, take ten minutes to update, and cost nothing
- Retirement accounts are protected in bankruptcy under 11 U.S.C. § 522, making them the one generational asset that survives a financial collapse — never cash one out to pay dischargeable debt
The Bottom Line
If you have ever felt that there is a conversation happening about money that you were not invited to, you were right — and this week I read the invitation. The strange part is what was inside it. The families who are best at keeping wealth are not being told about a secret investment; they are being told to talk to their children, to teach them with small amounts first, to write down what the money is for, and to think in decades instead of months. Every one of those is free, and not one of them requires you to already be rich. You are not behind because you lack a trust. You are behind because nobody handed you the instructions, and now somebody has. Start with the ten-minute one: go look at who is named on your retirement account, and make it the right person.
One more thing, and I mean it kindly: this is my input, not my instruction. I do not know your family, your numbers, or what this year has cost you. Take what fits, leave what does not, and if you are in the middle of a crisis right now, stabilize first — the long game can wait a few months, and it will still be there.
If this helped, please forward it to one person who needs to read it. The people who most need to know the instructions exist are exactly the people nobody mails them to.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Frequently Asked Questions
Is the $124 trillion great wealth transfer going to help ordinary families?
Mostly no. Cerulli Associates projects $124 trillion transferring through 2048, but more than half of that total comes from high-net-worth and ultra-high-net-worth households, which are about 2% of all American families. Federal Reserve analysis shows the top 10% of households receive roughly 56% of transferred wealth while the bottom half receives about 8%, and around 55% of all inheritances are under $50,000. The headline number is real; the distribution is extremely concentrated.
Do beneficiary designations really override my will?
Yes, and this surprises almost everyone. Retirement accounts, life insurance, annuities, and payable-on-death or transfer-on-death accounts pass directly to whoever is named on the account form. Your will only governs assets that do not have a named beneficiary or surviving joint owner. If your 401(k) names an ex-spouse and your will names your children, the ex-spouse gets the account. Updating the form takes about ten minutes and costs nothing.
Is it true that 90% of wealthy families lose their money by the third generation?
It is the most-quoted statistic in the wealth-management industry, but it traces to a single consulting-firm study of roughly 3,200 families, and family-wealth researchers have publicly questioned the methodology. Peer-reviewed economic research points the other direction on how durable advantage is: a study published in The Review of Economic Studies matched Florence, Italy’s 1427 tax records to its 2011 residents and found the wealthiest surnames were still the wealthiest roughly twenty generations later. Individual fortunes get divided and spent; the position tends to persist.
Can I build generational wealth if I still have debt?
Some of it, yes — and some of it should wait. The free habits in this article cost nothing and can start today no matter what you owe: the family money conversation, the letter to your kids, updating your beneficiary forms. But if you are carrying debt you genuinely cannot pay, dealing with that comes first, because unpayable debt is precisely what prevents anything from compounding. What you should not do is drain a protected retirement account to pay unsecured debt that could be discharged.
Are my retirement accounts safe if I file bankruptcy?
Generally yes. Under 11 U.S.C. § 522, employer-sponsored plans such as 401(k)s are broadly protected, and IRAs are protected up to a cap that is adjusted periodically and currently sits just over $1.7 million. This is why cashing out retirement savings to pay dischargeable debt is such a costly mistake — you are spending a protected asset to settle a debt the law may have eliminated anyway. Talk to a bankruptcy attorney about your specific accounts and state before making that move.
What is the single first thing I should do after reading this?
Log in to your 401(k), IRA, and life insurance accounts and look at who is named as beneficiary. Most people have not looked since the day they opened the account, and life has happened since — marriages, divorces, births, deaths. It is free, it takes ten minutes, and it directs more money than almost anything else you will do this year.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



