

Written by Steve Rhode, consumer debt expert since 1994 • Last updated August 12, 2026
Quick Answer: A private investor bought either the debt on your unpaid property taxes (a tax lien) or your home itself (a tax deed) at a county tax sale. Under the U.S. Supreme Court’s Tyler v. Hennepin County ruling, the county and the investor can only recover what you actually owe — any leftover value is still legally yours. Most states give you a redemption period after the sale, from about 180 days to several years, to pay it off and keep your home — but a few states, California among them, only let you redeem before the sale closes and give you no right to get the property back afterward, so find out today which category your state falls into. The deadline is real. Don’t wait to find out how much time is left.
What Just Happened to Your Property
When property taxes go unpaid long enough, the county doesn’t wait for you to catch up — it sells the debt (or the property itself) to recover the money now. In roughly half the states, that means a tax lien sale: an investor pays your back taxes to the county and gets a certificate entitling them to collect that amount from you, plus interest that can run anywhere from a modest annual rate up to the state’s legal cap. You still own the home. You now owe the investor instead of the county. In the other states, it’s a tax deed sale: the county sells the property itself at auction, and the winning bidder gets a deed — sometimes with a short post-sale window for you to redeem it, sometimes with none.
This overwhelmingly hits people who own their home free and clear. If you have a mortgage, your lender almost always collects a slice of your payment every month for an escrow account and pays the tax bill for you automatically — the Consumer Financial Protection Bureau explains how that works here. Once the mortgage is paid off, that safety net disappears, and it’s on you to track and pay the bill directly, once or twice a year, for the rest of the time you own the home. A hospital stay, a stroke, a move into assisted living, a family member managing an aging parent’s mail — any of it can mean a tax bill sits unopened while the delinquency quietly grows.
The Mistake You’re About to Make: Assuming the notice is junk mail because it looks like the thousand “we buy houses for cash” postcards already in your recycling — or the opposite mistake, panicking and signing whatever a stranger who knocks on your door hands you. Investors and “rescue” services sometimes approach homeowners in this exact position offering a fast cash buyout or a deed transfer that looks like help. If you still have a redemption right, or if a sale already happened and there’s leftover equity above what you owed, signing something before you understand your actual deadline and your actual rights can cost you tens of thousands of dollars you didn’t have to lose. Read your options below first.
Your Options Right Now
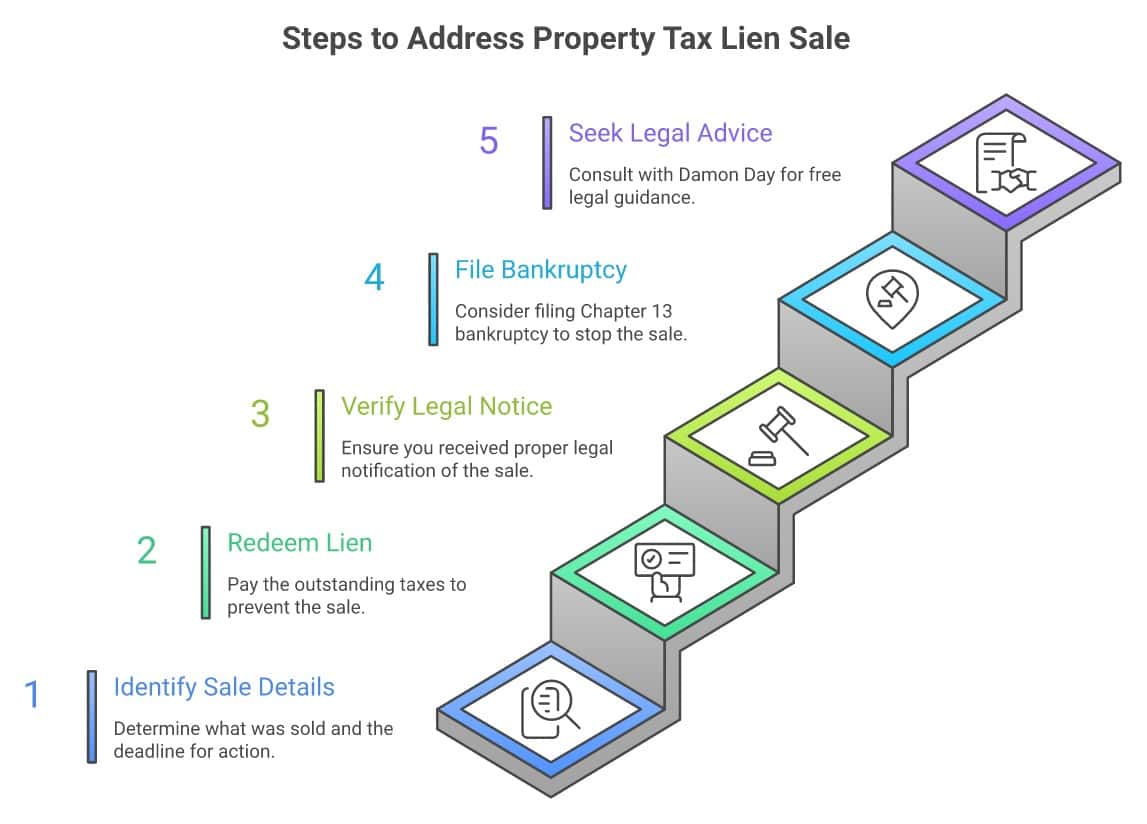
What to Do in the Next 48 Hours
- Find out exactly what was sold, and your deadline. Call your county tax collector or treasurer’s office and ask: was this a lien sale or a deed sale, what is my redemption period, and what is the exact date it ends. Redemption windows run from about 180 days in some states to 2-3 years or more in others — you cannot guess this, you have to ask.
- Redeem it if you can, before the deadline — not after. Who you actually pay depends on which kind of sale happened: in lien-certificate states you generally pay the county or tax collector, who passes the money to the investor, and in tax deed states with a redemption right — Texas and Georgia among them — you typically pay the purchaser directly. Confirm which applies before you send a dollar to anyone, because paying the wrong party does not stop the clock. Call the county treasurer and ask this directly: “Exactly who must receive my payment — the county, or the purchaser?” — then get the named payee and the exact payoff figure in writing before you send anything. Waiting even one day past the statutory deadline can end your right to redeem entirely.
- Check whether you actually got proper legal notice. The Supreme Court held in Jones v. Flowers that if a mailed notice comes back undelivered, the government has to take additional reasonable steps before it can sell your home — a returned certified letter isn’t enough. If notice was sent to an old address, to a deceased relative, or was returned unclaimed and the county did nothing further, you may have grounds to challenge the sale.
- If you can’t pay it off outright, file Chapter 13 bankruptcy before your redemption deadline — not before a “sale” that may already be behind you. The automatic stay stops the tax foreclosure the moment you file — not weeks later — but only if you still have a deadline left to protect. Federal law (11 U.S.C. § 108(b)) can extend a state deadline that hasn’t yet expired when you file, but it cannot revive one that has already run, so if your redemption date has passed, bankruptcy generally cannot bring it back. Ask the county which date actually governs your case — the redemption deadline or a final confirmation sale, whichever one your state actually has — and if you aren’t certain, call a bankruptcy attorney today rather than after you’ve confirmed it yourself. Chapter 13 lets you repay the tax debt over 3 to 5 years through a court-supervised plan instead of all at once. Take the 2-minute bankruptcy quiz to see if the math favors this, and use NACBA to find a bankruptcy attorney in your state.
- Talk to Damon Day, a certified consumer debt coach, for free before you decide anything. Talk to Damon Day for free — he’s not an attorney, but he can help you triage the numbers and figure out whether redemption, bankruptcy, or a surplus-funds claim makes sense for your situation before you spend money on legal fees you may not need yet.
How to Actually Stop It — Your 4 Paths
- File Chapter 13 bankruptcy before the redemption period runs out. The automatic stay under 11 U.S.C. § 362 halts a pending tax foreclosure immediately, and Section 1322(c)(1) lets you cure the arrears through your plan — but only if you file before your redemption deadline or a final confirmation sale, whichever one your state actually has, so ask the county which deadline governs your case. If your redemption deadline has already passed, 11 U.S.C. § 108(b) generally cannot revive it — it only extends a deadline that hasn’t yet run as of the day you file. In some states, if no tax deed has actually been issued yet, a Chapter 13 plan may still be able to reach the property — ask a bankruptcy attorney whether your state is one of them. Tax liens generally survive bankruptcy and still have to be paid in full through the plan, but you get years instead of days to do it.
- Redeem before the deadline — but confirm who to pay first. This is the cleanest fix if you can raise the money — pay the delinquent taxes, interest, penalties, and costs before your state’s deadline and the sale is voided outright. In lien-certificate states that payment goes to the county, and in deed states with a redemption right it often goes straight to the purchaser, so confirm the correct payee with the county treasurer before you send anything. Some family members or lenders will advance this money short-term against the home’s equity if the numbers make sense.
- Challenge a defective notice. If you can show the county didn’t take the additional reasonable steps required under Jones v. Flowers after a mailed notice came back undelivered, an attorney may be able to get the sale set aside even after the redemption period has technically closed. This is fact-specific — talk to a real estate or consumer attorney through NACA.
- What WON’T work: ignoring it, or a debt settlement/consolidation company. This isn’t credit card debt — a settlement company can’t negotiate away a tax lien or stop a foreclosure clock, and consolidation loans don’t move fast enough to beat a redemption deadline. The property is on a legal timeline that only redemption, a court order, or bankruptcy’s automatic stay can actually change.
What You Need to Know About Your Rights
The core protection comes from the Fifth Amendment’s Takings Clause. In Tyler v. Hennepin County (598 U.S. 631, 2023), the Supreme Court ruled unanimously that Hennepin County, Minnesota violated the Constitution when it sold a 94-year-old woman’s condo for $40,000 over a $15,000 tax debt and kept the entire $25,000 difference. The Court held that a government “may not extract more from a taxpayer than she owes” — the excess belongs to the former owner, not the county or the investor who bought the debt.
| Jurisdiction | How Sales Work | Notes |
|---|---|---|
| Federal baseline (all states) | Surplus equity above the tax debt belongs to the former owner, but states may require you to file a claim by a set deadline to actually collect it | Tyler v. Hennepin County, 2023 — the right applies nationwide, but recovering the money is not automatic |
| Texas | Tax deed sale; 2-year redemption for homestead/agricultural property, 180 days for other property | Redemption premium of 25% (year one) or 50% (year two) on top of what the buyer paid — Tax Code Chapter 34, Subchapter B |
| California | No lien-certificate sales; property becomes eligible for sale after 5 years of tax delinquency (3 years for nonresidential commercial) — Rev. & Tax. Code § 3691 | No post-sale redemption, but a 1-year window to claim excess proceeds after the sale — Rev. & Tax. Code § 4675 |
| Illinois | Reformed in 2026 to a tax deed auction model; surplus equity returned by the county treasurer | Public Act 104-0553, signed July 10, 2026 — reported to phase out private tax-lien buying in Cook County by 2030 — Illinois Public Act 104-0553, Illinois General Assembly |
If you’re elderly, disabled, or on a fixed income — you’re statistically the most likely group to lose a home this way, precisely because you’re more likely to own it free and clear with no mortgage escrow catching a missed bill. A Pacific Legal Foundation analysis of Minnesota tax sales found that between 2014 and 2020, homeowners who lost family homes this way lost an average of about $207,000 in equity — roughly 92% of the home’s value — against tax debts that averaged only around $17,000, before Minnesota changed its law. Ask about a senior property tax deferral or exemption program in your county before you’re ever behind; many exist and go unused simply because no one asks.
If you believe the notice you received was legally deficient, or a company is charging you an upfront or excessive fee to “help” you claim money that is already legally yours — the New Jersey Division of Consumer Affairs has documented this exact scam pattern around sale surplus funds, with fees running as high as 75% of money you can typically claim yourself for under $100 — file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990. I know what it feels like to watch a deadline you didn’t fully understand turn into a problem you can’t undo. When I ran a credit counseling nonprofit, the people who lost the most weren’t the ones with the biggest debts — they were the ones who sat on a notice for three months because it felt too overwhelming to open. A property tax lien sale is math wrapped in a deadline, not a moral failing. The people who called someone — the county, an attorney, Damon Day, anyone — within the first few weeks kept their equity or their home far more often than the people who waited to see if it would sort itself out. It doesn’t sort itself out. Make the call this week.
Frequently Asked Questions
My property tax lien was sold — can I still get my house back?
In most cases, yes, if you’re still inside your state’s redemption period. You (or sometimes an heir or lienholder) pay off the back taxes, interest, penalties, and costs, and the sale is voided — but who you actually pay depends on your state: the county in lien-certificate states, or the purchaser directly in deed states like Texas and Georgia. Call your county tax collector immediately to confirm both your exact deadline and the correct payee — neither one is the same in every state.
How long do I have to redeem my property after a tax lien sale?
It depends entirely on your state — anywhere from about 180 days to 3 years or more, and sometimes longer for a homestead than for other property — though a few states, California among them, give no post-sale redemption at all and only let you redeem before the sale closes. Texas gives homestead owners 2 years and non-homestead owners 180 days under Tax Code § 34.21; other states differ significantly. Confirm your exact date directly with the county — don’t rely on a general estimate for a deadline this important.
I filed bankruptcy — how fast does it stop a tax lien foreclosure?
The automatic stay under 11 U.S.C. § 362 takes effect the moment you file, not weeks later, and it stops a pending tax foreclosure sale immediately — but only if you still have a deadline left to stop. You generally have to file before your redemption deadline or a final confirmation sale, whichever one your state actually has, so ask the county which deadline governs your case. If that date has already passed, federal law (11 U.S.C. § 108(b)) generally can’t revive it — it only extends a deadline that hasn’t yet expired when you file, and Johnson v. First National Bank of Montevideo, 719 F.2d 270 (8th Cir. 1983), is the leading case on just how little runway that buys you. Chapter 13 then lets you repay the tax debt over 3 to 5 years once you’re inside that window.
Do I get any money back if my house sold for more than I owed in taxes?
Yes — this is the law nationwide now. Under Tyler v. Hennepin County (2023), any surplus value above your actual tax debt legally belongs to you, not the county or the investor. Most counties require you to file a claim within a set window (often 1 to 2 years) rather than mailing it to you automatically, so you have to ask.
What if I never actually got a notice that my taxes were delinquent?
You may have a strong legal argument. In Jones v. Flowers, the Supreme Court held that if mailed notice comes back undelivered, the government must take additional reasonable steps — like a second mailing or posting notice at the property — before it can sell your home. If that didn’t happen, talk to a consumer or real estate attorney through NACA about challenging the sale.
Can a company legally charge me a fee to help me claim my surplus funds?
Be careful here. Filing a surplus or excess-proceeds claim yourself is usually simple and cheap — often under $100 in filing costs, with no attorney required. State consumer protection agencies, including New Jersey’s, have documented “recovery” companies charging up to 75% of money that was already legally yours. If someone contacts you first, be skeptical; if you hire help, understand exactly what percentage you’re paying before you sign anything.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
What’s the difference between a tax lien sale and a tax deed sale?
In a tax lien sale, an investor buys the debt, not the house — you keep ownership and owe the investor instead of the county, with a chance to pay it off (redeem) before the investor can eventually foreclose. In a tax deed sale, the county sells the property itself, and the buyer gets the deed directly, sometimes with a short redemption window afterward and sometimes with none. Ask your county which kind of sale happened to you — the deadlines and your options are different for each.
Does bankruptcy erase the tax lien itself, or just buy me time?
It buys you time and a repayment structure — a valid tax lien generally survives bankruptcy and still has to be paid in full, typically through your Chapter 13 plan. What bankruptcy does is stop the immediate foreclosure clock and let you pay it over years instead of all at once. See when tax debt actually can be wiped out in bankruptcy for the underlying income-tax rules, which are different from a property tax lien.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day, a certified consumer debt coach (not an attorney), for free about the practical side of your situation.
Key Takeaway: A tax lien or tax deed sale is serious, but it runs on a fixed legal clock — not an instant loss. Find your exact redemption deadline today, and if you can’t pay it off outright, take the 2-minute bankruptcy quiz to see if Chapter 13’s automatic stay can buy you the years you need. The longer you wait to make a call, the fewer real options you have left.
The Bottom Line
You are not careless or foolish for missing a tax bill — plenty of people who own their homes outright, especially older homeowners and people managing a health crisis or a family emergency, end up here through no real fault of their own. The law now recognizes that: since 2023, no government or investor is allowed to walk away with more than you actually owed. The homeowners who came out of this best were the ones who called the county, an attorney, or Damon Day the same week they realized what happened — not the ones who waited to see if it would go away. If someone you know owns their home free and clear and mentions a strange notice from the county, send them this page — it might be the thing that saves their equity. See the Find Your Path quiz for a full picture of your options.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



