

Quick Answer: The $120,334,500 homebuyer commission class action settlement (Tuccori, et al. v. At World Properties LLC, et al., No. 1:24-cv-00150, U.S. District Court for the Northern District of Illinois) is now accepting claims. If you purchased a home listed on a Multiple Listing Service anywhere in the United States and a commission was paid to any brokerage in that transaction during the applicable class period, you may qualify for a payment. Filing is free, requires only a recorded property deed, and the deadline is October 27, 2026 — knowing how to file a claim correctly before a deadline matters just as much as knowing you qualify. File directly at HomebuyerSettlement.com, the official court-approved administrator site, not through a third-party service.
Expert Context: I’ve been helping people with debt since 1994, and writing about it here since I launched GetOutOfDebt.org in 2008. I’ve watched which settlements actually put money in people’s pockets and which ones get eaten alive by fees, middlemen, or paperwork nobody explains clearly. This one is real, it’s free to file, and there’s a specific way people are already getting steered wrong on it.
A $120 million class action settlement just opened its claims window, and if you bought a home that was listed on an MLS and a commission was paid on the sale, you may be entitled to a piece of it — but the way this story is spreading online is exactly the kind of thing that makes me nervous.
What You Need to Know
The defendants are the National Association of Realtors and a group of residential real estate brokerages. The official notice puts it this way: “There are 25 residential real estate companies named in the Litigation that have agreed to the Settlement.” It does not name them in the notice itself, and points you to the FAQ on the settlement site for the list. Together they agreed to pay $120,334,500 into a global settlement fund — NAR’s share is $52.25 million, paid in over a multi-year period, according to its own announcement — a fund to resolve claims that they engaged in anticompetitive conduct that plaintiffs allege kept real estate broker commissions artificially high and raised prices for homebuyers nationwide. Those are allegations, not findings. The case is Tuccori, et al. v. At World Properties LLC, et al., filed in the U.S. District Court for the Northern District of Illinois.
Claiming money you are owed is one good day. What you do over the following year is what actually changes your position.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
The defendants have not admitted any wrongdoing. As the official class notice puts it: “The Defendants deny having violated the law, and the Court has not decided who is right or wrong.” That matters — this is a negotiated settlement to avoid the cost and risk of a trial, not a verdict.
Key Terms Defined
MLS (Multiple Listing Service): The database real estate brokers use to list homes for sale and share information with other brokers — nearly every home sold through an agent passes through one.
Class period: The window of time during which a purchase must have happened for you to qualify. In this settlement, the class period varies by state and by which defendant brokerage was involved — the official notice says only that “the date ranges for the Class Periods vary by state” and does not publish a single set of dates. Secondary sites list specific ranges; I am not repeating them here, because if one is wrong it either talks an eligible buyer out of filing or sends an ineligible one chasing. There is no date range that applies to everyone — check your own purchase against the settlement website, which is the only place that answers it for your transaction.
Settlement administrator: The independent, court-approved company responsible for processing claims and issuing payments. For this case, that’s the entity behind HomebuyerSettlement.com — not NAR, not a brokerage, and not any of the third-party sites currently writing about this case.
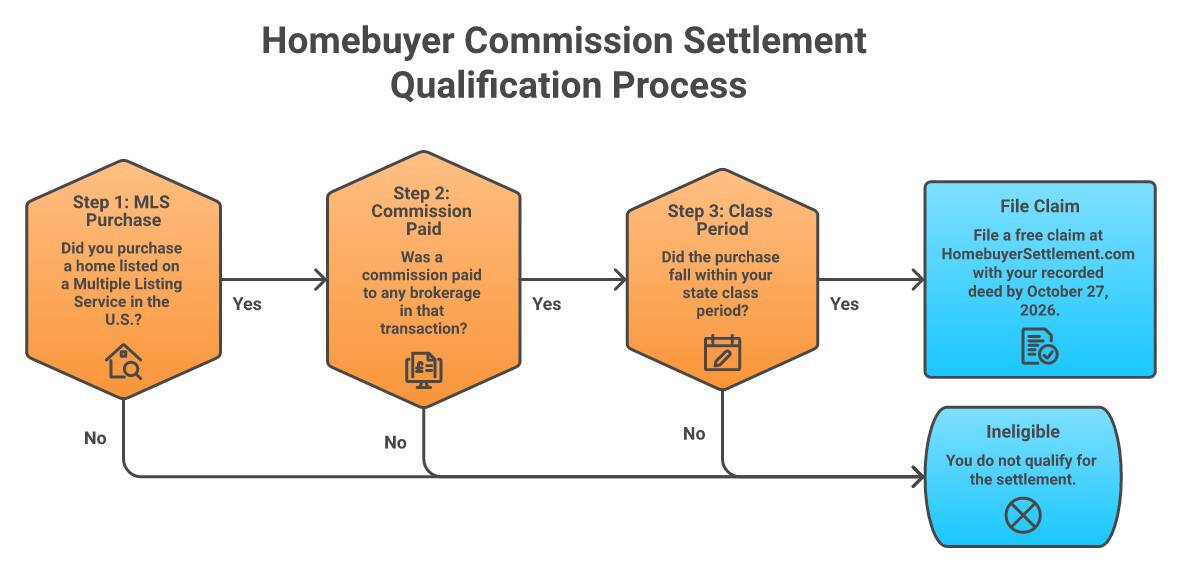
To actually get paid, you need a recorded property deed for the home you purchased — that’s the proof of purchase the administrator uses to verify your claim. Payments are not flat. The amount you receive depends on the number of valid claims submitted, how many properties you purchased, and how much commission was paid on those transactions — the administrator has said people who paid the highest commissions will receive the largest payments. You do not have to document the commission yourself; the deed is what you provide, and the administrator calculates the rest. Nobody can tell you your exact number in advance, and I wouldn’t trust anyone who claims they can.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Why You Need to Know It
Here’s the part that actually worries me more than the settlement itself. Stories like this one get picked up fast by third-party claim-aggregator sites — I found this one being republished by services like Claim Depot and Refund Advocacy, among others. To be clear and fair: I did not find anything on either site stating they charge a fee to help you file, and I’m not accusing either one of taking a cut. What I am telling you, from tracking settlement and debt-relief claims for a very long time, is the general rule that protects you regardless of which site you land on first: a class-action claim always has one official, free filing path — the court-approved administrator site named in the actual settlement notice. For this case, that’s HomebuyerSettlement.com. Anyone who wants to charge you a fee, a percentage, or “processing costs” to file a claim you could file yourself in a few minutes is selling you something you don’t need to buy.
I’ve warned people before about paying someone to file a claim they could file free themselves, and I’ve seen this exact pattern play out for years in the debt relief and settlement world — a real, legitimate opportunity gets discovered, and a layer of services spring up between the person and their money. Sometimes those services are harmless (a news site just reporting on the case, which is fine — that’s what I’m doing right now). Sometimes they take a cut of money that was never theirs to take a cut of. The only way to know for sure which one you’re looking at is to read the fine print before you click “file,” and when in doubt, go straight to the source named in the court notice.
The Claim: This settlement is what made real estate commissions negotiable and required them to be disclosed in writing before you sign with an agent.
The Reality: Those practice changes — a written buyer-agent agreement before you tour a home, and a specific disclosure of what your agent will be paid — came out of an earlier case, the Sitzer/Burnett settlement, and took effect industry-wide on August 17, 2024 (see NAR’s own explanation of that settlement). This new $120 million settlement doesn’t create new rules — NAR’s own press release on this settlement says the terms “require continued compliance with the practice changes as part of the Sitzer/Burnett settlement, but do not require any additional practice changes” (NAR press release). In plain English: this settlement pays homebuyers for the old conduct and keeps the existing reforms in place. It didn’t invent them.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Things to Consider
A few second-order effects worth thinking through before you do anything:
- The check is probably going to be modest, not life-changing. With payments split among what could be millions of claimants and dependent on how much commission you actually paid, neither the notice nor the administrator publishes an estimated per-person payment, and I am not going to invent one. What I will say from watching these for years: in settlements of this shape the individual checks are usually modest rather than life-changing, and attorneys’ fees and administration costs come out of the fund before anyone is paid — so the amount actually distributed is less than the $120,334,500 headline. That doesn’t mean skip it — small settlement checks are still worth claiming, as I’ve covered before. It means “file it and forget about it” is honest advice, not a brush-off.
- Filing by October 27 does not mean money in October. The court holds a final approval hearing on November 2, 2026, and nothing is paid out before a settlement is finally approved. If anyone appeals, payment can slide by many months more. That is normal and it is not a sign anything went wrong — but it is exactly the gap that makes people think they were scammed, and then makes them vulnerable to someone offering to “track down” their money for a fee. File it, note the date, and forget it.
- Opting out (by September 17, 2026) preserves your right to sue individually — and for almost everyone, that’s the wrong move. Opting out means giving up your share of the $120.3 million fund in exchange for the theoretical right to bring your own lawsuit against the settling defendants. Unless you have a specific, unusually large claim and a lawyer already advising you to do this, there’s very little upside to walking away from a guaranteed payment for a lawsuit you’d have to fund and win yourself.
- If you sold — rather than bought — a home, this settlement isn’t for you. The class is defined around purchasers. Don’t let the headline make you think every real estate transaction you were part of qualifies.
What to Think About Doing
- Check your eligibility and file directly at HomebuyerSettlement.com. You’ll need your recorded property deed. Do this before October 27, 2026. The official notice states the deadline as postmarked by that date; if you file online, submit it by then and keep your confirmation.
- Never pay anyone a fee to file this claim. If a site asks for a percentage of your payout, a “processing fee,” or your bank information before you’ve even confirmed eligibility on the official site, close the tab.
- If you’re buying a home in the next couple of years, get the buyer-agent commission line item in writing before you sign anything — and negotiate it. That right exists today because of the earlier Sitzer/Burnett practice changes, not this new settlement, but it’s real and it’s yours to use. Ask what the agent is being paid and how that number was set — I’ve also covered steering homebuyers toward deals that serve the agent more than the buyer in the mortgage space, which runs on the same commission-incentive logic.
- If you’re unsure whether your specific purchase falls inside your state’s class period, the settlement site’s eligibility lookup is the place to check — don’t guess, and don’t take a third-party site’s word for it over the official notice.
Key Takeaways
- The $120,334,500 settlement covers homebuyers who paid a commission on an MLS-listed home purchase, during a class period that varies by state and defendant.
- File free, directly, at HomebuyerSettlement.com — with your recorded deed — by October 27, 2026.
- This settlement did not create the negotiable, written buyer-agent commission rules; those came from the earlier Sitzer/Burnett settlement in August 2024.
- Nobody legitimately needs to charge you to file a class-action claim. Ever.
The Bottom Line
If you’re staring at a settlement notice wondering whether it’s real, whether it’s worth your time, or whether the site you found it on is trying to get between you and your own money — that instinct to slow down and check is a good one, not paranoia. This settlement is real, the money is real, and filing takes a few minutes and costs you nothing. Go straight to the source, keep your deed handy, and don’t let anyone — a company, a “claim service,” or a headline promising more than the fine print delivers — talk you out of a few dollars you’re entitled to for free.
Frequently Asked Questions
What is the Tuccori v. At World Properties homebuyer settlement?
It’s a $120,334,500 class action settlement resolving claims against the National Association of Realtors and the residential real estate companies named in the litigation. The official notice says 25 of those companies have agreed to the settlement, and does not name them; plaintiffs allege the conduct kept real estate broker commissions artificially high. The case is Tuccori, et al. v. At World Properties LLC, et al., No. 1:24-cv-00150, in the U.S. District Court for the Northern District of Illinois. The defendants have not admitted wrongdoing.
Am I eligible for a payment from the $120 million homebuyer settlement?
You may qualify if you purchased a home listed on a Multiple Listing Service anywhere in the United States and a commission was paid to any brokerage in that transaction, during your state’s applicable class period. The official notice says only that “the date ranges for the Class Periods vary by state” and does not publish one set of dates, so the settlement site is the only place that answers it for your transaction. Check your specific eligibility at HomebuyerSettlement.com.
What do I need to file a claim?
A recorded property deed for the home you purchased. That’s the documentation the settlement administrator uses to verify your claim and calculate your payment.
What is the deadline to file a claim, and is there a cost?
The claim filing deadline is October 27, 2026. Filing is free at the official administrator site, HomebuyerSettlement.com. You should never have to pay anyone a fee or percentage to file a class-action claim.
Did this settlement make real estate commissions negotiable?
No. The written buyer-agent agreement and commission disclosure rules came from an earlier case — the Sitzer/Burnett settlement — and took effect industry-wide on August 17, 2024. This $120 million settlement requires NAR to keep complying with those existing rules; it doesn’t create new ones.
This is what I’m seeing after more than 30 years of tracking debt relief and settlement claims, and it’s what I’d tell my own family if they called me about this. Take it as one informed perspective — but only you know your full situation, your paperwork, and your risk tolerance. Use this as input for your decision, not a directive. Nobody gets to tell you what to do with your own money. Not me, not anyone.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



