

If you’re searching for the “$200 million Kia and Hyundai theft settlement,” I need to stop you before you spend an afternoon hunting for a claim form that no longer exists.
Debt is math wrapped in emotion — and so is a settlement claim. The math here is simple. The part people get wrong is which settlement they’re even looking at.
The $200 Million Settlement You Heard About Already Closed
The Claim: “There’s a $200 million Kia and Hyundai theft settlement open right now — file your claim before it’s gone.”
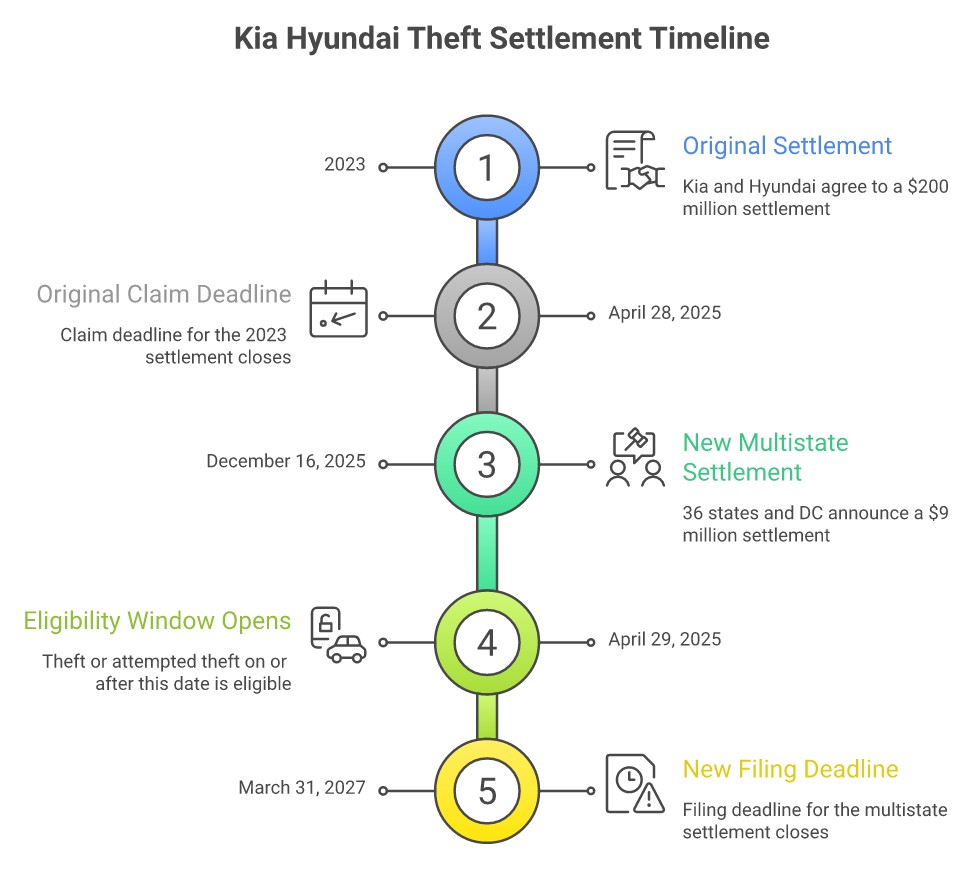
The Reality: That settlement is real, but it isn’t open anymore. Kia and Hyundai agreed to a class action settlement valued at more than $200 million when it was first announced in May 2023, after a wave of thefts driven by a TikTok trend that showed people how to steal certain models with nothing more than a USB cable, thanks to engine immobilizers the manufacturers left out. NPR covered the original deal when it was announced. That figure was later revised down, and the settlement that actually received final court approval in October 2024 was valued at $145 million. That settlement covered reimbursement for deductibles, out-of-pocket theft losses, and total-loss claims tied to thefts that happened before the free anti-theft software update reached your car — but the claim-filing deadline for it was extended and then closed on April 28, 2025. If your theft happened before that window closed and you never filed, I’m sorry — that door is shut.
Claiming money you are owed is one good day. What you do over the following year is what actually changes your position.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
I’m not writing this post to send you chasing a closed claim form. I’m writing it because there’s a second, newer settlement that is open right now, most owners have never heard of it, and it comes bundled with a second move that has nothing to do with the settlement check itself.
The One That’s Actually Still Open
On December 16, 2025, a coalition of 36 attorneys general — 35 states and the District of Columbia — announced a separate $9 million multistate settlement with Hyundai and Kia — this one over vehicles that still didn’t have real theft protection even after the original software fix. Attorneys general in Massachusetts, Washington, D.C., North Carolina, Illinois, and Washington state all published their own versions of the same announcement, which is usually a good sign a settlement is the real thing and not somebody’s scraped-together claim mill.
Who this covers: Owners and lessees of 2011–2022 Kia and Hyundai vehicles that were not factory-equipped with engine immobilizers, where the car had already received the free anti-theft software update — or had an appointment scheduled for it — and then was stolen or someone tried to steal it on or after April 29, 2025. That date matters. It’s not about when you bought the car. It’s about when the theft or attempted theft happened, relative to the software fix. The two settlements’ filing windows sit back-to-back on the calendar (one’s deadline was April 28, 2025; the other’s eligibility starts April 29, 2025) — but a filing deadline and an eligibility cutoff aren’t automatically the same thing, so if your theft falls right around that boundary, don’t assume either way. Check both settlement sites or call your JAG office / a consumer attorney to confirm which one (if either) covers your specific date.
The settlement does two things. First, Hyundai and Kia have to offer every eligible owner a free zinc-reinforced ignition cylinder protector — a physical hardware fix, not just a software patch — with a year from the date of your notice to get it installed at a dealership. Second, there’s a $4.5 million restitution pool for people who had a theft or attempted theft after the software update but before that hardware fix reached their car — the other half of the $9 million goes to the states themselves, not to a hardware-program fund, per the states’ own settlement announcements. The year-range and immobilizer criteria above are a starting point, not a guarantee — not every 2011-2022 Kia or Hyundai trim was missing the immobilizer, so run your VIN through the settlement site’s own lookup tool before assuming you’re covered or excluded.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Total Loss
Up to $4,500
Partial Loss / Damage
Up to $2,250
Attempted Theft
Up to $375
Those per-claimant figures are reported consistently across multiple settlement-tracking outlets covering the administrator’s claim tiers — TopClassActions, RecordingLaw’s settlement guide, and Dealership Guy’s coverage — though none of the state attorney general press releases I read broke the pool down to the dollar for each tier, so treat those as the reported range rather than a number written into any one AG’s release. You have until March 31, 2027 to file. The claim itself is free — it’s administered by a firm called Angeion, and you file it at HKMultistateImmobilizerSettlement.com, or by calling Kia customer care directly at (800) 333-4542 if your vehicle is a Kia.
Do Both Things in One Sitting
Here’s my actual advice, and it’s not just “go file the claim.”
Every document the settlement wants from you is also the exact paperwork you need for a conversation with your insurance company that most Kia and Hyundai owners never have. The claim asks for a police report, a total-loss or partial-loss letter from your insurer, proof you paid your deductible, and proof of any reasonable theft-related expenses. Pull all of that this weekend if you were affected, and use it twice. One caution: if your insurer already reimbursed you for this same theft, they may have a legal right to part of your settlement recovery (called subrogation) — check your policy or ask a consumer attorney before assuming the settlement check is entirely yours to keep.
The Move: (1) Gather your police report, your insurer’s loss letter or deductible receipt, and any repair or towing invoice. (2) File the settlement claim at HKMultistateImmobilizerSettlement.com — it takes maybe fifteen minutes and costs nothing. (3) Get the free hardware update at a dealer if you haven’t already, and get the completion paperwork in writing. (4) Call your insurer, tell them the update is installed, and ask them to re-rate the vehicle. Don’t skip step four — it’s the one most people never think to do.
The Insurance Problem the Settlement Doesn’t Fix
The settlement check is the small money. For a lot of Kia and Hyundai owners, the bigger financial hit has been what their insurance company did next.
Because roughly 7 million of these vehicles left the factory without an industry-standard immobilizer, insurers started treating them as a measurably higher risk. ABC News reported that State Farm and Progressive stopped writing new policies for certain high-theft models in some states, and local coverage documented the same thing — drivers who’d never filed a claim in their lives suddenly couldn’t get insured. Other existing policyholders got hit with rate hikes, purely because of the model they drove.
Here’s the part that should change how you think about this: the fix actually works. The Highway Loss Data Institute found that vehicles with the free anti-theft software update had theft-claim frequencies 53 percent lower than vehicles without it — and whole-vehicle theft frequency fell 64 percent. That’s not marketing copy — it’s the same kind of loss data insurers use to set your rate in the first place. If your insurer’s underwriting model priced in the theft risk from a car without an immobilizer, the data says that risk drops by more than half once the fix is installed — and now, with the zinc sleeve, you have physical hardware plus paperwork proving it.
I want to be straight with you about what I don’t have: I don’t have a document from Kia, Hyundai, State Farm, Progressive, or anyone else promising that showing up with your installation paperwork automatically gets your rate lowered or your policy reinstated. Nobody has published that policy. What I have is the data an insurer would need to justify re-rating you, and the fact that most owners never call and ask. If you don’t ask, the answer is always no. If you ask with the paperwork in hand, you at least made your insurer look at the actual risk instead of the model name on the title. I made the same “ask, don’t assume” argument when I covered Oppenheimer’s cash-sweep settlement — the people who benefit are the ones who actually pick up the phone and ask their provider to check the number.
And if you’re staring at a $2,250 partial-loss bill wondering how you’d cover it even with the settlement check on the way, you’re not alone — 59% of Americans can’t cover a $1,000 emergency out of savings, per Bankrate’s 2026 survey. A theft deductible is exactly the kind of expense that turns into new debt if there’s nothing behind it.
Do not pay a “claim filing service.” The settlement claim form is free, and filing it takes about fifteen minutes yourself at the official site. Anyone who contacts you offering to file this claim for a fee, or asks for payment or account information “to release” your settlement money, is not helping you. I saw the same “file your claim here” pitch used against Grubhub drivers waiting on FTC refunds — it’s the same script, just a different logo. Report them and move on.
This isn’t the only real settlement quietly paying out right now, either — I also covered two credit unions that just agreed to refund overdraft and NSF fees to members who never knew to ask. It’s worth five minutes to check whether you’re owed money you don’t know about before assuming you aren’t.
Key Takeaways
- The original $200 million Kia/Hyundai theft class action from 2023 is closed — its claim deadline passed April 28, 2025.
- A separate $9 million multistate settlement, announced December 16, 2025 by 36 state AGs and D.C., is open now through March 31, 2027.
- It covers 2011–2022 Kia/Hyundai owners whose vehicle had the software update (or a scheduled appointment) and was stolen or targeted on or after April 29, 2025.
- Reported payouts: up to $4,500 for a total loss, up to $2,250 for partial loss/damage, up to $375 for an attempted theft.
- File free at HKMultistateImmobilizerSettlement.com — the same documents you gather for the claim (police report, insurer’s loss letter, deductible receipt, repair invoice) are also what you need to ask your insurer to re-rate you now that the free anti-theft hardware is installed.
The Bottom Line
If somebody told you about a $200 million Kia or Hyundai theft settlement, they weren’t lying — they were just late. The one that matters to you right now is smaller, newer, and still open, and it comes with a second move almost nobody makes: use the same paperwork to push your insurer to look at your actual risk instead of your car’s reputation. Neither of those things requires you to pay anyone a cent. Do the free thing twice this weekend, and you’ve turned an afternoon of paperwork into both a check and a shot at a lower bill every month after.
Frequently Asked Questions
Is the $200 million Kia and Hyundai theft settlement still open?
No. That original class action settlement — announced at more than $200 million in 2023, later revised down to a $145 million fund at final court approval in October 2024 — had its claim-filing deadline extended and then closed on April 28, 2025. If your theft happened before then and you never filed, that claim window is shut. What’s open now is a different, smaller settlement described below.
What is the new Hyundai and Kia settlement that’s still open?
It’s a $9 million multistate settlement announced December 16, 2025 by a coalition of 36 attorneys general — 35 states and the District of Columbia. It covers 2011–2022 Kia and Hyundai vehicles that lacked a factory-installed engine immobilizer, where the car had already received the free anti-theft software update (or had an appointment scheduled) and was then stolen or targeted for theft on or after April 29, 2025. You have until March 31, 2027 to file a claim, free, at HKMultistateImmobilizerSettlement.com.
How much money can I actually get from this settlement?
Settlement-tracking sites reporting on the administrator’s claim tiers cite up to $4,500 for a total loss, up to $2,250 for partial loss or damage, and up to $375 for an attempted theft. The state attorney general press releases I reviewed confirm the $4.5 million restitution pool but don’t break it down claim-by-claim, so treat those per-claimant figures as the reported range rather than a number guaranteed in any one government release.
What documents do I need to file a Kia or Hyundai theft settlement claim?
Generally: a copy of the police report for the theft or attempted theft, a total-loss or partial-loss letter from your insurance company, proof you paid your insurance deductible, and proof of any reasonable theft-related expenses such as a repair or towing invoice. Gather all of it at once — you’ll want the same documents if you decide to ask your insurer to re-rate your policy after the anti-theft hardware is installed.
Will installing the anti-theft update or filing this claim lower my car insurance?
There’s no published guarantee of that from any manufacturer or insurer. What’s documented is that the Highway Loss Data Institute found the free software update cut theft-claim frequency by roughly 53 percent — real loss data, the same kind insurers use to set rates. Some insurers, including State Farm and Progressive, had stopped writing new policies for certain high-theft Kia and Hyundai models in some states. Once you have your installation paperwork for the physical zinc sleeve, calling your insurer and asking them to reconsider your rate or your eligibility is a reasonable, well-documented ask — it’s just not a promise. If you don’t ask, the answer is always no.
If this helped, forward it to anyone you know who drives a Kia or Hyundai from this era. Most owners have no idea this second settlement exists, and even fewer have thought to use the same paperwork on their insurance company.
This is what I’m seeing after over 30 years of helping people with money and debt. Only you know your full financial situation. Take this as input for your thinking, not a directive. Nobody gets to tell you what to do with your money. Not me, not anyone.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



