

Written by Steve Rhode, consumer debt expert since 1994 • Last updated August 14, 2026
Quick Answer: A creditor, landlord, or repo company ignored your rights under the Servicemembers Civil Relief Act — maybe a car was repossessed, a judgment was entered without checking your military status, or you’re still being charged over 6% interest on a debt from before you deployed. Most of that is illegal without a court order. Put the creditor on written notice, document everything, and call your JAG legal office or Military OneSource today. Don’t wait it out from overseas — the deadlines are real, but so are your protections.
What Just Happened to Your Rights
The Servicemembers Civil Relief Act gives active-duty servicemembers — and, in most cases, Guard and Reserve members activated under federal orders for more than 30 days — legal protections that creditors, landlords, and courts are supposed to check for before they act. A lot of companies don’t check. A “buy here, pay here” lot repossesses a car the normal way because a payment was missed while you were overseas. A property management company runs its standard eviction process because nobody flagged your file. A credit card issuer keeps charging 22% on a balance you opened years before you ever put on a uniform, because you never told them to stop.
The default judgment piece is the one that blindsides people hardest: a court can enter a judgment against you without you ever knowing it happened, because the law only protects you if the company suing you files an affidavit about your military status — and some plaintiffs skip proper verification, guess wrong, or just don’t look very hard.
The Mistake You’re About to Make: Assuming every SCRA protection is automatic. Some are — a creditor legally cannot repossess a car you started paying on before you entered active duty without a court order, full stop. But others require YOU to invoke them in writing. The 6% interest rate cap and your right to break a lease or a cell phone contract only kick in after you send the company written notice with a copy of your military orders attached. Waiting, assuming “someone on base will handle it,” or figuring you’ll deal with it after you’re home just lets the interest and the paperwork pile up while your protections sit unused.
Your Options Right Now
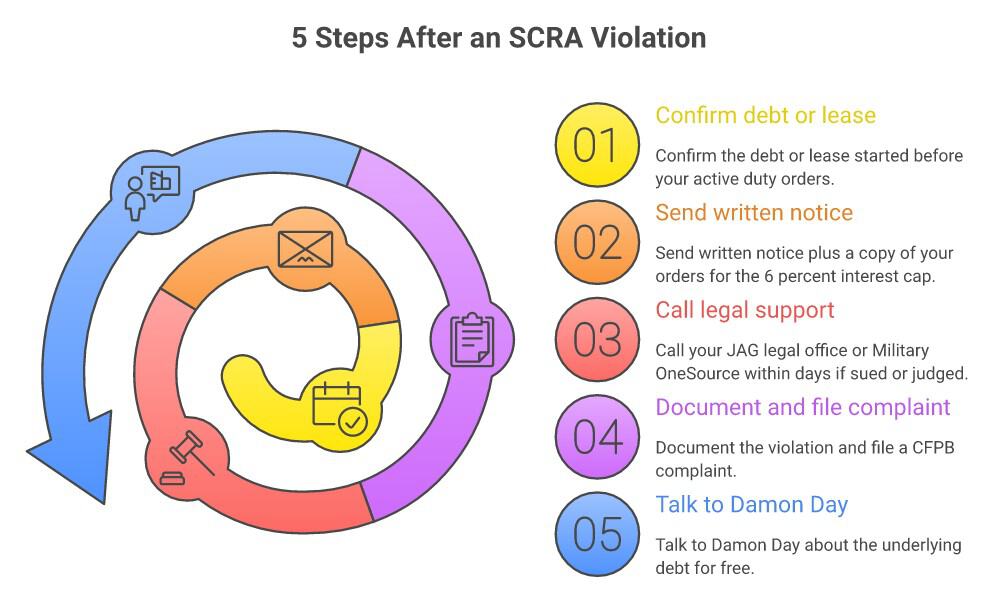
What to Do in the Next 48 Hours
- Confirm the timing — it changes which rule applies. Was the debt or account opened BEFORE your active-duty orders started? The interest rate cap and repossession protection generally apply to obligations from before your service began. Lease termination works differently depending on WHEN you signed, and it isn’t instant even when you qualify. If you signed a residential or motor-vehicle lease before you entered service, you can give notice at any time after entering — no waiting period to start the process. But a residential lease doesn’t end the moment you give notice: it terminates 30 days after your next rent due date following delivery of the notice. A motor-vehicle lease does end immediately, effective the day you deliver notice and return the vehicle. If you signed the lease while already in service, termination requires a later qualifying order first — a PCS or a deployment of 90 days or more for a residential lease, 180 days or more for a motor vehicle lease — then the same timing rules apply once you give notice. Cell phone, cable, and internet contracts follow the second rule (a qualifying PCS or 90-day-plus deployment order after you signed), with no pre-service exception. Storage-unit contracts aren’t clearly covered by federal SCRA at all — check with your JAG office before assuming one is. Pull your orders and the account’s origination date side by side before you contact anyone.
- Send WRITTEN notice today. Mail, fax, or email your creditor a written request for the 6% interest rate cap (50 U.S.C. § 3937) with a copy of your military orders attached. Do this even if you already called — a phone call does not create the legal notice the statute requires. Once the creditor receives it, all interest above 6% is forgiven — not just capped — retroactive to the day you entered service, for your whole period of military service. And there’s a deadline: if you didn’t send notice while you were still serving, you generally have until 180 days after your discharge or release to send it and still invoke the cap.
- If you were sued or a judgment was already entered, call your JAG legal office or Military OneSource (800-342-9647) within days, not weeks. Courts are required to verify military status with a sworn affidavit before entering a default judgment (50 U.S.C. § 3931) — filing a knowingly false affidavit is a federal crime. If that check was skipped, you have 90 days after you leave military service to ask the court to reopen the judgment and get your day in court. If the underlying debt turns out to be more than you can manage even after the SCRA issue is fixed, the Find Your Path quiz and NACBA can help you weigh bankruptcy as a separate, later decision.
- Document the violation and file federal complaints. Write down dates, names, what was taken or threatened, and any notice you already sent. Then file with the CFPB and the Justice Department’s Servicemembers and Veterans Initiative — since 2011, DOJ has recovered over $481 million for more than 147,000 servicemembers by pursuing exactly these violations (DOJ’s own May 2025 accounting — the total only grows with each new settlement).
- Talk to Damon Day about the debt itself, alongside your JAG attorney. Your JAG office or Military OneSource attorney handles the legal violation; the underlying debt is a separate, financial conversation — and it’s free. Talk to Damon Day for free.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
How to Actually Stop It — Your 4 Paths
- Send a formal SCRA notice citing the exact statute (fastest option). A lot of violations get fixed within days once a written demand with the U.S. Code section attached lands on a compliance desk — companies that ignore it are the ones ending up in DOJ settlements. In 2026 alone, an auto dealership paid over $137,000 and a home security company paid over $1.3 million to resolve SCRA allegations after servicemembers and DOJ pushed back.
- Ask the court to reopen a wrongful default judgment. File a motion under 50 U.S.C. § 3931(g) within 90 days of leaving military service if you can show your service affected your ability to defend the case and you have a real defense. Your JAG office can help draft this at no cost.
- File federal complaints and let enforcement do the work. The CFPB forwards SCRA complaints to the company and tracks the pattern; DOJ’s Servicemembers and Veterans Initiative actively investigates on its own, without you needing to hire a lawyer first. over $481 million recovered since 2011, as of DOJ’s own May 2025 accounting, means this isn’t a long shot.
- What WON’T work: paying the disputed amount just to make it stop. Paying an inflated balance, a repossession deficiency, or a wrongful judgment without disputing it first often waives your right to get the illegal interest refunded or the judgment reopened later. Get any resolution in writing before you send money.
What You Need to Know About Your Rights Under the SCRA
Maximum interest rate on debt from before you entered active duty, once you send written notice (§3937)
Recovered by DOJ for more than 147,000 servicemembers since 2011, as of May 2025 — and rising
Minimum court stay when service affects your ability to appear (§3932) — also your deadline to reopen a default judgment after leaving service (§3931(g))
2026 monthly rent ceiling that still triggers “no eviction without a court order” — covers nearly every rental in the country
The SCRA is federal law, so its baseline protections apply the same way in every state: a 6% interest cap on pre-service debt (§3937), mandatory military-status verification before a default judgment (§3931), no repossession without a court order on pre-service installment purchases (§3952), no eviction without a court order (§3951), and the right to terminate a residential or motor-vehicle lease (§3955) — you can give notice any time if you signed before entering service, or after a later qualifying order (90 days for residential, 180 for vehicle) if you signed while already in service, though a residential lease doesn’t actually end until 30 days after your next rent due date following notice (a motor-vehicle lease ends immediately) — or to terminate a cell phone, cable, internet, or similar service contract after a qualifying PCS or 90-day-plus deployment order signed before that order (§3956).
| Protection | What the law provides | Notes |
|---|---|---|
| Interest rate cap (federal) | 6% on pre-service debt, after written notice | Credit cards, auto loans, private student loans, some mortgages |
| Default judgment (federal) | Court must verify military status; 90-day reopen window after service ends | Applies nationwide; false affidavit is a federal crime |
| Eviction (federal) | No eviction without a court order (rent ≤ $10,542.60/mo in 2026) | Court can still evict, but must consider a stay, usually 90 days |
| Repossession (federal) | No repossession without a court order if any payment was made pre-service | Vehicles, furniture, appliances bought by installment contract |
| California (state law, not federal SCRA) | Extends similar protections to state active-duty and National Guard orders | Broader trigger than federal SCRA alone — check with your JAG office if you’re on state orders |
If you’re National Guard or Reserve and unsure whether your specific orders qualify — federal Title 10, Title 32, or a governor’s state active-duty call-up all trigger different levels of protection — bring your orders to your installation JAG office or a free Military OneSource legal consultation and ask directly. It’s exactly the kind of edge case worth ten minutes on the phone.
If a creditor, landlord, or repo company is violating your rights, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov — or start with your JAG legal assistance office or a Military OneSource consultation, since those are already paid for by your service.
Steve’s Take
I filed bankruptcy in 1990, so I know what it feels like when a company treats you like a line on a spreadsheet instead of a person going through something hard. For servicemembers it’s worse: you can be doing the hardest job in the country, half a world away, and a leasing office or a repo lot back home just runs its normal process because nobody bothered to check a box. Congress wrote this exception into the law on purpose, decades ago, precisely so you wouldn’t come home to a mess you never had a chance to prevent. Debt — and a wrongful judgment — is math wrapped in emotion. Don’t let shame or “I don’t have time for this while I’m deployed” keep you from making one phone call to your JAG office. More than $481 million in DOJ recoveries since 2011 — DOJ’s own May 2025 accounting, and it only grows — proves these violations are common. You didn’t do anything wrong by serving.
Frequently Asked Questions
My car got repossessed while I was deployed — can I get it back?
If you made a down payment or at least one installment payment before you entered active duty, a creditor cannot repossess without a court order (50 U.S.C. § 3952). DOJ has forced companies to return vehicles and pay damages in cases like Holmes Motors, which agreed to pay over $137,000 in July 2026 to resolve allegations it illegally repossessed vehicles from three servicemembers without court orders. Contact your JAG office or file a CFPB complaint immediately.
A default judgment was entered against me while I was overseas — can I undo it?
Often, yes. Courts are required to verify military status before entering a default judgment (§ 3931), and if that check was skipped or done wrong, you can ask the court to reopen the case under § 3931(g). You have 90 days after leaving military service to file, and you’ll need to show your service materially affected your ability to defend and that you have a real defense.
Do SCRA protections apply to National Guard and Reserve, or just active duty?
Guard and Reserve members are generally covered once activated under federal Title 10 orders for more than 30 days. A specific type of Title 32 order can qualify too — a call to active service under 32 U.S.C. § 502(f) of more than 30 consecutive days, in response to a presidentially declared national emergency with federal funding — but routine Title 32 training or drill weekends generally don’t. Some states — California’s Military and Veterans Code, for example — extend similar protections to members on state active-duty orders even when federal SCRA wouldn’t otherwise apply. Confirm with your JAG office which of your specific orders qualify.
How fast does the 6% interest rate cap kick in once I send notice?
It isn’t automatic. You have to send the creditor written notice plus a copy of your military orders (§ 3937). Once they receive it, all interest above 6% on that pre-service debt is forgiven — retroactive to the day you entered service, not just from the date you sent the notice — for your whole period of service. If you never sent notice while serving, you generally have until 180 days after your discharge or release to send it and still get the cap.
My landlord is trying to evict me — can they do that while I’m deployed?
Not without a court order, if the home is your (or your dependents’) residence and the rent is at or below the 2026 threshold of $10,542.60 a month (§ 3951) — a threshold that covers nearly every rental in the country. A judge can still order the eviction, but the law requires the court to consider staying it, typically for 90 days, if your military service affects your ability to pay.
Does the SCRA cover my spouse or dependents too?
Some protections extend to dependents specifically — the eviction protection names them directly. Others, like the interest rate cap, are tied to accounts in the servicemember’s own name. If your spouse is on a lease or loan with you, mention that when you call your JAG office; it can change which protections apply.
What actually happens to the company that violated my rights?
Companies that violate the SCRA can face a private lawsuit from the servicemember — with real damages, attorney’s fees, and sometimes punitive damages — on top of Justice Department enforcement. In 2026, DOJ settled with a home security company for over $1.3 million and an auto dealership for over $137,000 over these exact kinds of violations. Since 2011, DOJ has recovered more than $481 million for over 147,000 servicemembers, per its own May 2025 accounting — and that total keeps climbing with each new settlement.
I’m a National Guard member on state orders — am I covered?
State active-duty orders from a governor’s call-up don’t automatically trigger federal SCRA protection, but many states have written their own version of the law for members on state orders — California’s Military and Veterans Code is one example. Bring your specific orders to your JAG office or a free Military OneSource consultation and ask directly.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state, your installation’s JAG legal assistance office, or a free Military OneSource legal consultation. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: An SCRA violation is serious but almost always fixable — often faster than a normal debt dispute, because federal law and an active DOJ enforcement program are already on your side. Send written notice, document everything, and call your JAG office or Military OneSource this week. The longer a wrongful judgment or an unrefunded overcharge sits, the more paperwork stands between you and getting it undone.
The Bottom Line
You didn’t do anything wrong by serving, and you’re not the only one this has happened to — DOJ’s $481 million-plus in recoveries since 2011 (its own May 2025 accounting) says this is a pattern, not a personal failure. Congress built these protections into law specifically because deployment makes people vulnerable to exactly this kind of company shortcut. The servicemembers who acted fast — written notice, documentation, a call to JAG — got their money and their vehicles back faster than the ones who waited it out. If you know someone who’s deployed or about to be, send them this page before they need it — knowing the deadlines in advance is half the battle. See all your debt relief options and take the Find Your Path quiz if the underlying debt needs its own plan.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 9): The paycheck advance app said it wasn’t a loan. Connecticut just made it give every fee back.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



