

Debt is math wrapped in emotion. When someone takes your monthly payment and your debts do not move, the math stopped being done on your behalf a while ago.
On August 18, 2026, Connecticut Banking Commissioner Jorge L. Perez signed a Temporary Order to Cease and Desist, Order to Make Restitution, Order to Provide Disgorgement, Notice of Intent to Issue Order to Cease and Desist, Notice of Intent to Impose Civil Penalty, and Notice of Right to Hearing against a debt relief operation doing business as CDS Financial and two men, David Lugo and Kevin Lugo. I want to be precise about what that document is and isn’t before I say another word about it.
This Is Not a Final Finding of Wrongdoing. What I describe below are things the Connecticut Department of Banking alleges in a public, signed order — not facts a court or tribunal has established. CDS Financial, David Lugo, and Kevin Lugo each have a right to a hearing under Connecticut law, and if a hearing is requested, one is scheduled for October 14, 2026. If none of the three respondents requests a hearing within 14 days of receiving the order, the allegations against that respondent are treated as admitted and the temporary order becomes permanent — but as of the date I’m writing this, that has not happened yet. If you represent CDS Financial, David Lugo, or Kevin Lugo and believe anything in this post is inaccurate, contact me and I’ll review it promptly.
What I could confirm, and what I could not. I downloaded the order directly from the Connecticut Department of Banking and confirmed it is the genuine public document, so everything I quote below is really in it. What I cannot do is verify the underlying facts myself. The bank-account figures come from statements the Department reviewed covering February 2024 through July 2024 — records I have never seen. The order also states, at paragraph 45, that CDS Financial failed to make its records available to the Commissioner, so the Department built its account without records from the company. And the legal standard here is not proof: the order says repeatedly that the Commissioner “has reason to believe” these violations occurred. That is the threshold for a temporary order, and it is a lower bar than a finding after a hearing. So read what follows as what Connecticut alleges and why, not as settled fact.
The Part of This Story That’s Personal to Me
Here’s why I’m writing about a Connecticut regulatory filing involving a company most of the country has never heard of: I’ve seen this address before.
Back in 2019 — more than seven years ago — I wrote about a company called LifeBridge Servicing after a reader sent me a “pre-selected consolidation loan” mailer that led, on closer inspection, to what looked like debt settlement services dressed up as a loan offer. I dug into Massachusetts business filings at the time and found that LifeBridge Servicing listed its address as 999 Broadway, Suite 101, Saugus, MA 01906 — which, I noted then, is also the address of a Holiday Inn Express hotel. The LLC’s manager was a man named David Lugo, and that same David Lugo was also the founding manager of a second entity, Clarity Debt Solutions, LLC. Read my original reporting: LifeBridge Servicing: Red Flags to Know.
The Connecticut order now in front of me gives 999 Broadway, Suite 101, Saugus, Massachusetts as one of two addresses for CDS Financial — the Department served the order there by certified mail. The order also states that David Lugo is currently the Manager of Lifebridge Servicing, LLC and was the Manager of Clarity Debt Solutions, LLC (dissolved in 2021) — the exact same two entities I flagged in 2019, at the exact same address. The order adds a third entity: 2nd Chance Solutions, Limited, a Massachusetts corporation formed May 29, 2025, of which David Lugo is President, Treasurer, Secretary and Director, and which, per the order, “purports to provide debt settlement, credit repair, tax relief and medicare lead generation.”
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
I want to be careful here, because precision matters: my 2019 post was research into public Massachusetts business filings, not an allegation that anyone had broken the law at that time. So let me do the same thing here that I did at the top of this post, and separate what I can show you from what I cannot.
What those 2019 filings showed. David Lugo listed as the LLC manager of LifeBridge Servicing, registered 24 July 2018, stated purpose “debt settlement services.” The same person as founding manager of Clarity Debt Solutions, LLC, registered 12 September 2016. And a business address of 999 Broadway, Suite 101, Saugus — which, as I noted at the time, is also the address of a Holiday Inn Express. The 2026 Connecticut order gives that same Saugus address for CDS Financial, and names David Lugo.
What those filings did not show, and what I still cannot tell you. Whether any of these companies were connected to one another beyond sharing an officer and an address. Whether anything improper happened at any of them. Whether the businesses were related in operation, in ownership, or not at all. Only CDS Debt Relief LLC, David Lugo and Kevin Lugo are respondents in the Connecticut action. No regulator has alleged anything against the other companies named here. What I am handing you is a set of public records you can pull yourself in about ten minutes. I will tell you plainly how I read them, because I have been doing this since 1994 and I wrote about this address once already: when the same manager and the same building keep turning up on debt-settlement filings across a decade, I pay attention, and I think you should too. But my read is not a finding, and I want the line between them to stay bright. What the records establish is the address and the manager. Whether these companies were connected in ownership or operation, I cannot tell you — and no regulator has alleged anything against the three that are not respondents. Reach your own conclusion; you have the same documents I do.
Why an address matters. A hotel address on a business filing isn’t automatically a red flag — lots of legitimate small operations use suite services or shared office space. What I can tell you is what the public filings show: the same Saugus address appears on filing after filing, across several entities, tied to the same person. Separately, one company at that address — CDS Financial — is the subject of this Connecticut order. The other entities named here are not respondents and no regulator has alleged anything against them. I am handing you a similarity I found in public records, not a conclusion about what it means.
Who the Order Names
The order names three respondents directly:
- CDS Debt Relief LLC, also known as CDS Debt Relief, LLC, doing business as CDS Financial — a limited liability company the order says was formed in Delaware on June 15, 2020, and registered in Massachusetts on January 26, 2021, with business addresses at 324 Datura St, Suite 140, West Palm Beach, Florida, and 999 Broadway, Suite 101, Saugus, Massachusetts.
- David Lugo — alleged by the order to be a manager and control person of CDS Financial, and separately identified as an officer or manager of three other entities (below).
- Kevin Lugo — also alleged by the order to be a manager and control person of CDS Financial.
The order also identifies three other entities connected to David Lugo, none of which are named as respondents in this action:
- 2nd Chance Solutions, Limited — a Massachusetts corporation the order says was formed May 29, 2025, purporting to provide “debt settlement, credit repair, tax relief and medicare lead generation.” The order lists David Lugo as its President, Treasurer, Secretary and Director.
- Lifebridge Servicing, LLC — a Massachusetts LLC the order says was organized July 24, 2018, with Massachusetts filings describing its services as “debt settlement services,” “marketing and financial services,” and “marketing and sales agency.” The order lists David Lugo as its Manager.
- Clarity Debt Solutions, LLC — a Massachusetts LLC the order says was formed September 12, 2016, and dissolved by the Massachusetts Secretary of the Commonwealth on June 30, 2021, with earlier filings describing its purpose as “financial services, debt management, credit services” and “debt settlement, debt negotiations, helping consumers out of debt.” The order lists David Lugo as its Manager.
The order also names Salem Five Bank as the institution where CDS Financial’s operating account was held. I want to be explicit: the order does not accuse Salem Five Bank of any wrongdoing. Banks hold operating accounts for all kinds of businesses; the bank isn’t alleged to have done anything wrong here.
What the Order Alleges Happened to Consumers
According to the order, CDS Financial “has never been licensed to engage in the business of debt negotiation, debt adjustment or money transmission in Connecticut or in any other state” per the Nationwide Multistate Licensing System and Registry (NMLS) — and Connecticut law requires all three licenses for a company doing what the order alleges CDS Financial was doing.
The order walks through one named consumer’s experience in detail (identified only as “CT Debtor 1” to protect her or his identity). The order states that a CDS Financial representative told this Connecticut resident the company would consolidate his debt, that he would pay CDS Financial directly, and that CDS Financial would pay off his debt within three to six months. According to the order, he signed a contract on December 15, 2023, enrolling $46,934 in unsecured debt and agreeing to 36 monthly payments of $1,000 beginning January 12, 2024 — payments the contract itself described as “credit repair fees” or “membership fees.”
Unsecured debt CT Debtor 1 enrolled, per the Connecticut order
Amount he paid before, per the order, CDS Financial stopped answering him
Fee the order alleges the contract charged, on debt enrolled — not debt reduced
The order alleges he made at least seven $1,000 payments in 2024, totaling $7,000, before creditors on the enrolled debts began calling him directly — seven months in, with (per the order) none of the promised debt relief services provided. When he tried to find out what was happening, the order states, “CDS Financial repeatedly disconnected his calls and has failed to respond to any e-mail correspondence.” As of the date the order was signed, the Department alleges CDS Financial has neither negotiated any of his debts nor returned his $7,000.
The order describes ten additional Connecticut consumers by town, listing payments withdrawn from their bank accounts between February and July 2024:
| Town | Payments | Total |
|---|---|---|
| Enfield | 2 | $750 |
| Niantic | 5 | $750 |
| Meriden | 3 | $2,469 |
| Easton | 2 | $758 |
| Wilton | 5 | $1,570 |
| Wallingford | 3 | $471 |
| Bridgeport | 3 | $1,800 |
| Litchfield | 6 | $2,400 |
| Naugatuck | 2 | $290 |
| Southington | 2 | $600 |
The order separately mentions a Better Business Bureau complaint from a Waterbury, Connecticut resident, filed January 9, 2025, in which she wrote that she consolidated her debts with CDS Financial in December 2023, lost contact with the company in July, and is “out $8,000.”
Where the Order Says the Money Went
This is the part of the filing that stopped me. The order reviewed bank statements for CDS Financial’s operating account at Salem Five Bank covering roughly six months, February through July 2024. In that window, the order alleges CDS Financial and David Lugo deposited or attempted to deposit approximately 1,569 payments from consumer debtors nationwide, totaling approximately $488,751 — and states plainly that “the Account’s bank statements do not evidence a single payoff of a consumer debtor account related to debt negotiation.”
In that same six-month window, the order alleges the account also showed:
Per the order, transferred to David Lugo’s personal checking and savings accounts
Per the order, cash withdrawals from the account
Per the order, paid to American Express from the account
The order also lists $32,216 paid to Discover, $3,311 to Capital One, and $8,143 in monthly payments to Toyota Financial Services described as related to a personal vehicle. There’s a single line I can’t get past: the order alleges a $1,191 point-of-sale purchase at Acapulcos, a restaurant in Beverly, Massachusetts, came out of the same account consumers were told held their debt-payoff money. The order also documents 378 service charges totaling $3,780 assessed against the account for returned deposited items, with descriptions the order quotes directly: “account closed,” “unauthorized signature returning,” and “altered/fictitious check.”
The order alleges CDS Financial and David Lugo “employed a scheme, device or artifice to defraud or mislead” consumers by taking in money earmarked for creditors and instead “misappropriating such funds by spending the funds on operating expenses, direct payments to David Lugo and other personal expenses.” I want to say this as clearly as I said the warning above: that is an allegation in a document that has not been through a hearing. It is also, word for word, what the Commissioner of Banking for the State of Connecticut signed his name to on August 18, 2026.
The Fee Math Nobody Explains to You
Here’s something worth understanding whether or not you’ve ever heard of CDS Financial, because it applies to any debt negotiator: Connecticut caps what a debt negotiator can charge. The Department’s Schedule of Maximum Fees, in effect since 2009, limits a debt negotiator’s total fees to 10% of the amount by which your debt is actually reduced. Not 10% of what you owe — 10% of what they actually save you.
The order alleges CDS Financial’s contract charged 25% of the “Verified Debt” enrolled — a fee calculated on the amount you owe rather than the amount saved. That’s not a small distinction. A fee based on the amount a debt is reduced is tied to a result. A fee based on the amount you enrolled is tied to the size of your problem instead.
The order also alleges the contract lacked the specific “Debtor’s three-day right to cancel” disclosure Connecticut law requires — a consumer protection that exists precisely so you have a cooling-off window before a debt relief contract locks in.
Myth: “My money is sitting in a holding account waiting to pay my creditors.”
Reality: The order alleges CT Debtor 1’s contract said exactly that — that funds “are transferred into a bank holding account on client’s behalf.” Connecticut law (Section 36a-659) requires a licensed debt adjuster to keep a separate account, held for the benefit of debtors, apart from the company’s own operating funds. The order alleges CDS Financial instead deposited Connecticut consumers’ payments directly into its general operating account — the same account the order says paid David Lugo’s personal expenses.
What the Department Says Happened When It Tried to Reach the Company
Connecticut received its first complaint about CDS Financial on August 15, 2024. The order states the Department emailed CDS Financial at its listed support address that same day, requiring a response by August 30, 2024, and sent two more follow-up emails on September 10 and September 26, 2024. When none of those produced a response, the order says the Department sent a certified letter on December 16, 2025, requiring a response by December 30, 2025. According to the order, CDS Financial has never responded to any of it, nor made its records available to the Commissioner.
Connecticut law authorizes a civil penalty of up to $100,000 per violation — and the order alleges multiple violations across debt negotiation law, debt adjustment law, and money transmission law, against all three respondents.
What Happens Next
This is a temporary order. Under Connecticut law, each respondent has 14 days from receiving it to request a hearing. If a hearing is requested, it’s scheduled for October 14, 2026, at 10 a.m., at the Department’s Hartford offices, with remote participation available at the hearing officer’s discretion. At that hearing, each respondent has the right to appear, present evidence, and contest every allegation in the order.
If a respondent does not request a hearing, or fails to appear at one that’s requested, the order says the allegations against that respondent “will be deemed admitted,” and the restitution and disgorgement orders become permanent against them. As of the date I’m publishing this, I don’t know whether any of the three respondents has requested a hearing. I’ll update this post if that changes and it becomes publicly available.
Separately from the hearing process, the order already requires CDS Financial, David Lugo, and Kevin Lugo — jointly and severally — to make restitution to every Connecticut consumer identified in the order, plus interest, and to disgorge any fees or revenue tied to the alleged violations.
This isn’t an isolated filing, either — I keep a running list of FTC and state regulatory actions against debt relief companies if you want to see how often this pattern shows up.
What I’d Tell You to Do About It
Whether or not you’ve ever heard of CDS Financial, this filing is a reminder of something I’ve said for as long as I’ve run this site: check before you pay, not after.
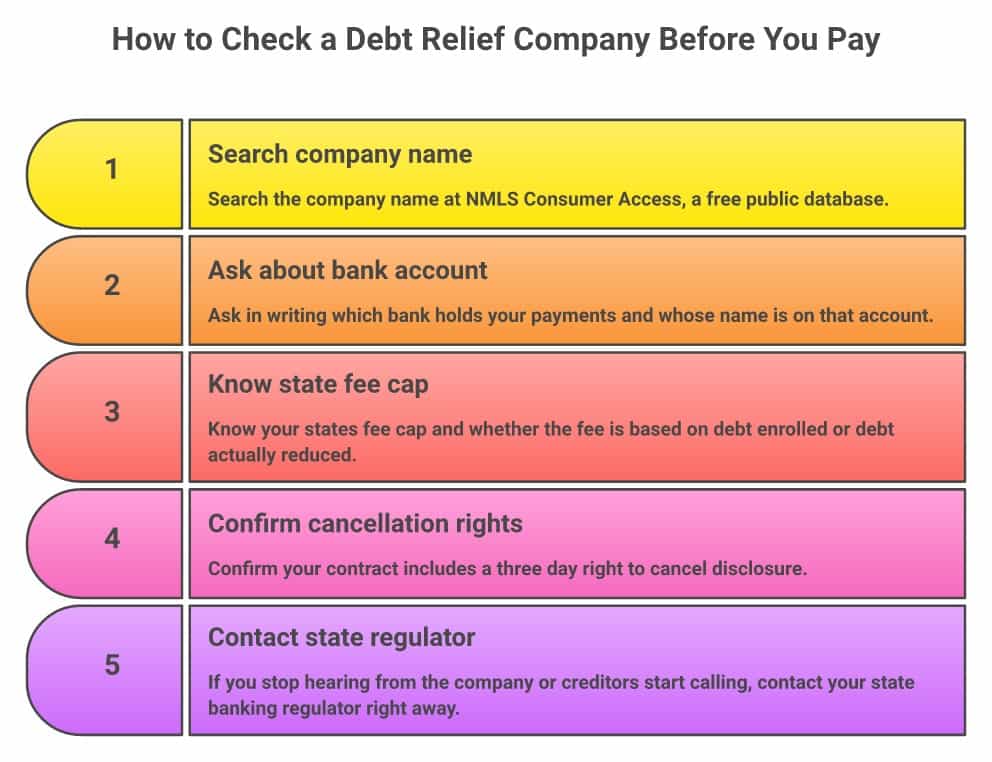
- Look up any debt relief company on NMLS Consumer Access at nmlsconsumeraccess.org. It’s free, it’s public, and it takes about ninety seconds. If a company offering debt negotiation, debt adjustment, or money transmission services in your state isn’t licensed there, that’s your answer before you sign anything.
- Ask, in writing, exactly which bank holds your money. A legitimate debt adjuster keeps your payments in a separate account held for your benefit — not the company’s general operating account. If you can’t get a straight answer to “what account, at what bank, in whose name,” that’s a red flag on its own.
- Know your state’s fee cap and what it’s calculated on. A fee based on what you owe gets paid whether or not you’re helped. A fee based on what gets saved only gets paid when there’s a result. Run any debt relief contract you’re considering through my free Contract Decoder before you sign it.
- If you’re a Connecticut consumer who paid CDS Financial and haven’t already, contact the Department of Banking’s Consumer Credit Division at 280 Trumbull Street, 16th Floor, Hartford, Connecticut 06103. The order includes a restitution requirement that exists specifically to get money back to consumers like you.
Bottom line: A state banking regulator has alleged, in a signed public order, that a debt relief company took in nearly half a million dollars from consumers over six months without evidence of a single debt payoff — and, separately, that David Lugo is listed in Massachusetts business filings as an officer or manager of several other entities going back to 2016. Those filings are public records; they are not accusations, and no regulator has alleged wrongdoing by those companies. None of that is proven in court yet. All of it is worth knowing before you send anyone your next payment.
Frequently Asked Questions
Is CDS Financial permanently banned from doing business in Connecticut?
Not yet. The August 18, 2026 order is a temporary cease-and-desist order plus notices of intent to make it permanent and impose a civil penalty. CDS Financial, David Lugo, and Kevin Lugo each have a right to request a hearing within 14 days of receiving the order. If none of them requests one, the order becomes permanent against that respondent by default.
Was CDS Financial ever licensed to do debt settlement in Connecticut?
According to the order, no. The Department states CDS Financial “has never been licensed to engage in the business of debt negotiation, debt adjustment or money transmission in Connecticut or in any other state,” per NMLS records.
What’s the connection between CDS Financial and LifeBridge Servicing?
According to the Connecticut order, David Lugo is currently the Manager of Lifebridge Servicing, LLC, a Massachusetts entity registered in 2018, and CDS Financial’s Massachusetts business address (999 Broadway, Suite 101, Saugus, MA) matches the address I found for LifeBridge Servicing when I researched that company in 2019.
If I paid CDS Financial, how do I get my money back?
The order already requires CDS Financial, David Lugo, and Kevin Lugo to make restitution to Connecticut consumers, plus interest, within 30 days of the restitution order becoming permanent. If you’re a Connecticut consumer, you can contact the Department of Banking’s Consumer Credit Division at 280 Trumbull Street, 16th Floor, Hartford, CT 06103. If you’re outside Connecticut, this order doesn’t directly cover you, but you can still file a complaint with your own state’s regulator and with the CFPB.
How do I check whether a debt relief company is licensed before I pay them?
Search the company’s name at NMLS Consumer Access, which is free and public. Debt negotiation, debt adjustment, and money transmission are all separately licensed activities in most states, and a legitimate company should show up there.
I’m going to keep watching this one. If a hearing gets requested, or if this order becomes final one way or the other, I’ll come back and tell you what happened. That’s what I’d want someone to do for me if I’d just paid $7,000 to a company that stopped answering the phone.
This is what the public record shows and what I’m seeing in it — not legal advice, and not the final word. Only you can decide what’s right for your situation, and if you’re currently enrolled with any debt relief company and worried about what you’re reading here, don’t wait for a regulator to tell you what to do next.
Before You Sign Anything: Run any debt relief contract through the free Contract Decoder to spot hidden fees and unfair terms. Check the company’s complaint history with the Scam-O-Meter.
Compare Your Real Options: Most debt relief companies won’t tell you about all your options — especially the ones they can’t profit from. Credit counseling has a 21-27% completion rate. Settlement resolves about 1% of enrolled debts fully. Bankruptcy has a 95% discharge rate — and protects your retirement. Take the Find Your Path quiz for a recommendation based on your actual numbers.



