

Written by Steve Rhode, consumer debt expert since 1994 • Last updated August 26, 2026
Quick Answer: Almost never — and mechanically, you usually can’t do it directly anyway. None of the federal loan servicers’ own payment pages I checked list a credit card as an accepted method; MOHELA’s payment options page, for example, lists auto-debit, a one-time online payment, phone payment, a debit card, your bank’s own bill-pay service, or a check or money order — credit card isn’t on it. The only way to put a federal student loan payment on a credit card is to route it through a third-party bill-pay processor that charges its own fee, and every dollar that processor sends to your servicer converts that much of your balance from federal student loan debt into ordinary credit card debt. The federal balance you have left keeps everything it always had — income-driven payments, forgiveness pathways, the discharge provisions if you die or become disabled. Only the portion you moved loses them. Pay one $400 bill this way and you have converted $400, not your loan. That is not the same as harmless: that $400 is now permanent unsecured debt at a rate near 22%, and unlike the federal balance beside it, it will not shrink when your income drops, will not pause if you lose your job, and will not go away if you die or become disabled. The processor keeps its fee either way. If you’re short this month, call your servicer first, before you touch a credit card at all. Ask about the new Repayment Assistance Plan, which for most federal borrowers bottoms out at $10 a month — and ask them to compare it against IBR, which can go to $0 if your income is at or below 150% of the federal poverty guideline. Or ask about a forbearance. One important exception: if what you hold is a Parent PLUS loan, the income-driven plans are largely closed to you. The IBR statute — 20 U.S.C. § 1098e — excludes what it calls an “excepted PLUS loan,” and the new RAP rules carry the same exclusion. I am not going to pretend the alternative is comfortable: the Standard Plan does not scale to your income, which is probably the whole reason you are reading this. Ask your servicer specifically what a Parent PLUS borrower in your situation can access this year, get the answer in writing, and if the number is impossible, that is worth taking to a bankruptcy attorney rather than to a credit card.
What This Decision Really Is
Start with the mechanics, because most people never get here. Your federal loan servicer isn’t set up to take a credit card. That’s not a policy quirk — it’s the reason the whole question is more complicated than “can I put this on plastic.” To get a card into the picture at all, you need a third-party bill-pay service that charges you a percentage fee (commonly in the 2.5%–3% range) to accept your card and mail or wire your servicer the money. On your card statement, that transaction posts as a purchase from the bill-pay company, not as “student loan payment” — and that distinction matters, because your card issuer, the credit bureaus, and the law all now treat what you owe as ordinary revolving credit card debt.
That’s the real decision hiding inside “should I do this.” You’re not choosing a payment method. You’re choosing to convert some or all of a federal student loan — a debt built with income-driven payment options, a path to forgiveness, and protections that trigger automatically if your life falls apart — and replace it with an unsecured credit card balance that has none of those built in. The interest rate usually gets worse too: federal Direct Loans first disbursed for 2025–2026 carry fixed rates of 6.39% for undergraduate loans and 7.94%–8.94% for graduate and PLUS loans, while the Federal Reserve reports the average credit card interest rate on accounts that carry a balance was 22.15% as of June 2026 — more than three times higher.
There’s one more trap inside the trap: if you (or a bill-pay service on your behalf) run the transaction as a cash advance instead of a purchase — which is how some workaround methods and convenience checks are structured — interest starts accruing that same day, with no grace period, at a rate the CFPB found is commonly 30% APR in the credit card agreements it reviewed, plus a separate cash advance fee the same CFPB report describes as typically “the greater of $10 or 5%” of the amount advanced.
The Mistake You’re About to Make: Doing the math on the processor’s fee and stopping there. A 2.5%–3% fee sounds like the whole cost, so a $400 payment “only” costs an extra $10–$12. That’s the wrong ledger. The real cost is what you give up: a federal loan’s income-driven payment floor ($10 a month under the new Repayment Assistance Plan, and as low as $0 under IBR if your income is at or below 150% of the federal poverty guideline), a forgiveness pathway, forbearance rights if you lose your job, and a loan that disappears entirely — owed by no one — if you die or become permanently disabled. Whatever portion you move to a credit card loses all of that. What you leave behind keeps it. Call your servicer before you call a bill-pay processor.
How to Actually Decide — The Questions That Change the Answer
Work Through These Before You Touch a Card
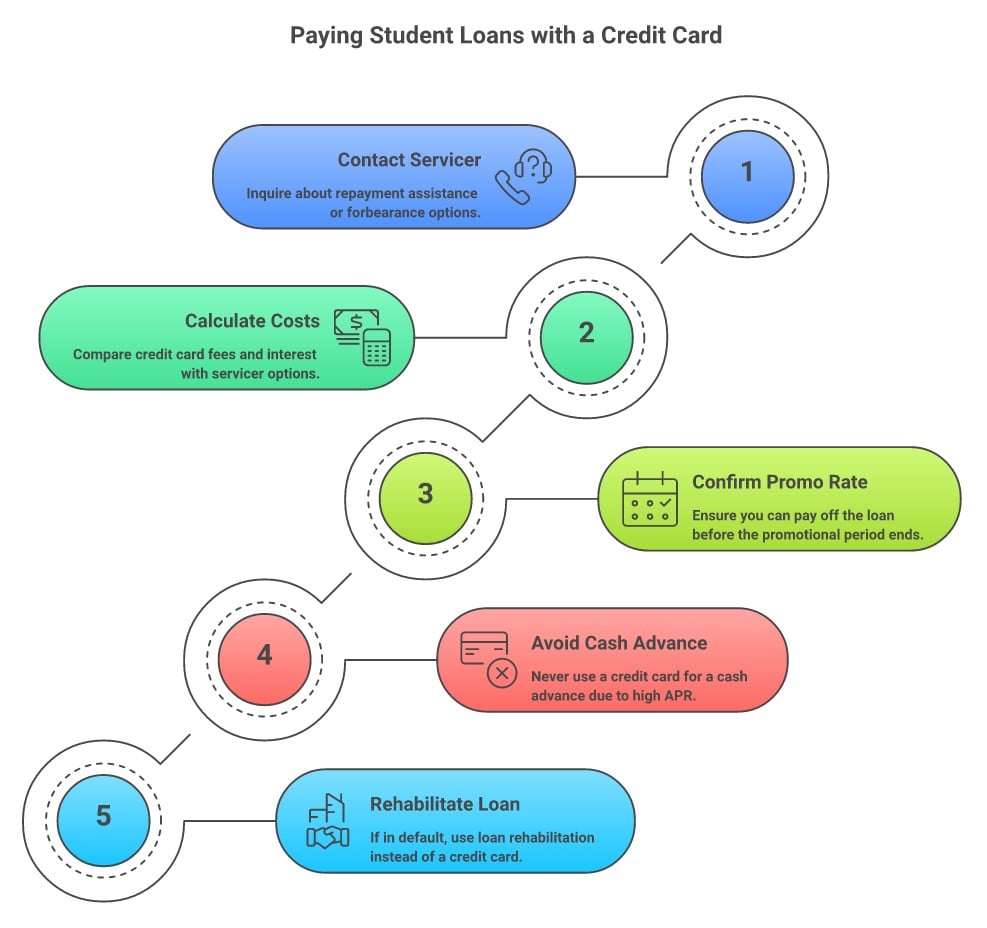
- Call your servicer first and ask about the Repayment Assistance Plan, an income-driven plan, or a forbearance — before you ever call a bill-pay processor. If your monthly bill is the problem, RAP can drop a federal loan payment to as low as $10 a month based on your income; a credit card doesn’t do that, it just moves the same dollar amount onto a product with a much higher rate. I’ve written about what RAP actually guarantees at zero income if you want the details before you call.
- If this is a genuine one-month cash crunch, price the real cost of each option side by side. A processor fee plus a card balance you pay off next month is one number. A servicer’s own late fee, or a short forbearance, is a different number — and forbearance doesn’t touch your credit the way a growing card balance eventually can.
- If you’re chasing a 0% introductory APR offer, do the math before you swipe, not after. The processor’s fee is charged up front, in full, whether or not you pay the balance off during the promotional window. Confirm in writing that you can pay the entire balance before the intro rate ends — if you can’t say that with certainty today, this isn’t the 0% deal it looks like.
- Never let the transaction post as a cash advance. A cash advance starts accruing interest immediately, with no grace period, commonly around 30% APR plus its own separate fee. If a workaround you’re considering involves a “convenience check,” an ATM-style transaction, or anything your card issuer might code as cash rather than a purchase, stop and ask first.
- If your loans are already in default, a credit card doesn’t fix the default — it just adds a second debt. Loan rehabilitation and consolidation exist specifically to get a defaulted federal loan back into good standing without touching your credit cards at all. See what to do if your student loans are already in default, and talk to Damon Day for free before you decide anything.
I Already Put a Student Loan Payment on a Credit Card — Now What?
If you’re reading this after the fact, the card balance is genuinely real and there is no undo button, so the job now is damage control, not regret. First, get the scale right: if you put one payment on the card, only that amount changed character. Your federal loan and every protection attached to it are still there for the rest of the balance — check your servicer account before you assume otherwise. If you paid the loan off entirely, then it really is gone.
- Treat that balance as your highest-priority unsecured debt, not a routine one. It’s carrying a rate the original loan never had, and unlike the loan, nothing about it drops automatically if your income falls.
- If you used a 0% or low-rate promotional offer, mark the exact date it expires and build your payoff plan backward from that date, today. The rate that follows the promo is usually the card’s standard purchase APR — the same 20%+ range as everyone else’s balance.
- Call your card issuer if you can’t make the new payment and ask about a hardship program. These are contractual accommodations the issuer chooses to offer, not a legal right the way federal loan forbearance is — ask plainly what they can do.
- Understand this changes your bankruptcy math, for better and worse. Ordinary credit card debt discharges in a Chapter 7 without you having to prove anything close to the “undue hardship” standard that applies to student loans — a standard that has become far more winnable for federal loans since 2022, and one that some private loans never have to meet at all. But there is a trap on the other side of that, and it runs the opposite way. If you take a credit-card cash advance to make the payment, and your cash advances on that card add up to more than $1,250 within 70 days of filing, federal bankruptcy law presumes that debt is not dischargeable and the burden shifts to you to disprove it — 11 U.S.C. § 523(a)(2)(C), at the dollar figures in force since April 2025 and next adjusted April 2028. It is rebuttable, not an automatic bar, but it puts you on the defensive at the worst possible moment. You have also spent a fee and given up income-driven payments and forgiveness to get there — filing bankruptcy over a balance that RAP might have priced at $10 a month is rarely the better trade. Talk it through before you assume either direction is obviously right.
- Talk to Damon Day for free — DamonDay.com — about whether your next move should be a payoff plan, a balance transfer, or a bigger conversation about all your debt.
When It Makes Sense — and When It Doesn’t
- It can make sense, rarely: you have a genuine 0% introductory APR purchase offer, the amount is small enough that the processor’s fee doesn’t erase the benefit, and you can say with certainty — today — that you’ll pay the full balance before the promotional rate ends.
- It usually doesn’t make sense when: you’re short one month and reach for a card instead of calling your servicer about the Repayment Assistance Plan, an income-driven plan, or a forbearance — all of which exist for exactly this situation and none of which cost you a fee.
- Rethink it entirely when: the transaction would post as a cash advance rather than a purchase. No grace period and roughly 30% APR from day one turns a temporary problem into a worse one immediately.
- What won’t work: assuming your card’s rewards or cash back offset the processor’s fee. A typical 2.5%–3% processing fee usually costs more than the 1%–2% most cards pay back, so you’re paying to move the debt, not earning on it.
The Numbers That Matter
The gap between what a federal student loan costs you and what a credit card costs you isn’t a rounding error — it’s frequently a multiple. And the rate is only part of it. Under the Repayment Assistance Plan that launched July 1, 2026 under the FY2025 reconciliation law, your monthly payment is generally 1%–10% of your income, with a $10 minimum and a reduction for each dependent — and any remaining balance is forgiven after 360 qualifying monthly payments, roughly 30 years, sooner through Public Service Loan Forgiveness for qualifying public-service work. A credit card doesn’t scale to your income in any month, good or bad, and it doesn’t forgive anything.
| Protection or Feature | Federal Student Loan | Credit Card Debt |
|---|---|---|
| Payment tied to your income | Yes — RAP bottoms out at $10/month, and IBR can go to $0 for income at or below 150% of the federal poverty guideline. Compare both before you enrol. (Not available on Parent PLUS.) | No — fixed minimum regardless of income |
| Forgiveness pathway | Yes — RAP (30 yrs), IBR, PSLF (10 yrs public service) | None |
| Discharged if you die | Yes, in full — 34 C.F.R. § 685.212(a) — but not automatically: a family member or estate representative has to send the servicer an original or certified death certificate. Nothing happens until someone does. (FFEL and Perkins loans have their own parallel rules, §§ 682.402 and 674.61.) | No — becomes a claim against your estate; a joint cardholder stays liable |
| Discharged if you become permanently disabled | Yes — 34 C.F.R. § 685.212(b) (TPD discharge). Automatic only if you are picked up in the quarterly Social Security or VA data match; otherwise you have to apply, with a physician’s certification. | None |
| Bankruptcy discharge standard | Depends on the loan. Federal: an “undue hardship” adversary proceeding under 11 U.S.C. § 523(a)(8) — which since the November 2022 DOJ/Department of Education guidance succeeds far more often than the old conventional wisdom claims. Some private loans fall outside § 523(a)(8) altogether and discharge with no hardship showing at all — but the categories are narrower than people hope. A standard private loan taken for tuition at an accredited school is usually a “qualified education loan” and is covered. The ones that commonly fall outside are loans for K–12 tuition, bar-exam and medical-residency loans, loans at unaccredited schools, and amounts borrowed above actual qualified education costs. Ask a bankruptcy attorney which kind you have — do not assume. | Ordinarily dischargeable in Chapter 7 with no hardship showing required |
| How default is collected | Administrative wage garnishment up to 15% of disposable pay without a lawsuit — 20 U.S.C. § 1095a; also tax refund offset. You do get 30 days’ written notice first and can request a hearing to dispute the debt, the amount, or the repayment terms — and a separate rule, 34 C.F.R. § 34.25, lets you get the garnishment reduced by proving financial hardship | Generally requires the creditor to sue and win a judgment first, under state law |
If a bill-pay processor misrepresented its fees, or a credit card issuer misled you about a promotional rate, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, and I remember the exact feeling of wanting a bill to just be gone — not managed, not restructured, gone. A credit card feels like it does that. The student loan balance zeroes out, the servicer stops calling, and for about thirty seconds it feels like you solved something. Debt is math wrapped in emotion, and this is one of the clearest cases I’ve seen of the emotion winning a fight the math should have won. Federal student loans are one of the only debts in this country built with a safety net under them — income-based payments, forgiveness, a clean discharge if you die or can’t work again. You don’t trade that away to save yourself a phone call to your servicer. Make the call first. It costs nothing and it’s usually the better deal.
This one comes down to YOUR income, YOUR loan type, and YOUR timeline. Whether a credit card genuinely makes sense in your case depends on things a general article can’t weigh — how close you are to forgiveness, whether your loans are federal or private, and whether the “emergency” is really a one-time gap or a sign your payment no longer fits your budget. That’s exactly the kind of question I built the free Ask Steve chat for — tell me what’s actually going on and I’ll give you my honest read. It’s free and anonymous, and I sell nothing. Everyone else in debt wants to sell you a solution; I just want you to make the right call for you.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Frequently Asked Questions
Can I pay my student loan directly with a credit card?
Almost certainly not directly. Federal loan servicers’ own payment pages don’t list a credit card as an accepted method — MOHELA’s, for example, lists auto-debit, a one-time online payment, phone payment, a debit card, your bank’s bill-pay service, or a check or money order. Debit card, yes. Credit card, no. The only route onto a card is a third-party bill-pay processor that charges its own fee to accept the card and forward the payment on your behalf.
Will my credit card rewards or cash back make the fee worth it?
Usually no. A third-party processor’s fee is commonly in the 2.5%–3% range, and most cards pay back 1%–2% in rewards or cash back on a purchase. You’re generally paying more in fees than you’d earn back, on top of whatever interest you carry if you don’t pay the card off in full.
What happens to my income-driven repayment plan if I pay off my federal loan this way?
If you pay the balance off entirely, it disappears with the loan — there is no federal student loan left to apply an income-driven plan to. If you only put a payment or two on the card, which is the far more common case, your plan is untouched and your remaining federal balance still sits inside it — you now owe an ordinary credit card balance with a fixed minimum payment that doesn’t move with your income, up or down.
Does paying with a credit card make my debt easier to erase in bankruptcy?
In one narrow, technical sense, yes — ordinary credit card debt is generally dischargeable in a Chapter 7 without the “undue hardship” showing that 11 U.S.C. § 523(a)(8) requires for most student loans. But that only helps you if you actually file bankruptcy, and by the time you’re weighing that you’ve already paid a processor’s fee and given up an income-driven plan that might have priced the same debt at $10 a month with no filing at all. And if you reached for a cash advance to do it, the answer can flip entirely: cash advances totalling more than $1,250 in the 70 days before you file are presumed nondischargeable under 11 U.S.C. § 523(a)(2)(C), so the very move you made to survive the month can follow you into the case. Talk to a bankruptcy attorney before using a cash advance for any payment if filing is a real possibility in the next few months. Don’t use any of this as a reason to convert the debt on purpose — if bankruptcy is genuinely the right move for you, take the 2-minute bankruptcy quiz and talk to an attorney about your full picture, student loans included.
I already put a payment on a cash advance and can’t afford the new bill — what do I do?
Call your card issuer today and ask about a hardship program — it’s a business accommodation they can choose to offer, not a legal right, so ask plainly what’s available. Then talk to Damon Day for free about whether a payoff plan, a lower-rate balance transfer, or a broader look at all your debt makes the most sense from here.
Is a Direct Consolidation Loan the same thing as paying with a credit card?
No, and the difference matters. A Direct Consolidation Loan combines your federal loans into one new federal loan — it stays federal, keeps income-driven repayment and forgiveness eligibility, and doesn’t touch your credit cards at all. Paying with a credit card, by contrast, moves the debt entirely out of the federal system and into an unsecured consumer product with none of those protections.
My loans are already in default — is a credit card a faster fix than dealing with the default?
No. A credit card payment doesn’t fix a default; it just adds a second debt on top of it, usually at a much higher rate. Loan rehabilitation and consolidation exist specifically to bring a defaulted federal loan back into good standing. See what to do if your student loans are already in default before you consider a workaround.
What if my loans are private, not federal — does any of this still apply?
The mechanics are similar, but the trade is different. Most private lenders also don’t accept a credit card directly. And private student loans don’t come with RAP, IBR, or PSLF at all — some are already dischargeable in bankruptcy without the federal hardship standard, depending on how the loan was structured. Read what actually determines whether a private loan qualifies before assuming a credit card is your only move.
One more thing — everything I share here is based on more than 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to your servicer, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Loan terms, servicer rules, and card issuer policies vary, and your situation may have details that change what’s actually best for you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: Call your student loan servicer about the Repayment Assistance Plan, an income-driven plan, or a forbearance before you call a bill-pay processor about a credit card. A federal student loan comes with protections — income-based payments, forgiveness, a clean discharge if you die or become disabled — that a credit card simply doesn’t have, and for whatever share of the debt you convert, they are gone for good. Not sure where your situation lands? Find Your Path in two minutes.
The Bottom Line
Wanting a bill to just disappear doesn’t make you reckless with money — it makes you human, especially when a servicer’s phone tree feels like the last thing you have energy for this week. The smart move isn’t the one that makes the balance vanish from one statement fastest. It’s the one that keeps the protections you already have. If someone you know is eyeing a credit card to make a student loan payment go away, send them this page — the phone call to their servicer costs nothing and usually beats the card. Then see how all your debt relief options compare and Find Your Path.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 9): The paycheck advance app said it wasn’t a loan. Connecticut just made it give every fee back.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



