

Quick Answer: Credit card hardship help is often triggered by your account status, not by how responsibly you behave — the Consumer Financial Protection Bureau’s own advice says to call your card company “immediately,” and its wording leaves room for a gap: it says “many,” not all, card companies will work with you, and in my 30 years watching this industry, I’ve seen plenty of current, on-time customers get told to call back once they’re behind. That is not a verdict on your character — and it is not a guarantee either way, because going delinquent on purpose can mean a closed account and a credit-report mark that lasts years, with no promise you’ll get anything back for it. The smartest move is to get the specific rules from your own creditor in writing before you decide anything.
Where This Comes From: Conversations in my free Ask Steve chat keep raising versions of this same situation — someone did everything the guidebooks say to do, called their card company before they missed a payment, and got told to call back once they were behind. I’m not sharing any personal details here, just the pattern, because I’ve now seen it often enough to know it isn’t one unlucky phone call. If you’re staring down a similar decision, you can ask your own question in Ask Steve — it’s free, private, and nothing is for sale.
Expert Context: I ran a credit counseling organization for over a decade and sat across the table — sometimes literally — from card issuers’ hardship and loss-mitigation desks. I know how those internal rules are actually built, and it isn’t around your honesty or your effort. It’s around your account status.
Dealing with your creditors is not a morality test. It is a business process, and inside that process you are a line item in someone else’s loss-mitigation model. Once I understood that, the guilt I used to feel about “not doing enough” for my creditors mostly evaporated — because they were never grading me on effort. They were pricing risk. That’s really the whole thesis of why I keep saying debt is math wrapped in emotion: the math doesn’t care how you feel about it, and neither does a loss-mitigation desk. So the decisions that serve you best are the ones made with that fact in view, not in spite of it.
The Word the Government Leaves Out
The CFPB’s guidance on credit card trouble is genuinely good, and I don’t want to talk anyone out of following it. It tells you to “contact your credit card company immediately” the moment you know you’re in trouble, and to be ready to explain why you can’t pay the minimum, how much you can afford, when you could restart normal payments, and what new payment amount you’re requesting and for how long. That’s solid, practical advice. Follow it.
The Claim: If you do the responsible thing and call your card company before you miss a payment, they’ll work out a hardship plan with you.
The Reality: The CFPB’s own page stops short of promising it — its exact wording is that “many card companies are willing to work with you to change your payment if you’re facing a financial emergency.” Not all. Many. That single word leaves room for a gap — and in my own experience, watching this play out over and over from inside the industry, a lot of issuers’ hardship programs are, in practice, keyed to a delinquency trigger, so the caller who is still current often gets told, politely, that there’s nothing to offer yet.
I want to be careful here, because this isn’t a conspiracy and it isn’t the CFPB being dishonest. It’s a plain description of an imperfect system. Loss-mitigation departments exist to manage the issuer’s risk, and in my experience many of them are built to activate once an account crosses into delinquency — not before. A representative on the front line usually can’t override that. They’re reading from the same script whether the caller is a stranger to the desk or one they’ve spoken to five times.
Why the Responsible Call Doesn’t Always Unlock Help
Here’s the part that took me years inside the business to really internalize: your card company’s hardship rules are not a referendum on your character. They are a workflow, and workflows react to codes, not to intentions. A person who calls the day they realize they’re in trouble and a person who calls after three missed payments are, to that workflow, in different queues — and in my experience, the queue with more options is very often the one that requires missing the payment first.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
That is a genuinely strange incentive to build into a system built around “responsible” behavior, and I don’t think most issuers set out to design it that way on purpose. But it’s the reality a lot of people run into, and it’s worth naming plainly instead of letting someone quietly conclude they did something wrong.
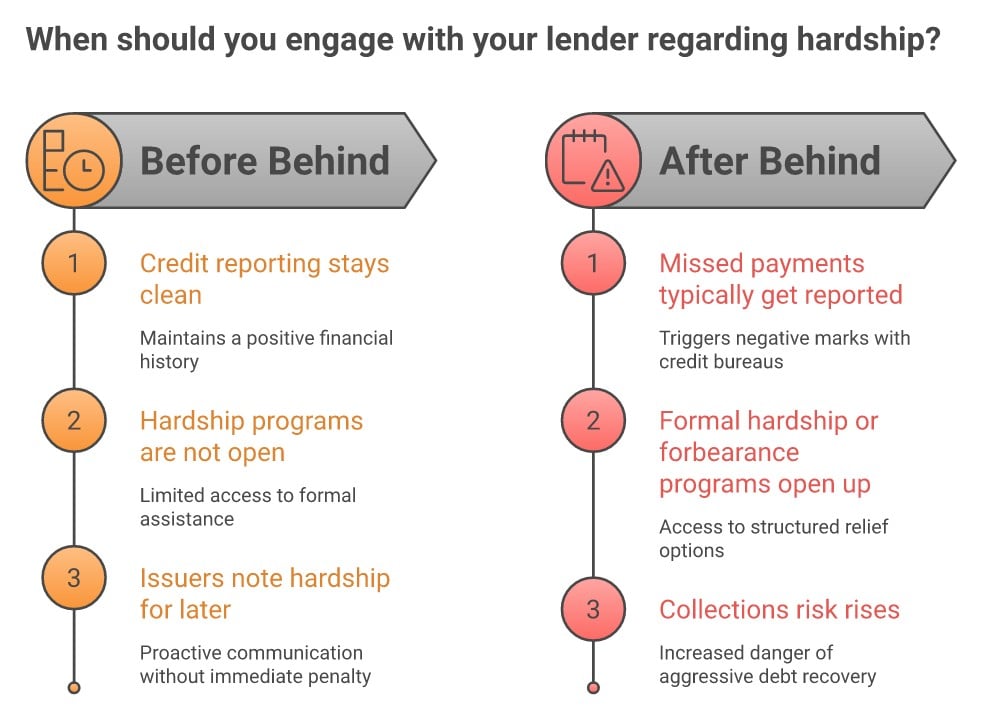
What Changes If You Fall Behind — And What It Costs to Get There
While You’re Still Current
- Many issuers will still discuss a payment date change or a short-term due-date shift
- Some issuers do have proactive hardship lines — ask directly whether yours does
- Your credit report stays clean, and your card stays open and usable
Once You’re Behind
- Your issuer very often closes the account or cuts your credit line
- A missed payment reports as a large, long-lived mark on your credit file — not a minor blip
- Around 180 days past due, the account is typically charged off and frequently sold to a debt buyer
- Formal hardship or forbearance programs may open up — but only if the issuer offers them, and that is never guaranteed
Here’s the part too many people miss: going delinquent does not guarantee you get anything. You can pay the entire price of missing a payment — the late mark, the closed account, the collections calls — and still be told no, or offered something worse than what you already had. Nothing about this trade is guaranteed in your favor, in either direction.
And here is my honest read after more than 30 years of watching this from both sides of the desk: for most people, this trade loses. The credit damage, the collections risk, and the real chance you get nothing back are usually bigger, and far less reversible, than the hardship benefit you were hoping to unlock — which is exactly why it’s worth knowing what going delinquent actually costs, in specifics, before you ever decide.
Here’s what going delinquent on purpose actually costs, in specifics: your issuer often closes the account or cuts your credit line, and for a lot of people that card is real, immediate cash-flow room that’s now gone. A 30-day late payment reports as a single, large, long-lived mark on your credit file. Around 180 days past due, issuers commonly charge off the account, and the tradeline can sit on your credit report for roughly seven years. Once it’s charged off, it’s frequently sold to a debt buyer — a different company with no memory of any hardship conversation you had with the original issuer, and no obligation to honor it. You may also lose a promotional interest rate and get hit with a penalty APR, independent of whatever hardship deal you were hoping for. And none of it is reversible: you can pay every one of these costs and still be told no.
What I Am Not Telling You To Do: I am not telling you to stop paying your credit card on purpose to unlock a hardship program. Decide with your eyes open, using the actual rules your creditor will give you if you ask — not by drifting into delinquency by accident, and not by staying current out of guilt while quietly draining your savings to do it.
What I’ve Watched Cost People More Than the Debt Itself
Over more than 30 years of doing this work, I have watched people — often people who did everything “right” — empty a savings account or raid a retirement fund to stay current with a creditor, purely because staying current felt like the responsible, moral thing to do. Some of them land in the exact same financial hole a year later anyway, minus the cushion that would have carried them through it. That’s the expensive part of treating a business decision like a morality test: the cost isn’t just the interest. It’s the safety net you burned trying to prove you were a good person.
I’ve also watched the opposite play out with people close to retirement — people in their late fifties and early sixties who lost a job or a source of income at the worst possible time to rebuild, and who felt enormous shame about falling behind on cards they’d paid on time for decades. That shame is not earned. Losing income is not a character flaw, and neither is needing your creditor’s hardship program to actually be a hardship program instead of a reward for having already suffered enough to qualify.
And there is one asymmetry worth more than anything else on this page: everything in that right-hand column is still available to you next month, but nothing in the left-hand column comes back once you cross. Delinquency is a one-way door. Staying current today keeps the option to go late later, with better information than you have right now — which is a reason to hold, not a virtue to claim.
None of this means staying current is a mistake. For most people who can actually afford the payment, staying current is exactly the right call — it protects your credit and keeps the account open. The trap isn’t staying current. It’s staying current when you truly cannot afford it, purely out of guilt, while your savings quietly disappears to make it happen.
What I’d Ask For If I Were You
Whatever you decide, decide it deliberately — not by accident, and not out of guilt. Here’s what I’d want in hand before making the call:
- Ask what’s available to you right now, while you’re current. Ask the representative directly: “What hardship or payment-relief options can I access today, without missing a payment, and what documentation do you need from me?” You can ask for a clear answer, even if you can’t demand one.
- Get any offer in writing before you accept it. A verbal promise from a call center isn’t something you can hold them to later. Ask for written confirmation of the terms before you change your payment behavior based on them — but once you accept a written offer, that acceptance can create real obligations for both of you.
- Ask exactly how the arrangement will be reported to the credit bureaus. “Current, paying as agreed” and “delinquent” report very differently, and the difference matters for months or years afterward.
- Ask what happens to your interest rate, your minimum payment, and your term. A hardship arrangement that quietly stretches your payoff by years, or resets to a high rate the moment you miss one payment, is not the deal it looks like on the phone.
- Weigh the real cost of going delinquent on purpose. Credit score damage, possible collections contact, and in some cases a lawsuit are genuine risks, not scare tactics — see my explainer on what your creditor already expected before you missed a payment for how that risk pricing actually works.
None of that is complicated, but almost nobody asks those five questions on a stressed phone call, because a stressed phone call is not when most people think clearly. That’s exactly why I’m putting them here, in writing, before you’re ever on the phone. If you want the fuller picture first, read my full explainer on what credit card hardship programs actually cover.
If your income has dropped for reasons bigger than one missed payment — a layoff, a strike, a medical event — the calculation gets bigger than one card. I’ve written a broader breakdown of what to do across all your creditors before a temporary income gap turns into missed payments everywhere.
Before you agree to anything, it’s worth knowing that not every path that sounds gentler is actually gentler on your credit once you look at the data.
And if you’re weighing your card issuer’s own hardship program against going through a third party, here’s a closer look at how a card issuer’s own hardship program compares to going through a third party.
Key Takeaways
- The CFPB’s own advice leaves room for a gap with one word: “many,” not all, card companies are willing to work with someone facing a financial emergency.
- Hardship rules react to your account status, not to your honesty or effort — that is a workflow design, not a judgment of your character.
- Going delinquent on purpose does not guarantee help — you can pay the full price of a missed payment and still be told no.
- For most people, going delinquent on purpose loses: the credit, collections, and charge-off costs are usually bigger and far less reversible than the benefit.
- If you can actually afford your payment, staying current is still the right call for most people — it’s staying current out of guilt you can’t afford that costs people their savings.
- Ask what help exists for you today while you are current, get any offer in writing, and ask specifically how it reports to the credit bureaus before you agree to anything.
The Bottom Line
If you called your card company before you missed a payment and got told to call back once you were behind, you didn’t fail — you ran into a workflow that wasn’t built to reward the responsible move you made. You are not your debt, and you are not the rules your creditor’s software runs on. Run your own numbers the same way they run theirs: with information instead of guilt, and with your future — not your shame — driving the decision. I filed bankruptcy myself in 1990 and rebuilt from a much harder starting point than a hardship call. Whatever you decide with your creditors, decide it as your own advocate, not as someone waiting to be judged.
Frequently Asked Questions
Should I call my credit card company before or after I miss a payment?
Call before, following the CFPB’s own advice — it’s still the right first move and some issuers do have proactive hardship options. Just go in knowing that many issuers’ formal hardship programs are, in my experience, keyed to delinquency, so “call immediately” may get you a note on file rather than an active plan. Ask directly what is available to you right now, while you are current, and what documentation they want from you.
What exactly should I ask for when I call about hardship help?
Ask what’s available to you right now while you’re still current, get any offer in writing before accepting it, ask exactly how the arrangement will be reported to the credit bureaus, and ask what happens to your interest rate, minimum payment, and repayment term. A verbal promise on a recorded line isn’t something you can hold them to later.
Will a credit card hardship arrangement hurt my credit score?
It depends entirely on how the issuer reports it, which is exactly why you need to ask before you agree to anything. Some hardship arrangements report as “paying as agreed,” others report the account as modified or delinquent. Never assume — ask the specific reporting language for the specific offer in front of you.
Should I stop paying my credit card on purpose to qualify for hardship help?
No. Going delinquent on purpose carries real risk — a closed account, a credit-report mark that can sit on your report for roughly seven years, possible collections contact, and in some cases a lawsuit — and none of that guarantees you’ll get help in return. The point of this piece is not “stop paying to get help.” And my honest read after 30 years is that for most people this trade loses — the costs are bigger and far less reversible than the help you were hoping to unlock, and going late is a one-way door you cannot reopen once you walk through it.
Is it my fault if my card company will not help me until I am behind?
No. That is a description of how many loss-mitigation workflows are built, not a verdict on your honesty or your effort. You are not your debt, and being told to call back once you are behind is information about their process — not about your character.
This is what I’m seeing and what I’d tell my own family — but you’re the only one who knows your full situation. Take my advice as input, not instruction. Don’t let anyone, including me, tell you what to do with your money.
If this made sense to you, send it to someone who’s staring at a credit card bill right now feeling like they’ve failed somehow. They haven’t. Sometimes knowing the rules of the game is the thing that changes everything.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research found that people who filed for bankruptcy saw their credit scores recover faster than similarly insolvent people who never filed — one quarter on, the filers’ scores ran 40 to 80 points higher.



