

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed September 1, 2026 • Every claim below links to a primary source.
The verdict: Partly true — and which part depends entirely on the bankruptcy chapter. If your cosigner (or co-borrower) files Chapter 7 and discharges the debt, you are still fully and immediately liable for the whole balance — that part of the myth is a flat Myth. If they file Chapter 13, federal law gives you a temporary shield called the co-debtor stay while their case is active — but it isn’t permanent and it comes with real exceptions, so believing it means you’re “off the hook” is only Half True. Under 11 U.S.C. § 524(e), a bankruptcy discharge only ever protects the person who filed — never a cosigner. There is one narrow carve-out for a filer’s spouse in a community-property state, covered below — but it protects certain property from collection; it does not release that spouse’s personal liability.
Well, Actually…
I hear a version of this question constantly, from both directions: “My ex cosigned my car loan and just filed bankruptcy — does that wipe out my share too?” and “I cosigned for my kid, and now I’m filing — does my bankruptcy get them off the hook?” The honest answer disappoints almost everyone who asks it, because a bankruptcy discharge is a personal shield, not a debt eraser. The law that governs this, 11 U.S.C. § 524(e), says it plainly: “Except as provided in subsection (a)(3) of this section, discharge of a debt of the debtor does not affect the liability of any other entity on, or the property of any other entity for, such debt.” The debt itself doesn’t disappear. Only the filer’s personal responsibility for it does. And read that opening exception carefully, because it is narrower than it looks: § 524(a)(3) is an injunction protecting property — specifically community property acquired after the case is filed — from being collected against. It does not release anybody’s personal liability. It bites the property half of that sentence, not the liability half.
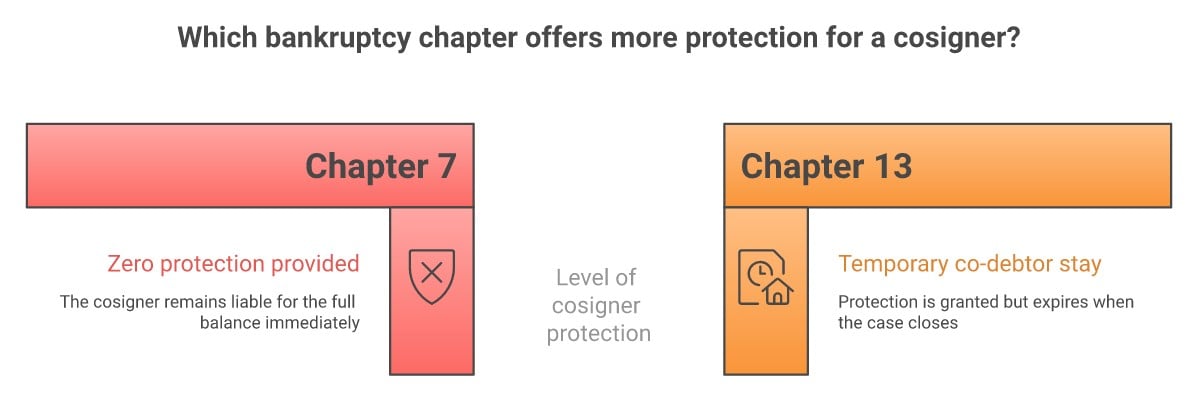
For nearly every cosigner, that’s the whole rule for Chapter 7 — no waiting period, no fine print that helps you. There’s one narrow, genuine exception, and it protects property — not you: if the person who filed is your spouse and you live in one of the nine community property states (Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, or Wisconsin — Alaska also lets spouses opt into community property by written agreement, so ask if one exists), you remain fully and personally liable, but § 524(a)(3) blocks a creditor from reaching community property acquired after the case was filed — the kind the bankruptcy estate could have reached — on a debt that counts as a community claim under your state’s law. It doesn’t touch your separate property, community property from before the filing, or — after a later divorce — your own separate earnings, and it doesn’t apply at all to a debt that would be excepted from discharge under § 523. And separately from all of that, § 524(b) describes narrower situations in which this property protection never arises at all. Outside that specific situation, Chapter 13 is where the myth gets its grain of truth. Congress built a real, if temporary, protection into Chapter 13 called the co-debtor stay, at 11 U.S.C. § 1301. While a Chapter 13 case is open, a creditor generally cannot chase a cosigner on a consumer debt — one incurred “primarily for a personal, family, or household purpose” — while the debtor’s plan is running. That’s real relief. It is not, however, the same thing as the debt being gone. The moment the case closes — whether the debtor finishes the plan and gets a discharge, or the case is dismissed or converted — the stay ends and whatever balance is left becomes the cosigner’s problem again.
Three more things people miss. First, the co-debtor stay isn’t automatic-and-untouchable: a creditor can ask the court to lift it, and the court must grant that request if the cosigner was really the one who got the benefit of the loan, if the debtor’s plan doesn’t propose to pay that debt at all, or if continuing the stay would irreparably harm the creditor’s interest — that’s the actual statutory bar, and it’s a high one, not just general inconvenience. Second, it only covers consumer debt — if your cosigner backed a business loan for you, or you cosigned in the ordinary course of your own business, the stay never applies at all. Third, the stay only protects an individual codebtor — if the co-signer on your loan is an LLC or a corporation rather than a person, there’s no stay to lose (§ 1301(a)-(c)).
“My cosigner filed Chapter 7 and the loan got discharged — so I don’t owe it anymore either.”
Chapter 7 has no codebtor stay — the automatic stay under 11 U.S.C. § 362(a) protects the debtor and the bankruptcy estate, not a cosigner as such. (One narrow wrinkle: if the filer is your spouse in a community-property state, community property becomes part of the bankruptcy estate and gets a temporary shield from § 362(a) while the case is open — see the community-property exception explained above. That’s a shield for property, not a release of your liability, and it doesn’t apply outside that specific situation.) The discharge order releases only the filer’s personal liability. As § 524(e) states, the discharge “does not affect the liability of any other entity” on that debt — and the community-property carve-out does not change that, because it shields property rather than releasing liability. The lender can — and routinely does — turn to the cosigner for the full remaining balance starting the day the case is filed, not when it closes; outside the community-property exception, there’s no quiet period while the filer’s case is pending. You owe the entire remaining balance, not a negotiated “half” — cosigner liability was never split between the two of you in the first place.
“My cosigner filed Chapter 13, so the debt is permanently off my plate now.”
Real, but temporary and conditional. 11 U.S.C. § 1301‘s co-debtor stay pauses collection against you on a consumer debt while the Chapter 13 case is active — but it ends automatically when the case closes, dismisses, or converts, it never covers business debts, and a creditor can ask a judge to lift it early if you (not the filer) actually got the money, or if the plan isn’t paying that debt. “Collectors stopped calling” is not the same fact as “I’m permanently released.”
Why You Were Told This
Two honest reasons this myth spreads. First, bankruptcy really does say the word “discharge,” and most people reasonably assume a discharged debt is simply gone — for everyone attached to it. It isn’t; it’s gone for one specific person, the filer, and the statute exists precisely because Congress anticipated people would assume otherwise. Second, in a Chapter 13 case the phones genuinely do stop ringing for the cosigner while the co-debtor stay is in effect — and it’s human nature to read silence as “solved.” Nobody sends the cosigner a reminder that the clock is still running. The bankruptcy attorney in the case represents the person who filed, not you — so if you’re the cosigner, there is no lawyer in that courtroom whose job is to warn you.
There’s also a second trap worth knowing about, on top of everything above — a different way your cosigner’s bankruptcy filing can hit you. In 2014, the CFPB documented that many private student loan contracts let the lender demand full immediate repayment from the borrower the moment a cosigner files bankruptcy — even on a loan that was current. Congress banned that specific practice going forward: under 15 U.S.C. § 1650(g)(1), a private student loan lender may not declare a default or accelerate the debt against the borrower “on the sole basis of a bankruptcy or death of a cosigner” — but only for loans taken out on or after November 20, 2018. If your private student loan predates that, the contract term the CFPB documented may still be enforceable, which makes requesting a cosigner release — before a bankruptcy filing can trigger the clause — the safer move either way.
What to Actually Do
- If your cosigner just filed Chapter 7, treat the whole balance as now yours to manage. Get the payoff amount from the lender in writing and don’t wait for a bill — the account may not show up on your radar until it’s already delinquent.
- If your cosigner filed Chapter 13, mark the case’s expected close date — and watch for an early termination. The federal court’s PACER system (free to register, small per-page fees) shows the case docket. The stay ends no later than the day the case closes, dismisses, or converts — but it can end much sooner: if a creditor asks the court to lift it because the plan doesn’t propose to pay your debt, § 1301(d) terminates the stay automatically 20 days later unless you or the filer files and serves a written objection. Nobody is required to remind you that clock is running.
- Ask what the Chapter 13 plan actually proposes to pay on that specific debt. If the plan pays it in full, you may genuinely be covered once it’s done — though a plan pays the claim as it stood on the filing date, so interest that kept accruing on your separate contract with the lender can still land on you. If it pays a fraction (common for unsecured debt) or nothing, you’ll owe the rest the moment the stay lifts.
- If you’re the one filing and you want to protect your cosigner, say so to your attorney before you file. A Chapter 13 plan may be allowed to classify and pay a cosigned consumer debt differently than your other unsecured debts — often a higher percentage, sometimes in full — under 11 U.S.C. § 1322(b)(1), subject to the judge approving that classification, or in Chapter 7 you can reaffirm a secured debt like a car loan — but reaffirmation requires the lender’s agreement too and has to be signed before your discharge is entered, and each option has real tradeoffs for you. Get advice specific to your case rather than assuming any one path is automatically the kind thing to do.
- Get your own advice as the cosigner. The bankruptcy attorney in the case works for the filer, not you. A short consult with your own attorney (many offer free initial calls) can tell you exactly where you stand and whether the co-debtor stay even applies to your debt.
Steve’s Take
In 30-plus years of watching bankruptcy filings, this is one of the most expensive misunderstandings I see — and it cuts both ways. I’ve talked to people who stopped worrying about a cosigned loan the day their ex filed Chapter 7, and got a collection notice for the full balance eight months later. I’ve also talked to people who assumed a Chapter 13 co-debtor stay meant “forever” and never budgeted for the balance that came due the day the case closed. Bankruptcy law protects the person who signed up for the protection — it was never designed to sweep up everyone connected to a debt. If you’re a cosigner and someone else’s bankruptcy just entered the picture, don’t guess. Get the actual case chapter, the actual plan terms if it’s a 13, and your own advice. That’s the difference between being surprised and being ready.
Frequently Asked Questions
Does Chapter 7 bankruptcy ever protect a cosigner, even temporarily?
Almost never, and not in the way people hope. Chapter 7 has no codebtor stay — the automatic stay under 11 U.S.C. § 362(a) protects the debtor and the bankruptcy estate, not a cosigner as such — so the lender can pursue you for the full balance from the day the case is filed, not just after it closes. The one narrow exception: if the filer is your spouse in a community-property state, see the community-property carve-out explained above — and even there, you remain personally liable the whole time. Outside that specific situation, when the filer’s discharge is later entered, 11 U.S.C. § 524(e) makes clear it only released the filer — it changes nothing about your exposure.
What exactly is the Chapter 13 “co-debtor stay,” and how long does it last?
It’s a court-ordered pause on collection against a cosigner, created by 11 U.S.C. § 1301, that applies only to consumer debts while the Chapter 13 case remains open. It ends no later than the day the case closes, is dismissed, or is converted to Chapter 7 or 11 — and it can end earlier if a court lifts it for cause or an unopposed creditor request runs its 20-day clock.
Can a creditor still go after the cosigner while the Chapter 13 case is active?
Yes, if a court lifts the stay. Under § 1301(c), a judge must grant relief from the stay if the cosigner actually received the benefit of the loan, if the Chapter 13 plan doesn’t propose to pay that debt, or if continuing the stay would irreparably harm the creditor’s interest — the actual statutory bar, and a high one.
What happens to the cosigner once the Chapter 13 case ends?
Whatever the plan didn’t pay on that debt becomes collectible against the cosigner again. If the plan paid the debt in full, there’s little or nothing left to collect — though a plan pays the claim as it stood on the filing date, so interest that kept accruing on your own contract with the lender can still be outstanding. If the plan paid a partial amount — common for unsecured debt in a Chapter 13 case — or didn’t cover it at all, the remaining balance is fully the cosigner’s responsibility, exactly as it would be after a Chapter 7 case.
I’m the one filing — can I do anything to protect my cosigner?
Sometimes, but it depends on your case and the debt. You can ask your attorney about classifying and paying that specific debt differently — often in full — through a Chapter 13 plan (11 U.S.C. § 1322(b)(1), subject to the judge approving the classification), or reaffirming a secured debt like a car loan in Chapter 7 — though reaffirmation also requires the lender to agree and must be signed before your discharge is entered. Each option changes what you owe and give up, so it isn’t automatically the right move. This is a conversation to have with your attorney before you file, not something that happens by default.
Does this only apply to loans, or does it cover things like credit cards and medical bills too?
It applies to any debt where a second person is legally obligated — jointly held credit cards, cosigned auto and personal loans, and cosigned private student loans all work the same way under § 524(e) and § 1301. The dividing line for the Chapter 13 stay is whether the debt is a “consumer debt” — incurred primarily for personal, family, or household purposes — not what kind of account it is.
How is this different from what happens if I’m the one who cosigned and I’m the one filing?
That’s the reverse question, and the answer is the mirror image of everything above: a debt you cosigned is your debt too, so your own bankruptcy discharges your personal liability on it, the same as it would any other debt you owe (11 U.S.C. § 524(a)). What your bankruptcy does not do is release the primary borrower, or strip a lien off collateral — the debt keeps existing for them, just like it keeps existing for a cosigner when the roles are reversed. (The main wrinkle: a cosigned private student loan can survive your own bankruptcy under § 523(a)(8) unless you show undue hardship — but only if it qualifies as a “qualified education loan” under § 523(a)(8)(B). A private loan that doesn’t meet that definition — one that exceeded your cost of attendance, or went to an ineligible school or a non-degree program, for example — falls outside § 523(a)(8) entirely and discharges like any other unsecured debt, no hardship showing required.) I cover that direction, and general cosigner liability from day one, in They Said Cosigning Is Just Vouching and Cosigner Debt in Bankruptcy: What Happens. This post answers the opposite question — what happens to you when the other person on the loan files.
The borrower I cosigned for just stopped paying — what do I do right now, today?
This post explains the law behind your situation; if collectors are already calling and you need an immediate action plan, go read I Cosigned a Loan and They Stopped Paying: Here’s What to Do Right Now. It walks through validating the debt, protecting your credit, and deciding your next move today — this post is the deeper explanation of the § 524(e) and § 1301 rules behind that advice.
This is one informed perspective after over 30 years of watching how these cases actually play out — take it as input for your decision, not the decision itself. Bankruptcy chapter, plan terms, and state law all change the details of your specific situation. Only an attorney who has seen your paperwork can tell you exactly where you stand.
The bottom line: A cosigner’s bankruptcy discharges their liability, never yours — Chapter 7 offers essentially no protection to a cosigner (in a community property state one narrow carve-out shields certain property of the filer’s spouse from collection — it still does not release the spouse’s personal liability), and Chapter 13’s co-debtor stay is real but temporary, ending no later than the day the case closes and often sooner. If someone you know is counting on a cosigner’s bankruptcy to erase their own share of a debt, send them this before they stop budgeting for it.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



