
Quick Answer: The Bible does not condemn bankruptcy. Scripture explicitly mandates debt release — Deuteronomy 15:1-2 required creditors to cancel debts every seven years, and Leviticus 25 established a complete economic reset every fifty years. Jesus taught debt forgiveness as a virtue, not a failure. And 43 U.S. Catholic religious organizations have filed for bankruptcy protection when their debts became unmanageable, including the Diocese of El Paso in 2026. The shame directed at individuals considering bankruptcy has no biblical foundation — and the institutions directing that shame use bankruptcy themselves.
Why I Know This Firsthand: I filed bankruptcy in 1990 after my real estate business collapsed. I sat in that courtroom carrying what felt like a moral verdict, not a financial one — because that’s exactly how the culture framed it. I’ve spent 30 years helping people with debt, and the single most destructive force I’ve encountered isn’t high interest rates or predatory lenders. It’s religious shame that keeps people in financially ruinous situations for years while they convince themselves they’re doing the godly thing. I studied the scripture. The shame is manufactured. The Bible says something completely different.
Table of Contents
Islamic View of Debt: An Imam’s Perspective
Islam prohibits interest but provides debt relief through Zakat and teaches that debtors who genuinely cannot repay may have obligations forgiven. A different faith tradition, the same principle: debt forgiveness is divine.
If you’ve been told that filing bankruptcy is ungodly, un-Christian, or a failure of faith — the people telling you that are wrong. Not slightly wrong. Fundamentally wrong. And the same institutions promoting that message have been quietly filing Chapter 11 themselves for decades.
This is the most complete answer I can give you on what the Bible actually says about bankruptcy, where the shame came from, and why the math of your situation matters more than someone else’s interpretation of ancient texts.
Key Terms Defined
The Sabbath Year / Shemitah: A seven-year cycle mandated in Deuteronomy 15. At the end of every seventh year, creditors were required to release debtors from their obligations. This was not optional — it was law.
The Year of Jubilee: Leviticus 25 established a fiftieth-year reset: all debts cancelled, all indentured servants freed, all land returned to original owners. God’s economic system built in a mandatory fresh start at scale.
Chapter 7 bankruptcy: Liquidation bankruptcy — most unsecured debts discharged. Available once every eight years under U.S. law, mirroring the seven-year biblical cycle.
Chapter 11 bankruptcy: Reorganization bankruptcy used by businesses, churches, and municipalities. Debts restructured under court supervision while operations continue.
Automatic stay: The immediate legal protection that stops all collection actions, lawsuits, and garnishments the moment a bankruptcy petition is filed.
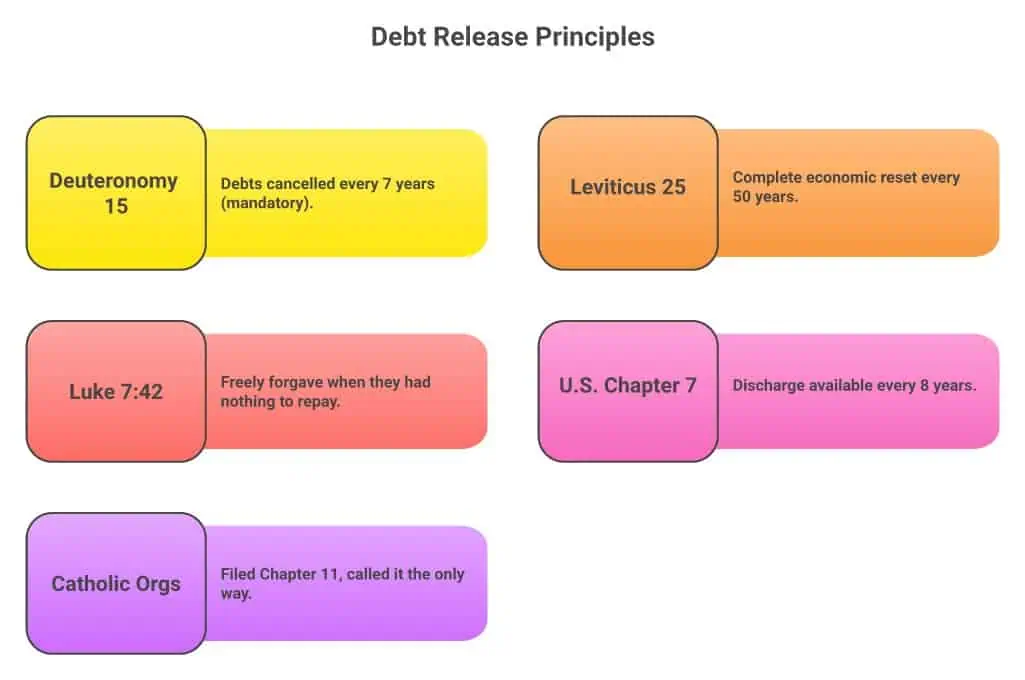
What the Bible Actually Says About Debt and Release
Let’s go directly to the text, because the people promoting bankruptcy shame rarely quote it accurately.
Deuteronomy 15:1-2: “At the end of every seven years, you shall grant a release of debts. And this is the form of the release: Every creditor who has lent anything to his neighbor shall release it; he shall not require it of his neighbor or his brother, because it is called the LORD’s release.”
That is not a suggestion. That is a command from the same God whose authority is cited by the people shaming you for considering bankruptcy. The seven-year debt release — the Shemitah — was mandatory, recurring, and divinely ordained. The lender had no right to object.
Leviticus 25:10: “And you shall consecrate the fiftieth year, and proclaim liberty throughout the land to all its inhabitants. It shall be a jubilee for you; each of you shall return to his own property, and each of you shall return to his family.”
The Year of Jubilee went further than the Shemitah. Every fifty years, all debts were cancelled, all indentured servants freed, all land returned. It was a complete economic reset, designed specifically to prevent permanent debt bondage. God didn’t just permit this — God commanded it.
Proverbs 22:7: “The rich rules over the poor, and the borrower is slave to the lender.”
This verse is frequently quoted to shame debtors. What it actually says is that debt is bondage — and breaking free from bondage is the biblical ideal, not a moral failure. The Jubilee existed precisely because this verse is true.
Matthew 6:12: “Forgive us our debts, as we also have forgiven our debtors.”
Jesus used debt as the central metaphor for forgiveness in the Lord’s Prayer. The Greek word used — opheilema — refers to literal financial debt as well as moral obligation. Debt forgiveness is woven into the core of Christian theology.
What You’ve Been Told: “The Bible says you must repay everything you borrow. Filing bankruptcy violates your word and dishonors God.”
What Scripture Actually Says: God mandated debt cancellation every seven years (Deuteronomy 15), full economic reset every fifty years (Leviticus 25), and taught debt forgiveness as a divine virtue (Matthew 6, Matthew 18). The concept of a fresh start is not a loophole — it is the architecture of the biblical economic system. American bankruptcy law, with its eight-year discharge cycle, is closer to the biblical model than “grind for five years and shame anyone who can’t” is.
Jesus’s Two Parables About Debt Forgiveness
Jesus used debt — literal financial debt — as the illustration in two major parables. Neither ends with the debtor grinding out repayment. Both end with forgiveness.
Matthew 18:21-35 — The Unmerciful Servant: A servant owed a king an astronomical sum (ten thousand talents — the equivalent of a lifetime’s wages). The king forgave the entire debt. The servant then refused to forgive a fellow servant a small amount. The parable’s moral point is radical: forgiveness of overwhelming debt is the model, not the exception, and extending that forgiveness to others is the obligation.
Luke 7:36-50 — The Two Debtors: “A certain creditor had two debtors: one owed five hundred denarii, and the other fifty. When they could not pay, he cancelled the debt of both.” Jesus used this cancellation as the illustration of divine grace. The debtor who had more forgiven loved more in return.
“And when they had nothing with which to repay, he freely forgave them both” (Luke 7:42).
“When they had nothing with which to repay, he freely forgave them both.”— Luke 7:42
That is the biblical model of debt resolution for people who cannot pay. Not shame. Not a five-year repayment plan that leaves you financially unsafe. Forgiveness.
Free Tool — Your Brain on Debt Quiz: Fear, shame, and panic don't just make debt harder — they actively drive people toward bad decisions. The free Your Brain on Debt Quiz identifies which emotional driver is in control of your financial choices right now. Take the Quiz →
The Institutional Double Standard
Here is the part that nobody who promotes bankruptcy shame wants to address directly.
According to research tracked by Penn State Dickinson Law, 43 U.S. Catholic religious organizations had filed Chapter 11 bankruptcy protection as of December 2025. The Diocese of El Paso filed in March 2026, citing “astronomical” potential judgments it described as having “no other option” to address. Bishop Mark J. Seitz called bankruptcy “the only way, with the resources at hand.”
These are institutions that have, in many cases, told their congregations that bankruptcy represents a moral failure. Then they filed themselves.
What Institutions Call It When They File
- “The only way to address our obligations equitably”
- “Protecting our mission and ministries”
- “Responsible stewardship of resources”
- “A court-supervised reorganization”
- “The right financial decision given our circumstances”
What They Call It When You File
- “A failure to honor your word before God”
- “Not a biblical option”
- “Running away from your obligations”
- “What the world does, not what Christians do”
- “A moral failure that will follow you forever”
I’m not saying the Catholic Church, or any denomination, is conspiring against debtors. What I am saying is that the double standard is real, documented, and should fundamentally change how you receive advice about bankruptcy from religious sources. The tool they use when their math breaks down is the same tool available to you. The shame they attached to it for individuals has no more biblical basis than their own institutional filings do.
For the full documented history of church bankruptcies, read: Why Do Churches Keep Filing Bankruptcy?
Where the Shame Actually Came From
If scripture supports debt release and institutions use bankruptcy freely, the obvious question is: where did the religious shame around personal bankruptcy come from?
It was manufactured. Not by God. By people with a financial interest in keeping debtors paying.
The credit industry, the debt settlement industry, and certain financial media personalities have all benefited enormously from the belief that bankruptcy is a moral failure reserved for people who lack character. That belief keeps people making minimum payments for years, generating interest revenue. It keeps people in debt management plans at fees. It keeps people listening to radio shows that sell financial products.
I documented this history in detail — the specific campaigns, the advertising, the rhetoric that built shame into the cultural conversation around debt — in How Bankruptcy Stigma Was Manufactured. The short version: the shame is a product, not a principle. And it was sold to you by people who profit from your reluctance to use the legal tool God’s own economic law invented.
What the Data Says About People Who File
Beyond the theological argument, the empirical evidence is unambiguous. A Federal Reserve Bank of New York study found that people who filed bankruptcy were measurably better off financially within two to three years compared to people in similar debt situations who did not file. Credit recovers faster than most people believe. The fresh start is real.
The people telling you bankruptcy will ruin your financial life forever are either uninformed or have a financial interest in your continued debt payments. The data does not support their claim.
What Christian Debt Advice Usually Gets Wrong
There is an entire industry of “Christian debt advice” built on religious branding — organizations and advisors who use faith language to sell the same debt management products available everywhere else. Most of them steer clients away from bankruptcy regardless of whether it’s the right financial choice, because they make money on the debt management plan, not the bankruptcy discharge.
I covered this in depth in Christian Debt Advice: Myth vs Reality. The key insight: the religious framing is marketing, not ministry. When a “Christian” debt counseling company talks you out of bankruptcy that would save you $40,000 in fees and five years of your life, that is not godly guidance. That is a sales pitch wearing a cross.
Explore the Full Bible and Bankruptcy Series
The Biblical Case Against Dave Ramsey’s Bankruptcy Shame
Dave Ramsey uses religious guilt to discourage bankruptcy. Here’s what scripture actually teaches about debt forgiveness, Jubilee, and fresh starts — and why his framing contradicts his own faith tradition.
43 Catholic Organizations Filed Bankruptcy. So Why Are You Being Told It’s Ungodly?
The Diocese of El Paso filed Chapter 11 in 2026. When institutions call it “the only way,” why is it a sin when you need it? The institutional double standard, documented.
What the Bible Really Says About Debt (It’s Not What You Think)
The Bible warns about debt as bondage — but it also mandates release from that bondage. A complete look at every major debt passage in scripture and what it actually means for your situation.
Why Do Churches Keep Filing Bankruptcy?
A documented history of churches and religious organizations choosing bankruptcy protection — and what that tells us about who the moral argument against personal bankruptcy actually serves.
Christian Debt Advice: Myth vs Reality
Most “Christian debt counseling” is religious branding on standard debt products. Here’s how to tell the difference between genuine guidance and a sales pitch wearing a cross.
Why Jesus Would File for Bankruptcy: The Biblical Case for Debt Forgiveness
God’s law commanded debt release every 7 years. Jesus taught forgiveness of impossible debts. Modern bankruptcy is a secular Jubilee — backed by Scripture.
The Practical Answer: What Should You Actually Do?
If you’re carrying debt that has become unmanageable, here is what I want you to take away from everything above:
- Bankruptcy is a legal tool with biblical origins. God’s law mandated debt release every seven years. American law allows it every eight. You are not doing anything God didn’t design into the economic system.
- Your creditors are businesses making calculated bets. The interest rate on your debt already priced in the possibility of default. You are not betraying a personal relationship — you are an entry on a balance sheet.
- Never cash out retirement to avoid bankruptcy. Retirement accounts are protected in bankruptcy. They are not protected from your own decision to drain them. Trading your future for someone else’s balance sheet is not stewardship — it is the opposite.
- The shame is not yours to carry. It was placed on you by people who benefit from your reluctance to use a legal tool. The Bible doesn’t put it there. The data doesn’t support it. The institutions promoting it don’t apply it to themselves.
- Get an informed picture of all your options. Bankruptcy may or may not be right for your specific situation. Take my Find Your Path quiz to understand the full range of options — without the shame attached to any of them.
Key Takeaways
- Scripture mandated debt release every seven years — bankruptcy law mirrors this with an eight-year cycle
- Jesus’s parables used debt forgiveness as the model, not debt repayment at all costs
- 43 U.S. Catholic religious organizations have filed Chapter 11 bankruptcy — calling it the responsible choice
- The shame around personal bankruptcy was manufactured by people with a financial interest in your continued debt payments
- Federal Reserve data shows bankruptcy filers are better off financially within two to three years
The Bottom Line
The Bible does not condemn bankruptcy. It invented the concept. God commanded debt release every seven years and a complete economic reset every fifty. Jesus taught debt forgiveness as a virtue and used it as the central metaphor for divine grace. Forty-three U.S. Catholic religious organizations have filed for bankruptcy protection when their debts became unmanageable — calling it wise, equitable, and the only available option. The shame directed at individuals considering bankruptcy has no biblical foundation, no empirical support, and a clear financial beneficiary. If you are staying in a financially dangerous situation because someone told you that bankruptcy is ungodly, I want you to know: they are wrong, the scripture disagrees with them, and the institutions making that argument file bankruptcy themselves.
Frequently Asked Questions
Does the Bible say bankruptcy is wrong?
No. The Bible mandates debt release every seven years (Deuteronomy 15:1-2), a full economic reset every fifty years (Leviticus 25), and teaches debt forgiveness as a divine virtue in multiple New Testament passages. Modern U.S. bankruptcy law, with its eight-year Chapter 7 discharge cycle, is closer to the biblical model than the “repay every dollar regardless of consequences” position that gets promoted as Christian teaching.
Is it a sin to file for bankruptcy?
There is no biblical basis for calling bankruptcy a sin. The passages most often cited in anti-bankruptcy religious arguments — Proverbs 22:7, Psalm 37:21 — warn about the dangers of debt and the ideal of repayment, but they do not condemn debt release. Meanwhile, the explicit debt forgiveness mandates (Deuteronomy 15, Leviticus 25) and Jesus’s parables (Matthew 18, Luke 7) establish debt cancellation as the biblical ideal when repayment is impossible. Forty-three Catholic religious organizations have filed bankruptcy without concluding they had sinned — and their institutional theologians have not condemned them for it.
What does the Year of Jubilee mean for bankruptcy?
The Year of Jubilee (Leviticus 25) was God’s command that every fifty years, all debts would be cancelled, all indentured servants freed, and all land returned to its original owners. It was the most radical debt relief program in recorded history — a mandatory, society-wide fresh start. It established that permanent debt bondage is incompatible with the biblical vision of human dignity and freedom. Bankruptcy, in this context, is not a deviation from biblical values. It is the contemporary expression of the same principle.
Did Jesus say anything about debt forgiveness?
Yes — and extensively. The Lord’s Prayer uses debt as the central metaphor for divine forgiveness: “Forgive us our debts, as we forgive our debtors” (Matthew 6:12). In Matthew 18, Jesus told the parable of a servant whose enormous debt was completely cancelled by a merciful king. In Luke 7:42, Jesus described a creditor who “freely forgave” two debtors who “had nothing with which to repay.” Both parables end in forgiveness, not prolonged repayment. Jesus’s teaching treats debt cancellation as an act of mercy — not a moral failure by the debtor.
How many churches have filed bankruptcy?
As of December 2025, 43 U.S. Catholic religious organizations had filed Chapter 11 bankruptcy protection, according to Penn State Dickinson Law research. The Diocese of El Paso filed in March 2026. Protestant churches and other religious organizations have also filed in significant numbers — a 2020 American Bankruptcy Institute analysis noted that between 2006 and 2017, a mean of 79 religious organizations filed Chapter 11 per year. For a deeper look, read Why Do Churches Keep Filing Bankruptcy?
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



do you lose your home and vehicle if you file bankruptcy?
Not necessarily. Discuss this with a bankruptcy attorney who is licensed in your state.
Steve