
Quick Answer: Money anxiety comes in two very different kinds, and almost every article about it only addresses one. If you are genuinely behind — missed payments, collectors calling, a balance you can’t see the end of — your anxiety is a rational response to a real math problem, and it usually starts lifting the moment the math has a plan, long before the debt is actually gone. If you are not behind — bills paid, savings growing, and you still feel a knot in your chest every time you check a balance — then no budget, no spreadsheet, and no payoff calculator is going to touch it, because the math was never the thing that was wrong. Knowing which one you have is the single most useful thing you can figure out, because the two need opposite responses. This guide is built to help you sort that out.
Why I built this page
I ran a nonprofit credit counseling organization with 70 employees. We hired psychologists — which almost nobody in that industry did — because I kept watching something that made no sense to me on paper: people whose numbers were improving, month after month, who felt no better at all. And people whose numbers were terrible, who slept fine the night they finally had a plan. I filed my own bankruptcy in 1990, so I have been on the inside of that feeling too. After more than 30 years of this, I have stopped treating money anxiety as a side effect of debt. Very often it is the main event, and the debt is just where it shows up.
Start here: is your anxiety pointing at something real?
I want to give you the fork in the road before I give you anything else, because everything downstream depends on it.
Anxiety is, at its most useful, a smoke alarm. Sometimes it is going off because there is a fire. Sometimes it is going off because the battery is bad. Both are real, both are worth taking seriously, and both are exhausting to live with — but you do not fix them the same way. Standing in the kitchen waving a towel at a smoke alarm with a bad battery is a good description of what most money advice does to people in the second group.
The two kinds, stated plainly:
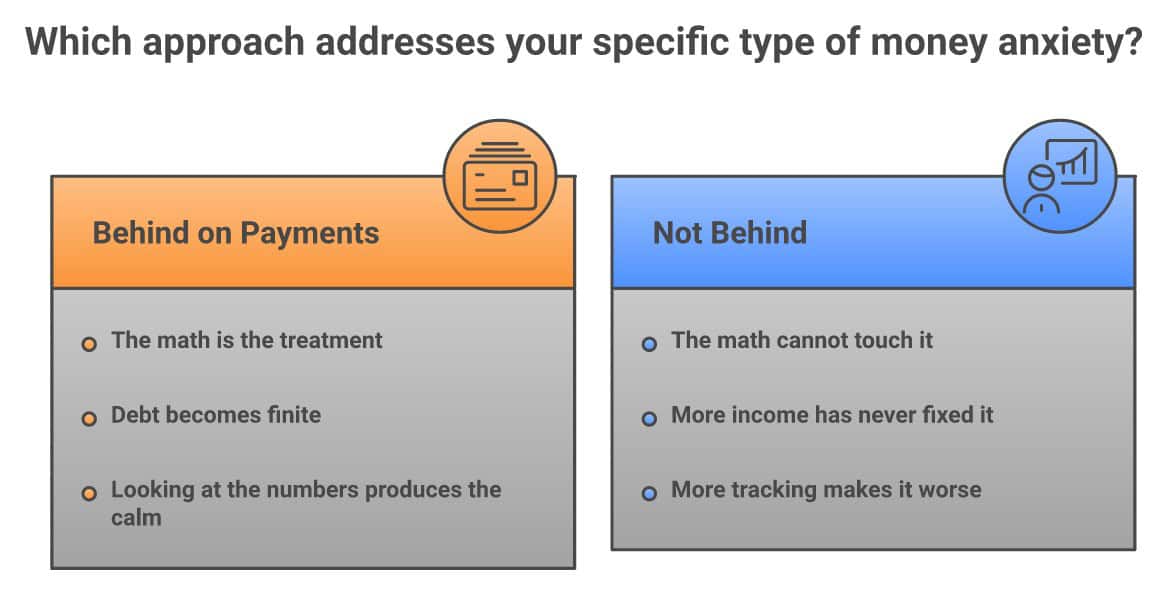
- There is a fire. You are behind, or you are one bad month from being behind. The anxiety is doing its job — it is telling you something needs to change. Here, the math is the treatment. Not because money buys peace, but because a credible plan converts an unbounded fear into a bounded one — and in my experience people feel that shift almost immediately, before a single dollar has moved.
- The battery is bad. By any external measure you are fine, and the fear does not care. Here, the math is not the treatment, and doing more of it — another spreadsheet, another budgeting app, another round of tracking every coffee — usually makes it worse, because it feeds the part of your brain that believes vigilance is what’s keeping you safe.
Most people can tell which one they are within about ten seconds of reading that. Some can’t — and if that’s you, I want to be careful here, because the two questions involved are genuinely different and it matters which one you answer first.
Answer the factual question first. Which path you’re on is a matter of fact, not feeling: are you behind, or one bad month from it? Feelings are unreliable narrators about this in both directions — frightened people routinely believe they’re in worse shape than they are, and people in real trouble routinely tell themselves they’re managing. So don’t guess and don’t go by how it feels. Put the real balances in front of you, or run the Find Your Path quiz, which sorts you on your actual numbers.
Then, on either path, ask the second question: how heavy is this on you? That’s what the Debt Stress Test measures. It takes two minutes and it’s built on the PHQ-9, a clinical screening instrument, not a personality-quiz formula I made up. It won’t diagnose you and it isn’t meant to — it tells you whether what you’re carrying looks like ordinary worry or like something a professional should look at. That question is worth answering whichever path you’re on. What it will not tell you is whether you’re behind on your bills, so please don’t use it for that.
The number that changed how I do this work
When I ran that counseling organization, we screened the people coming to us for depression. Almost nobody in the debt industry was doing that, and I want to tell you what we found, because it reframed the entire problem for me.
Source: original research conducted by Myvesta, the nonprofit I founded. Read the full study findings here. One honest caveat, because I would rather you hear it from me: this was a 2001 survey of our own clients — people who had already decided they needed help — screened with the CES-D, which flags risk rather than diagnosing anyone, and not a controlled clinical study, and the general-population comparison reflects estimates from that era. Treat the exact percentages as directional. The pattern is one I have watched hold for decades since; the decimal points should not be leaned on hard.
Roughly half. Not a fringe. Not the extreme cases. Half of the people walking through the door for help with a math problem were carrying something a doctor would have recognized on sight — and not one of them had been asked about it, because the entire industry was built on the assumption that the money was the problem and the feelings were the symptom.
I have come to believe that gets it backwards at least as often as it gets it right. And it explains something that used to baffle me: why “just make a budget and stick to it” fails so reliably for so many people. You cannot willpower your way through a depressive episode with a spreadsheet. Telling someone in that state to try harder isn’t advice. It’s an accusation.
Path one: you are actually behind
If the smoke alarm is going off because there’s a fire, here is the thing I most want you to know, and it is not what you’d expect.
The relief does not arrive when the debt is gone. It arrives when the debt becomes finite.
I have watched this hundreds of times. Someone comes in owing $40,000 and cannot sleep. They leave still owing $40,000 — not a dollar has moved — and they sleep that night. What changed is that the debt went from a formless dread with no edges to a specific number with a specific end date. Human beings can carry an enormous amount of bounded difficulty. What we cannot carry is not knowing where the bottom is.
That is why, on this side of the split, doing the math genuinely is the treatment. Not as a moral exercise. As a way of putting walls around the thing.
- Get the actual number. Not your estimate. Every balance, every rate, every minimum, on one page. Almost everyone I have ever done this with finds the real number is different from the one they’d been carrying around — sometimes worse, very often better, and either way the dread of not knowing was heavier than the fact.
- Find out which door applies to you. The Find Your Path quiz gives you a recommendation based on your actual numbers rather than on what a company wants to sell you.
- Understand that bankruptcy is a tool, not a verdict. I filed in 1990. It is the option the industry is least willing to explain honestly, because nobody makes money on it. If it is the right answer for your numbers, being afraid of it costs you years.
- If the panic is right now, the crisis guides are written for specific emergencies — sued, garnished, foreclosure, hospital bills — with the immediate steps for each.
- Talk to a human who isn’t selling anything. Damon Day will talk to you for free. I get nothing if you call him.
The one thing I’d ask you not to do: don’t wait until you feel calmer to look at the numbers. It runs the wrong direction. Looking at the numbers is what produces the calm — the avoidance is what keeps the dread unbounded. The worst night is almost always the night before you look, not the night after.
If your debt has already pushed you somewhere darker than worry, Debt and Mental Health goes deeper on depression, shame, and what to do about the relationship damage — including crisis lines if you need them today.
Path two: nothing is wrong, and you’re still afraid
This is the half almost nobody writes for, and it is the reason I built this page.
Before you read this section, one check. If you have missed payments, if collectors are calling, or if you genuinely don’t know your real numbers — this isn’t your section yet. Go back to Path One and find out where you actually stand first. Everything below assumes the math has been checked and is genuinely fine. And if that changes next week — a notice you hadn’t opened, a bill you didn’t know about — then the path changes with it. Nothing here is a permanent assignment.
You pay your bills. You have savings. Maybe you have quite a lot of savings. Your credit is good. By every number a financial advisor would look at, you are doing fine — and you feel a small cold drop in your stomach when a bank notification comes in, and you have never once felt like you have enough, and you cannot remember the last time you spent money without a quiet negotiation happening somewhere in the back of your head.
Here is the part I want to say clearly, because I don’t think you’ve been told it: more money will not fix this, and you already have the evidence. Think about what you earned ten years ago. If you had been told then what you’d be earning now, you’d have assumed the fear would be gone by now. It isn’t. That is not a sign you need to earn more. That is the experiment already having been run.
Why standard money advice actively backfires here. Budgeting, tracking, optimizing, and checking are vigilance behaviors. For someone in real financial danger, vigilance is appropriate and protective. For someone who is safe, vigilance is the engine of the anxiety, not the cure for it — each check gives a few seconds of relief, and in my experience that relief is exactly what keeps the habit going — the checking starts to feel like the thing keeping you safe, and the next gap between checks then feels more dangerous rather than less. Psychologists have a name for this shape: a safety behavior — something you do to prevent a feared outcome that ends up maintaining the fear instead. Recognizing it as one is usually more useful than trying to stop cold. If you have ever noticed that the more carefully you track, the more anxious you get, you are not doing it wrong. You are doing something that cannot work, very well.
I am not going to pretend I can resolve this in a web page. But I can tell you what I have watched actually move it, and what the money side of it looks like when it’s handled well.
- Build the number that buys sleep, then stop. For most people it’s three to six months of essential expenses, held somewhere boring and reachable. I’ve written before about why I would keep the cushion rather than throw it at the debt, and this is why: the cushion isn’t a financial instrument, it’s a psychological one. Past that point, additional savings tends to stop buying additional calm — and if it isn’t buying calm, be honest with yourself about what you’re actually accumulating it for.
- Automate the decisions you’re re-litigating. Every recurring money choice you make manually is a chance to feel the fear again. Automating a transfer isn’t laziness. It’s removing an occasion for anxiety.
- Put a fence around checking. Not zero — in my experience that tips into avoidance, which is the same problem wearing the opposite mask. A specific time, a specific frequency, and outside of that window the balance is simply not available to you as a thing to look at.
- Ask where you learned it. Almost every person I’ve met with money fear that outruns their circumstances can name the room it started in. A parent who lost work. An eviction. A childhood where money was the thing people screamed about at night. That’s not a spending problem you can budget away. It’s a memory doing its job too well, decades later.
- Consider that this may be a job for a therapist, not a financial planner. I am not being glib. If your relationship with money is causing you real suffering while your finances are objectively fine, a financial professional has no tool for that and a good therapist does. There is no shame in that sentence, and I’d rather be the one to say it to you than have you spend another five years looking for the spreadsheet that finally works.
The shapes money anxiety takes
In my experience it isn’t one thing. It shows up in recognizable patterns, and naming yours tends to be the moment something loosens — partly because a named thing is smaller than an unnamed one, and partly because different shapes need genuinely different responses.
Why “just be more disciplined” keeps failing
There is a large body of research on this, and the short version is that financial education — the kind that teaches people facts about compound interest and expects behavior to follow — has a remarkably poor track record. Not because people are stupid. The largest meta-analysis on this — Fernandes, Lynch and Netemeyer (2014), pooling 201 studies and 585,168 people — found that financial-literacy interventions explained just 0.1% of the variance in what people actually did with their money, with weaker effects still among low-income participants. And the effect decays: even large programs running many hours showed negligible behavioral effect 20 months on. Knowing and doing are different capacities, and in my experience stress makes the second one much harder to reach.
- Why financial education fails — what the research actually shows about money psychology and behavior.
- Why people make the wrong debt decision — the behavioral economics of choosing under financial pressure.
- Financial stress and cognitive decline — what years of money trouble may do to your brain, which is the part of this that ought to make everyone treat the stress as a real medical variable rather than a mood.
- ADHD and debt — if standard money advice has never worked for you and you’ve always assumed that was a character flaw, read this one first.
The research this page rests on
I want you to be able to check me. I keep a working reference library of the actual peer-reviewed literature on money and mental health — not summaries of it, the papers themselves — and these are the ones underneath this page. I am not going to pretend I have read every line of every one, or reduce any of them to a single tidy number, because that is exactly how research gets mangled on the internet. But if you want to go past my opinion to the source, this is where to start.
- Ryu & Fan (2022) — Financial Stress and Depression in Adults: A Systematic Review. The broad survey of what is actually established about the link.
- Ng, Nawi & Ismail (2020) — Relationship Between Debt and Depression, Anxiety, Stress, or Suicide Ideation. A second systematic review, covering the more severe end.
- Hu, Levine, Lin & Tai (2019) — Mentally Spent: Credit Conditions and Mental Health. Looks at credit conditions against measured mental-health outcomes, including antidepressant use.
- Fernandes, Lynch & Netemeyer (2014) — Financial Literacy, Financial Education, and Downstream Financial Behaviors, Management Science 60(8). 201 studies, 585,168 participants, 0.1% of variance explained. The meta-analysis behind why “just teach people about money” keeps disappointing.
- Heath & Soll (1996) — Mental Budgeting and Consumer Decisions. Why the budget in your head behaves differently from the budget on paper.
- Faber & Vohs (2011) — Self-Regulation and Spending: Evidence from Impulsive and Compulsive Buying. Relevant to the compulsion pattern above, and to why willpower is the wrong tool for it.
- MIDUS Study, University of Wisconsin (2020) — How Shame Intensifies Financial Hardship. On shame and the withdrawal it produces — the mechanism behind unopened mail.
- Garbinsky, Gladstone, Nikolova & Olson (2020) — Love, Lies, and Money: Financial Infidelity in Romantic Relationships. The research behind “the secret.”
- Smigielski et al. (2008) — Decision-Making and Risk Aversion among Depressive Adults. Why “just make a decision” is harder than it sounds when you’re low.
- Liu et al. (2026) — Persistent Financial Adversity and Cognitive Aging: A Life Course Investigation, Innovation in Aging, July 2026, following the 1946 British birth cohort. The long-run health question, which I wrote about separately in financial stress and cognitive decline.
- Guzelian, Stein & Akiskal (2015) — Credit Scores, Lending, and Psychosocial Disability. On what happens where credit systems meet mental health.
- Biolcati (2017) — The Role of Self-Esteem and Fear of Negative Evaluation in Compulsive Buying.
If you notice that almost every one of these studies is about the first path — debt, hardship, distress — you have spotted the same gap I did. That is most of what the literature covers, and it is a large part of why the second path gets written about so rarely.
Tools that tell you something you didn’t already know
These are free, none of them collect anything they don’t need, and I am not selling you anything at the end of them. They’re here because the whole point of this page is self-knowledge, and these are the instruments I have.
🧭 Find Your Path
If the math is the problem, this gives you a recommendation based on your real numbers — including the options most sites won’t discuss.
🧪 Debt Stress Test
Two minutes, PHQ-9-based. Tells you how heavily this is sitting on you — not which path you’re on. Take it after you’ve answered the factual question with your real numbers or the Find Your Path quiz. It’s worth taking on either path.
💭 Money Personality Quiz
Where your money habits actually come from. Useful mostly for the second path — the one where the numbers are fine and the feeling isn’t.
🤐 The Debt Confessional
Anonymous. No account, no email, no judgment. For when the heaviest part is that you haven’t said it out loud to anyone.
💬 Ask Steve
Ask me directly. It’s free, it’s private, and I’m not selling anything. This is not a subscription companion built to keep you company — if the honest answer to your question is “talk to a therapist” or “call Damon Day,” that is the answer you’ll get. If you’re not sure whether your situation even counts as a real problem, that is exactly the kind of question to bring.
🧠 Debt and Mental Health
The deeper guide for the first path — depression, shame, relationships, and what to do when debt has pushed you somewhere darker than worry.
What I’m not going to tell you
There is a growing industry around money anxiety right now — apps, AI companions, subscriptions, courses — and I want to be straight with you about where I think the honest line is, because I have watched an industry monetize this exact feeling before, from the inside.
- I’m not going to tell you your anxiety is only in your head. If you’re behind, it isn’t. Being told to breathe through a real emergency is its own kind of insult, and a lot of the wellness framing around money does exactly that. Sometimes the correct treatment for financial anxiety is fixing the finances.
- I’m not going to tell you the numbers don’t matter. They do. That’s the failure mode on the other side — endless emotional processing of a problem that a bankruptcy filing or a negotiated settlement would have solved in a season.
- I’m not going to sell you calm on a subscription. If something charges you monthly to feel better about money and never touches the money, look hard at what you’re buying.
- I’m not going to pretend I’m a therapist. I’m not one. I’ve spent over 30 years next to this problem and I know its shape well. When what you need is clinical, I’d rather say so than keep you.
Key Takeaway: Sort yourself first — is the alarm pointing at a real fire, or is the battery bad? If you’re genuinely behind, the math is the treatment, and relief arrives when the debt becomes finite, not when it’s gone. If you’re not behind and still afraid, no budget will touch it, and the tracking you’ve been doing to feel safer is probably feeding it. Both are real. Both deserve to be taken seriously. They just need opposite things, and almost all the advice out there is written as if only the first one exists.
Frequently Asked Questions
Is money anxiety a real condition?
“Money anxiety” isn’t a formal diagnosis you’ll find in a clinical manual, but financial stress is a well-documented driver of anxiety and depressive symptoms, and the effects are physical as well as emotional. In the original research I ran at Myvesta, 49.3% of people in debt crisis screened positive for depression symptoms and 39.7% scored in the severe range — directional figures from a 2001 CES-D screening survey of our own clients, not a controlled clinical study. This page used to compare that to an unsourced general-population figure and call it a five-fold gap. That comparison was built wrong — it set a screening result against a diagnosis rate — so I rebuilt it from a single peer-reviewed source, backing false positives out of both sides. I have since gone back to the original 2001 report. It surveyed 136 clients — a small sample, with a margin of error around eight points — and the 9.5% comparison in it was unsourced from the start. Rebuilt honestly the elevation is a range rather than a number, roughly two to five times. I show the whole working, including my own wrong turn, on the study page, and the original report is linked there so you can read it yourself. A screen is never a diagnosis. I set out the full limits of that study, and the independent literature that has grown up around the same relationship since, on the research page. Whether or not it has its own diagnostic label, it is real, it is common, and it is treatable — the question worth answering is whether yours is tracking a genuine financial danger or has become self-sustaining.
How do I know if my money anxiety is normal or something more?
Two rough tests. First, proportion: does the fear match the facts? Worry that tracks a real, current danger is doing its job. Fear that stays constant while your circumstances improve dramatically is not tracking anything. Second, function: is it making you act, or making you avoid? Anxiety that gets you to open the mail is useful. Anxiety that stops you opening it has stopped helping. If you want something more structured than a self-assessment, the Debt Stress Test is a two-minute PHQ-9-based screen.
Will paying off my debt make the anxiety go away?
Partly, and probably sooner than you think — but not in the way most people expect. In my experience the relief mostly arrives when the debt becomes finite and planned, not when the last dollar clears. That’s often months or years earlier. The caveat: if you’d have described yourself as anxious about money even in periods when you had none, paying off the debt will remove a real burden and leave the underlying pattern intact, and it’s better to know that in advance than to be blindsided by it.
I make good money and I’m still afraid. What’s wrong with me?
Nothing that isn’t extremely common. Money fear tends to be calibrated by experience — often experience from long before you had any money of your own — rather than by your current balance. That’s why raises so reliably fail to fix it: the raise changes the facts, and the fear was never indexed to the facts. This is the half of money anxiety that budgeting cannot reach, and it’s the half most likely to respond to a good therapist rather than a better spreadsheet.
Does checking my accounts more often help?
It depends entirely on which side of the split you’re on. If you’ve been avoiding, then yes — looking is the single highest-value thing you can do, and the dread almost always outweighs the facts. If you’re already checking several times a day and feeling worse, then no: frequent checking is a vigilance behavior that buys seconds of relief and charges compound interest on it. Same action, opposite prescription, which is exactly why generic advice fails so many people.
Should I see a therapist or a financial professional?
If you’re behind on real obligations, start with the money — a plan will do more for your head in a week than talking about it will. If your finances are objectively sound and the fear persists anyway, a financial professional has no tool for that, and a therapist does. Many people need both, in that order. And for the money half specifically, Damon Day will talk to you for free — I receive nothing for saying that.
Can financial stress actually affect my physical health?
Yes, and this is the part I wish were better known. Chronic financial stress has been linked to sleep disruption, cardiovascular strain, and measurable cognitive effects — I wrote about the research on financial stress and cognitive decline separately. It’s a reason to treat this as a genuine health variable rather than something to tough out, and a reason to mention it to your doctor, who will not be surprised or judgmental.
The Bottom Line
After more than 30 years of this, the thing I’d most want you to take away is that you are allowed to find money frightening without it meaning you’re bad at money. Roughly half the people who came to my organization for help with arithmetic were carrying something a doctor would have recognized, and not one of them had been asked. So let me be the one to ask: which alarm is going off for you? If it’s a real fire, the math is the fire extinguisher and it works faster than you expect — the relief comes when the thing gets edges, not when it disappears. If the battery’s bad, no amount of budgeting will help, and the tracking you’ve been doing to feel safer has probably been feeding it. Either way, you are not the first person to feel this, you are not weak for feeling it, and it is not permanent. If this put words to something you’ve been carrying without a name for it, please send it to someone else who needs it — most people never say this out loud, which is exactly why so many of them think they’re the only one.
One more thing, as always: everything here comes from over 30 years of helping people deal with debt and from watching this specific problem up close. But my advice is input for your decision, not the decision itself. I’m not a therapist or a doctor — if what you’re carrying feels heavier than this page can reach, please talk to one. There is no version of that conversation you’ll regret.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



