Quick Answer: When someone dies, their estate publishes a “Notice to Creditors” in a local newspaper — and that little legal ad starts a clock that can legally erase their unsecured debts. Creditors who don’t file a claim by the deadline (typically 3–7 months, depending on the state) are forever barred from collecting. Known creditors must also get actual mailed notice — the Supreme Court said so. Family members don’t inherit the debt either way. Here’s how the process actually works.
Where this topic came from: A recent conversation in my free Ask Steve chat raised exactly this kind of situation. I’m not giving away any personal information here — I never do — but when a real question shows me a gap worth covering, I write the answer for everyone. If you’re untangling a situation like this yourself, ask me about it in the chat. It’s free, it’s private, and I’m not selling anything.
Of all the things families ask me after a death, this one comes up over and over: “The lawyer says we have to publish a notice in the newspaper. What does that even do? Do we have to track down everyone Mom owed money to?”
Here’s the part almost nobody knows, and it changes everything about how you handle a loved one’s debts: that newspaper notice is the beginning of the end for most of their unsecured debt. Most people assume debts live forever and someone, somewhere, will always come collecting. Well, actually — the law gives every debt a deadline to speak up. Miss it, and the debt dies with the paperwork.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
What the Notice to Creditors Actually Does
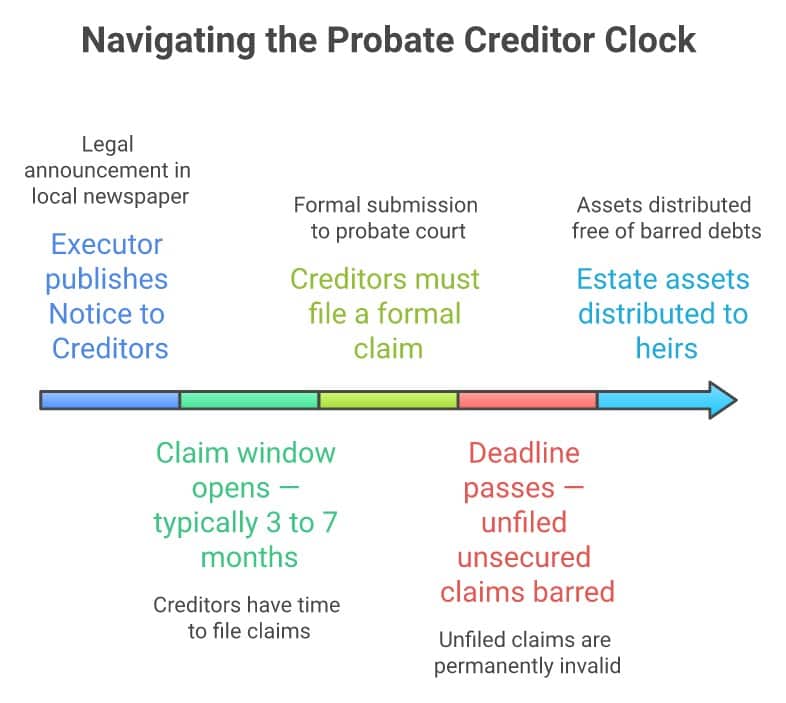
When an estate opens in probate, the executor (also called a personal representative) is required to alert potential creditors that the person has died and that claims can be filed against the estate. That happens two ways at once:
- The newspaper notice — a legal ad in a county newspaper, usually run once a week for three consecutive weeks. It names the deceased, the court, the executor, and the deadline to file claims. This covers unknown creditors — anyone the executor couldn’t reasonably have found.
- Direct mailed notice — for every creditor the executor knows about or could reasonably discover. This isn’t optional courtesy; it’s constitutional law. In Tulsa Professional Collection Services v. Pope (1988), the U.S. Supreme Court ruled that known or “reasonably ascertainable” creditors must get actual notice by mail — a newspaper ad alone isn’t enough to cut off their claims.
Once notice goes out, the claim window opens. And this is where the magic — or the reckoning, depending on which side you’re on — happens.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The Deadline That Kills Debts
Every state sets a window for creditors to file a formal claim with the probate court. Miss the window, and the statutes use a phrase I’ve always found beautifully blunt: the claim is “forever barred.”
| State | Claim Deadline | Backstop |
|---|---|---|
| Florida | 3 months from publication (30 days from mailed notice, if later) — Fla. Stat. § 733.702 | Absolute 2-year bar from death, even if probate never opens — § 733.710 |
| California | 4 months from the executor’s appointment (60 days from mailed notice, if later) — Prob. Code § 9100 | Hard 1-year bar from date of death |
| Texas | About 4 months from direct notice — Est. Code § 308.054 (newspaper publication often isn’t even required) | Varies |
| Illinois | 6 months from publication (3 months from mailed notice, if later) | 2 years from death |
| Ohio | 6 months from the date of death — R.C. § 2117.06 | Same 6-month clock |
| Arizona | 4 months from publication (60 days from mailed notice, if later) — A.R.S. § 14-3803 | 2 years from death |
| Washington | 4 months from publication (30 days from mailed notice, if later) — RCW 11.40.020 | — |
New York runs differently — its 7-month rule mainly protects the executor from personal liability for distributions made in good faith, rather than killing claims outright. As always, the table above is the map, not the territory: check your state’s exact rule or ask a probate attorney before relying on a deadline.
One distinction matters enormously here: this only works on unsecured debt — credit cards, medical bills, personal loans, utility balances. A mortgage or car loan has a lien attached to the property itself, and liens survive the claims process. If nobody keeps paying the mortgage, the lender forecloses, claim or no claim.
What This Means If You’re Handling an Estate
The notice process is your friend — when you do it right. A few things I’d tell anyone sitting where you’re sitting:
- Do the diligent search, in writing. Go through the mail, bank statements, and bills, and send certified-mail notice to every creditor you find. Skipping a known creditor doesn’t make their debt disappear — it keeps their claim alive past the deadline, because the cutoff only binds creditors who got proper notice. Courts can also hold executors personally liable for sloppy notice.
- Never pay a late claim without checking. If a claim arrives after the deadline, you are generally not allowed to pay it — and paying it can make YOU liable to the heirs. One Florida executor was held personally responsible after paying $2.5 million in time-barred claims.
- Don’t pay anything out of guilt or pressure before the process runs. Valid claims get paid from estate assets in a priority order set by state law. Your job is to run the process, not to make creditors whole from the family’s pocket.
What This Means If Collectors Are Calling the Family
Now the other side — the one I’ve spent decades fighting. Debt collectors know exactly how this process works, and some of them count on grieving families not knowing it. The FTC has explicitly warned collectors against misleading relatives into believing they’re personally liable for a dead relative’s debts. The CFPB’s rule is plain: unless you co-signed, held the account jointly, or live in a community property state with a spouse’s marital debt, only the estate owes the debt. Not you.
So when a collector calls about a deceased relative’s credit card — especially months or years later — the questions to ask are: Did you file a claim with the probate court? Was it filed before the deadline? If the answer is no, that debt is likely barred, and the call is theater. My crisis guide on what to do when a collector calls about a dead relative’s debt walks through exactly how to handle the conversation, and my complete Debt After Death guide covers the whole landscape — what survives, what doesn’t, and who actually owes what.
If a collector crosses the line — implying you owe what you don’t, calling repeatedly after being told to stop — file a complaint with the CFPB and your state attorney general, and consider a NACA consumer attorney. FDCPA violations carry statutory damages plus attorney’s fees, which is why good consumer lawyers often take these cases at no cost to you.
I’ve watched too many families drain savings paying debts the law had already extinguished, because nobody told them about a three-month window that closed two years earlier. If someone in your life is settling a parent’s or spouse’s estate right now, send them this — it might be the most valuable newspaper ad they never read.
Everything here comes from 30 years of helping families untangle debt, but probate is state law and details matter — a conversation with a probate attorney in your state is worth far more than any article, including mine. Take this as input for your decisions, not instruction. Only you know your full situation.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
If your spouse just died and collectors are already calling: that’s its own emergency. See my crisis guide on what you actually owe (and what you don’t) when a debt collector calls after your spouse dies — including how to protect your Social Security.