

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 26, 2025
Quick Answer: You paid into a debt settlement program, your creditors are still calling, and nothing has been settled — that is a recognized pattern, and you have legal protections. Under the FTC’s Telemarketing Sales Rule (16 CFR § 310.4(a)(5)), a debt settlement company that sold its service by phone cannot legally collect any fee until it has actually settled at least one of your debts AND you have made at least one payment on that settlement. You also have the right to cancel at any time and get all your dedicated-account funds back within 7 business days. Don’t keep paying into a program that isn’t working — you have options, and some of them are faster than you think.
What Just Happened to Your Money
You enrolled in a debt settlement program — probably after someone told you they could cut your balances by 40% to 60% and get your creditors off your back. You’ve been making monthly payments into a “dedicated account” or “escrow account” ever since. But here you are, months (maybe years) in, and your creditors are still calling, your balances are still growing with late fees and interest, and not a single debt has been settled.
This is not unusual. This is how most debt settlement programs go. The FTC’s own guidance on debt relief services is blunt: most debt settlement programs take two to four years to complete — and, per the CFPB, many people drop out before a single debt is resolved. During that time, you were likely told to stop paying your creditors. So your credit score got worse, late fees piled up, and your balances may actually be higher now than when you started. And in the meantime, creditors can and do file lawsuits against enrolled consumers. Your settlement company cannot stop a lawsuit.
What you may not know: if the company sold you the program over the phone and charged you fees before settling any of your debts, that may be illegal under federal law. And you can get your escrow money back.
It also helps to understand how the sales floor that enrolled you actually works — a federal court filing shows the person who signed you up was likely working a monthly enrollment quota, not a financial plan.
The Mistake You’re About to Make: The two most common panicked moves in this situation are: (1) keep paying into the program month after month, hoping it will finally work, or (2) just stop paying and walk away — without demanding your escrow funds back first. Either one costs you. If you quit without formally canceling and reclaiming your dedicated-account balance, that money can sit there while the company continues charging administrative fees. Get your account balance in writing, formally cancel, demand every dollar back, and then — only then — evaluate all your options fresh, including the ones the settlement company never mentioned.
Your Options Right Now
What to Do in the Next 48 Hours
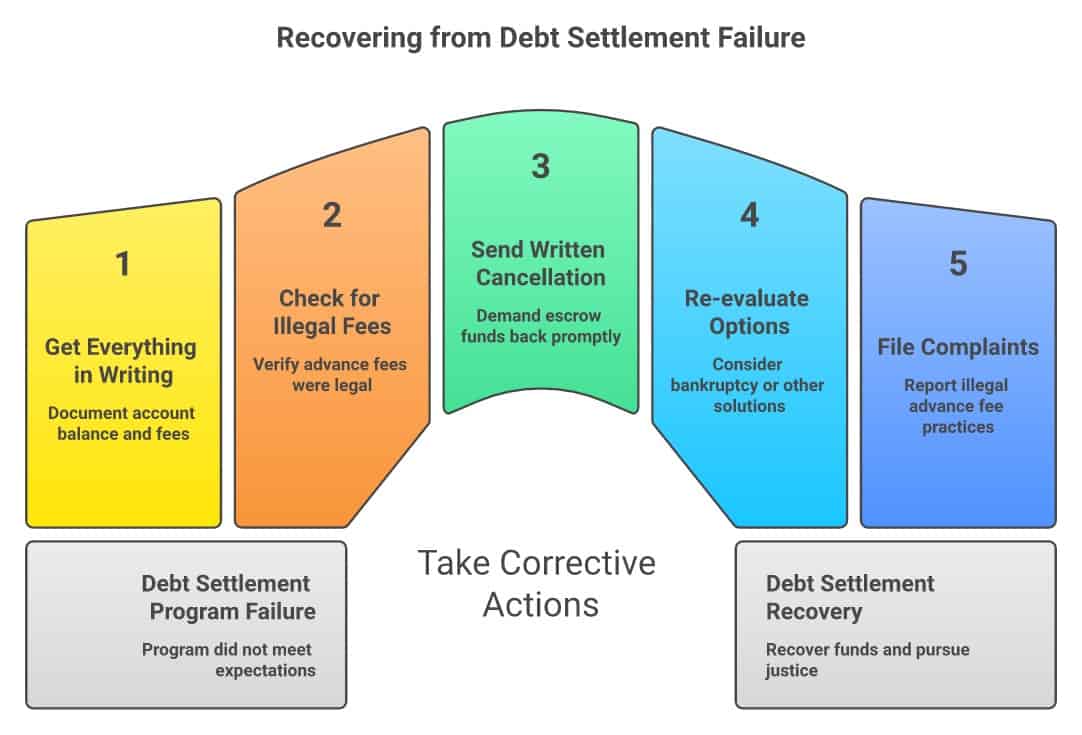
- Get everything in writing, today. Contact the settlement company and request, in writing: your current dedicated-account balance, a complete record of all fees paid to date (including setup fees, monthly fees, and any “legal” fees), and a list of exactly which debts (if any) have actually been settled. Do not rely on what they tell you verbally. You need the paper trail.
- Check whether the advance-fee ban applies to you. Under 16 CFR § 310.4(a)(5), if the company marketed its services to you by phone, it cannot legally charge you any fee until it has settled at least one debt AND you have made at least one payment toward that settlement. Calling the fee a “retainer” or routing it through an attorney does not exempt the company from this rule. If you were charged fees before any debt was settled, document exactly what you paid and when — that may be an FTC violation.
- Exercise your right to cancel and demand your funds. You can withdraw from the program at any time, without penalty. The settlement company is legally required to return all funds in your dedicated account — minus only fees they lawfully earned under the TSR — within 7 business days of your cancellation request. Sending it in writing (email with read receipt, or certified mail) gives you the best paper trail — but the statute requires only that you make a request, not that it be in any particular form. Send the cancellation in writing (email with a read receipt, or certified mail) and keep a copy. If they refuse or delay, file a complaint immediately (see Step 4).
- Re-evaluate your real options — including bankruptcy. Many people who’ve spent 12 to 24 months in a failing settlement program would have been completely discharged in months through Chapter 7 bankruptcy. The automatic stay takes effect the moment you file — not weeks later — stopping collection calls, lawsuits, and wage garnishment instantly. Federal Reserve research shows that bankruptcy filers recover faster than those who don’t file — a conclusion supported by multiple research papers including work published through Federal Reserve channels on credit recovery trajectories after filing. Find a bankruptcy attorney through NACBA (the National Association of Consumer Bankruptcy Attorneys).
- File complaints — and talk to Damon Day for free. If you believe the company violated the FTC’s advance-fee rule, file with the FTC (reportfraud.ftc.gov) and your state attorney general and the CFPB. Then call Damon Day — he reviews debt-settlement contracts for free and gives people an honest assessment of whether to stay in the program or get out. He’s seen hundreds of these contracts. He’ll tell you the truth.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
How to Actually Recover — Your Real Paths
- Bankruptcy (Chapter 7 — fastest path for most people). If you qualify, Chapter 7 eliminates most unsecured debt (credit cards, medical bills, personal loans — the debts that end up in settlement programs) in 3 to 6 months. The automatic stay stops all collection activity the moment you file. Federal Reserve research shows filers recover faster than those who don’t file. Credit scores typically rise within 12 months of discharge. Find a bankruptcy attorney at NACBA.org.
- Cancel and reclaim your escrow — then reassess. If the debts aren’t enormous and you have income, canceling the program, getting your dedicated-account funds back, and negotiating directly with individual creditors may be realistic. Some creditors will settle one-on-one without a middleman — especially if the account is already delinquent. Get any agreement in writing before paying a dime.
- Chapter 13 bankruptcy (repayment plan). If you have a home you want to protect or income that disqualifies you from Chapter 7, Chapter 13 lets you reorganize and repay debts over 3 to 5 years under court protection. The automatic stay still kicks in immediately. An attorney at NACBA.org can tell you which chapter fits your situation.
- What will NOT work: staying in the program longer. If your program hasn’t settled a single debt after 12 months, more time is unlikely to fix the underlying problem. Settlement companies don’t control when creditors agree to settle, and creditors are increasingly filing lawsuits against enrolled consumers rather than waiting. If a creditor sues you while you’re enrolled, your settlement company cannot stop the lawsuit or appear in court on your behalf.
What the Law Actually Says About Debt Settlement Fees
0
Fees legally collectible before your first debt is settled (phone-sold programs)
7
Business days to return your escrow funds after you cancel
2–4
Years the average settlement program takes — if you complete it
∴66%
Estimated dropout rate — per the industry’s own 2009 survey data, only 34% completed their programs (cited in GAO-10-593T); most leave before a single debt settles
The FTC’s Telemarketing Sales Rule, 16 CFR § 310.4(a)(5), prohibits debt-settlement companies that sell their services via telephone from collecting any fee whatsoever until: (1) at least one of your debts has been settled, (2) you have agreed to the settlement, AND (3) you have made at least one payment on that settlement. The law specifically closes the loopholes companies try to use — calling the fee a “retainer,” routing it through an attorney, or characterizing it as a “legal fee” does not exempt the company from the ban. The FTC’s own guide for businesses on this rule is public and explicit.
Separately, the Telemarketing Sales Rule also requires that companies tell you, before you enroll: how long the program will take, how much it will cost, the risks involved (including the damage to your credit and the possibility of being sued), and the fact that some creditors may refuse to negotiate at all. If they didn’t fully disclose these things, that’s also a potential violation.
| What Settlement Companies Often Say | What the Law / Reality Says | Source |
|---|---|---|
| “We’ll settle your debts for 40–60% of what you owe” | Settlement amounts vary widely; creditors are not required to negotiate; a 2–4 year timeline is typical | FTC Consumer Alert |
| “Our fees are a ‘retainer’ so they’re not covered by the advance-fee ban” | The TSR bans ALL fees — regardless of what they’re called — before a debt is actually settled | 16 CFR § 310.4(a)(5) |
| “We handle everything — creditors will stop calling” | Creditors can and do sue enrolled consumers; the settlement company cannot stop a lawsuit or appear in court for you | FTC Debt Relief Guide |
| “Your money is safe in a dedicated/escrow account” | It is your money — you are entitled to all of it back (minus lawfully-earned fees) within 7 business days of cancellation | 16 CFR § 310.4(a)(5)(i)(E) |
| “Attorney-model settlement is different and exempt” | The FTC has taken the position that attorney-model programs that used phone marketing are covered by the TSR | FTC Business Guidance |
If you believe the settlement company collected fees before settling any of your debts (and sold the service by phone), file a complaint with the CFPB, the FTC at reportfraud.ftc.gov, and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov. For a consumer attorney who handles debt-related violations, NACA (National Association of Consumer Advocates) can connect you with one.
Steve’s Take
I filed bankruptcy in 1990. And I spent years — years — running a nonprofit credit counseling organization and watching how the debt industry actually works from the inside. I’ve seen what settlement programs deliver to most people: damaged credit, growing balances, collection lawsuits, and empty promises. The pitch sounds great. “We’ll cut your debt in half.” What they don’t say is that you’re the one who has to wait — sometimes years — while interest and late fees pile up, while your credit tanks, while creditors who get fed up sue you anyway. If you’ve been in a program for 12 months and nothing has settled, the math is almost never going to flip in your favor the longer you wait. The people I’ve watched recover fastest from this situation are the ones who stopped, got their escrow money back, and chose a path with a defined endpoint — often bankruptcy. Debt is math. Don’t let shame or sunk-cost thinking keep you in a losing program when better options exist.
Free Tool — Scam-O-Meter: Considering a debt relief company? Run your situation through the free Scam-O-Meter — it checks for official FTC, FBI, CFPB, and SEC warning signs before you hand over any money. Check for Red Flags →
Frequently Asked Questions
I’ve been paying a debt settlement company for over a year and nothing is settled — is this normal?
Sadly, yes — it’s the norm, not the exception. The FTC’s guidance notes that most settlement programs take 2 to 4 years, and the majority of people who enroll drop out before a single debt is resolved. During that time, your credit suffers, interest and fees accumulate on the original balances, and creditors may file lawsuits. If you haven’t seen a single settlement after 12 months, that’s a meaningful signal that the program is not working for you — not that you need to wait longer.
Can I get my money back from the escrow/dedicated account?
Yes. Under 16 CFR § 310.4(a)(5)(i)(E) of the FTC’s Telemarketing Sales Rule, you can cancel the program at any time without penalty, and the company must return all funds in your dedicated account — minus only fees lawfully earned under the rule — within 7 business days of your written request. Send your cancellation as a written request (email or certified mail) and keep a copy — the statute requires only a request, but having it in writing protects you. If the company delays, refuses, or invents new fees to reduce your refund, file a complaint with the FTC and your state attorney general immediately.
The settlement company says their fees are a “legal retainer” so they’re allowed to charge upfront — is that true?
No. The FTC’s advance-fee ban under 16 CFR § 310.4(a)(5) explicitly prohibits any fee before a debt is actually settled — regardless of what the fee is called. “Retainer,” “legal fee,” “document preparation fee” — none of those labels change the law. If the program was sold to you by phone and they charged you before settling a single debt, that’s a potential federal violation.
I’m being sued by a creditor while I’m enrolled in a settlement program — what do I do?
Your settlement company cannot stop a lawsuit. If you’ve been served with a debt lawsuit, you have a separate, time-sensitive crisis that requires its own action — typically 20 to 30 days to respond, depending on your state. Do not assume the settlement company is handling it. See the companion crisis guide: I Was Just Served with a Debt Lawsuit. Here’s What to Do Right Now. If you’re being sued, filing for bankruptcy triggers an automatic stay that immediately halts the lawsuit. Contact a bankruptcy attorney through NACBA.org right away.
Would bankruptcy have been faster than the settlement program I’m in?
For many people — yes, significantly faster. Chapter 7 bankruptcy typically discharges most unsecured debt (credit cards, medical bills, personal loans) in 3 to 6 months. The automatic stay stops all collection calls, lawsuits, and wage garnishment the moment you file. Federal Reserve research shows that people who file bankruptcy recover faster than those who don’t. If you’re 12 to 24 months into a settlement program with nothing to show for it, talk to a bankruptcy attorney — the math almost always favors starting over with a real endpoint.
Will filing a complaint with the FTC or CFPB get my money back?
Filing a complaint creates a record and contributes to enforcement action — but it’s not a direct refund mechanism for you personally. For your money back, your first move is to cancel in writing and demand the funds directly from the company. If they refuse, a consumer attorney from NACA or a free legal aid attorney from LSC.gov can advise you on private legal remedies. File the FTC/CFPB complaints regardless — they aggregate these reports and they do drive enforcement actions against bad actors.
I’m too embarrassed to tell anyone I got taken in by this — what should I do?
I’ve been in debt trouble myself. I know what it feels like to have made a financial decision you regret. Here’s what I want you to hear: these programs are designed by professionals with skilled sales scripts to sound completely reasonable at the time you signed up. You were not stupid — you were promised something that sounded like a solution to a real problem. The shame belongs to the industry’s practices, not to you. The most important thing now is not to compound the first decision by staying in a program that isn’t working because you’re embarrassed to admit it isn’t working. Deal with this now and look to the future.
What states have extra protections against debt settlement fee abuse?
Many states have layered additional consumer protections on top of the federal TSR, including caps on fees, required licensing for settlement companies, and expanded cancellation rights. States with notably strong debt settlement regulations include California (DFPI registration requirements in effect since February 2025), Illinois (Debt Settlement Consumer Protection Act, 225 ILCS 429), and New York (active AG enforcement under General Business Law). Many other states require licensure and impose fee caps beyond the federal floor. Your state attorney general’s office is the best place to learn what your state specifically requires and to file a complaint if your rights were violated.
One more thing — everything I share here is based on over 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney for non-bankruptcy situations (like potential TSR violations), or talk to Damon Day for free about your situation.
Key Takeaway: Being enrolled in a failing debt settlement program is serious — but you are not trapped. Federal law gives you the right to cancel at any time, get your escrow funds back within 7 business days, and start over with a real plan. Use the Find Your Path quiz to see all your options based on your actual numbers. Talk to a bankruptcy attorney this week — the comparison to what you’re currently doing may surprise you. The longer you stay in a program that isn’t working, the worse the math gets.
The Bottom Line
You are not stupid for being in this situation. The debt-settlement pitch was designed by professionals to sound completely reasonable — “we’ll cut what you owe in half” is a compelling offer when you’re drowning. But you are allowed to change course. You have the right to walk away, get your money back, and look honestly at every option — including the ones the settlement company never told you about. The people I’ve watched come through this fastest are the ones who stopped letting sunk-cost thinking keep them in a losing program. Use the bankruptcy quiz to see if the math makes sense for you, and see the complete crisis guide library for other situations you may be facing. If someone you know is stuck in a debt settlement program that isn’t delivering, send them this page — knowing your rights is the first step to using them.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 15): A number you don’t look at is not an asset
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



