

A $167.5 million settlement between Visa, Mastercard, and the people who use independent ATMs got preliminary court approval on August 14, 2026, the claim window is open now, and the headlines are doing what headlines do with settlement news — making it sound bigger and simpler than it is. I want to walk you through what this settlement actually covers, who actually qualifies, and why I want you to read the fine print before you fill out a single form, because there’s an older, entirely different ATM settlement floating around in searches right now and mixing the two up will waste your time.
What You Need to Know
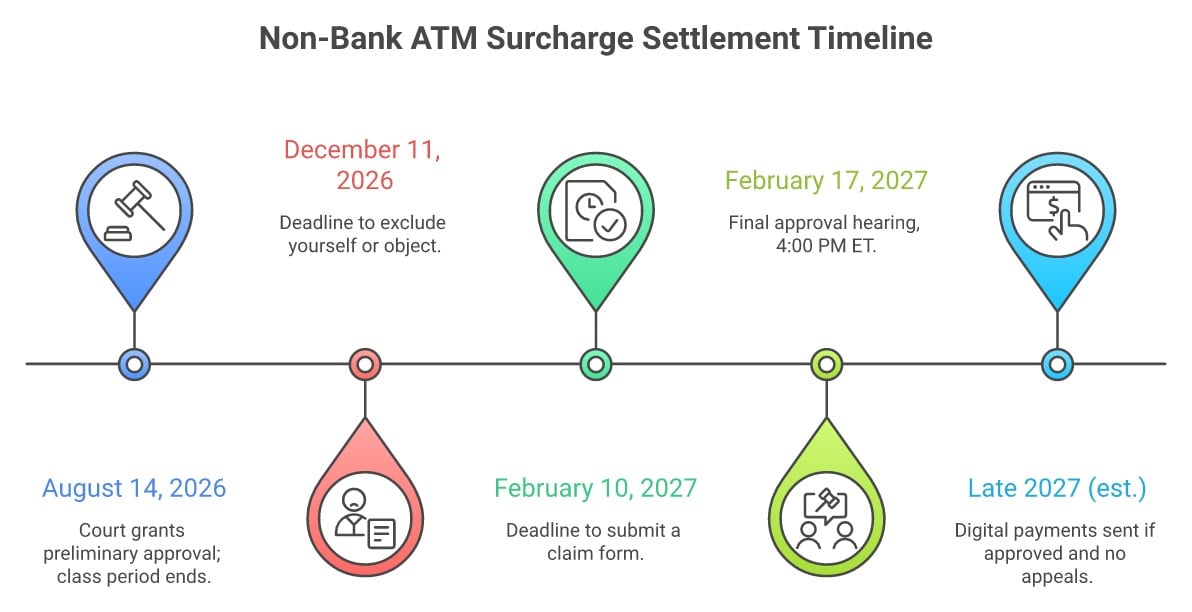
The case is Burke v. Visa Inc., No. 1:11-cv-01882, filed in the U.S. District Court for the District of Columbia and overseen by Judge Richard J. Leon. The plaintiffs alleged that Visa and Mastercard’s network rules stopped independent ATM operators from lowering their surcharges even when a transaction could have been routed over a cheaper competing network — in plain English, that the card networks’ rules kept ATM fees artificially high. Visa and Mastercard deny they did anything wrong, and nothing about this settlement is a finding that they broke the law. The court gave preliminary approval on August 14, 2026, and under that order the claims period opened 28 days later — it’s live now.
If approved, Visa and Mastercard will collectively pay $167,500,000 into a settlement fund — Visa contributing $88,775,000 and Mastercard $78,725,000 — according to the official settlement notice. After attorneys’ fees, litigation costs, taxes, up to $3 million in notice and administration costs, and service awards to the class representatives come out, what’s left goes to people who file valid claims.
You’re generally covered by the Nationwide Class if you’re in the United States, were charged a surcharge (also called an access fee) to withdraw cash from your deposit account using an ATM or PIN-debit card at an independent ATM located in the U.S. or its territories between October 24, 2007, and August 14, 2026, and your bank did not fully reimburse you for that fee. There are also Statewide Classes for California, Illinois, Massachusetts, and Michigan — but per the court’s preliminary approval order, these are defined identically to the Nationwide Class, just limited to fees charged at an independent ATM located in that specific state. They’re a subset, not a broader net — if you don’t meet the nationwide test, the statewide classes won’t cover you either.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Claiming money you are owed is one good day. What you do over the following year is what actually changes your position.
In the latest issue (Sep 22): The $1,000 retirement match in this week’s headlines has been law since 2022
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
Two words matter more than any other in that eligibility test: independent and surcharge. An independent ATM — the settlement notice calls it an “IATM” — is a machine not owned by Visa, Mastercard, a bank, or any other financial institution. Think the ATM in a convenience store, a bar, a casino, or a standalone kiosk in a strip mall — not the machine outside your own bank’s branch. And it has to be a domestic cash withdrawal from your deposit account using an ATM or debit card. Credit card transactions, cash advances, and prepaid card transactions don’t count.
Why You Need to Know It
In more than 30 years of talking to people about money, I’ve watched ATM surcharges do something that looks small on paper and isn’t small in real life: they punish you specifically for not having cash sitting in a bank account near where you need it. If you’re living paycheck to paycheck, you’re more likely to be pulling small amounts of cash from whatever machine is closest — not driving across town to find your own bank’s ATM — and every one of those $3 or $5 surcharges is a bigger percentage bite out of a smaller amount of money. That’s not a coincidence of geography. It’s a cost that falls hardest on people who can least absorb it — the same reason I’ve written about how debit card overdraft fees are supposed to require your opt-in and often didn’t get meaningful, informed consent. It’s the same structural problem wearing a different fee’s name.
It’s also why I want you to read the class definition carefully instead of just seeing “$167.5 million Visa Mastercard settlement” and assuming you’re covered. This settlement pays people who used independent ATMs — not your own bank’s machine, and not the separate “out-of-network” fee your own bank tacks on when you use another bank’s ATM. It covers only the surcharge (the access fee) the independent ATM’s owner charged you directly, and only if your bank never fully reimbursed you for it. That’s a narrower group than most of the news coverage makes it sound.
The Settlement You’re Actually Thinking Of Might Be a Different One
Here’s the part that trips people up. The Burke settlement’s own court notice names a separate, earlier case — Mackmin v. Visa Inc., No. 1:11-cv-01831 — brought by different plaintiffs in front of the same D.C. federal court, covering fees charged at bank-owned out-of-network ATMs. That litigation produced two rounds of settlements: an initial set with Bank of America, Chase, and Wells Fargo that reached final approval in 2022, then a separate settlement with Visa and Mastercard that reached final approval on June 23, 2025. If you already got a payment notice or a digital payment earlier this year for an ATM fee settlement, that was almost certainly that earlier Mackmin case — not this one.
And here’s the part I really need you to see if you’re one of those people: the official Mackmin settlement site, atmclassaction.com, says the digital payments it issued between April and June 2026 have all since been canceled, and it explicitly warns that “there have been fraudulent attempts to send digital payments to class members” — telling people not to click any links in those emails. If you’re holding onto an old payment link or you get an email claiming to pay out that older settlement, don’t click it. Type atmclassaction.com into your browser yourself to check the current status before you assume anything is finally coming through.
This new $167.5 million settlement, the Burke case, is specifically about independent, non-bank ATMs, and the claim window is open now, for the first time. If you were only ever charged fees at bank-owned machines, this particular settlement isn’t the one that covers you — though it’s still worth checking the official site, since some people used both types of machines over the years.
Things to Consider Before You File
Nobody can tell you what your payment will be — and be suspicious of anyone who claims they can. Per the settlement notice, each valid claim gets a pro rata — proportional — share of the net settlement fund, based on the total number of qualifying surcharged transactions submitted across all claims. Because nobody knows in advance how many transactions will be submitted, nobody can promise you a dollar figure. If you see a website, email, or text guaranteeing you a specific payout, that’s a red flag, not a preview.
You do not need to dig up old ATM receipts to file. The settlement notice states you don’t need to provide documentation at the time you file, though the claims administrator may ask for additional proof later if your claim is questioned. It still doesn’t hurt to have a rough sense of which independent ATMs you used and roughly how often, especially if you kept old bank statements — those will back you up if anyone asks.
Filing is free. Any email, text, or third party asking for an upfront fee before you can get your payment is a scam, not a real charge from this settlement. You file directly with the court-appointed claims administrator, A.B. Data, Ltd. — never through a third party charging a fee, a “settlement recovery service,” or anyone who contacts you first promising to handle it for a cut of your payment. Class action settlement season is prime time for copycat sites and scam texts that borrow real settlement names to phish for your bank information. The real settlement will never ask you to pay to receive money you’re owed.
Deadlines that actually matter here:
- Claim form deadline: February 10, 2027
- Deadline to exclude yourself: December 11, 2026 — your letter must be received by the claims administrator by that date, not just mailed
- Deadline to object: December 11, 2026 — your objection must be postmarked by that date
- Final approval hearing: February 17, 2027, 4:00 p.m. ET
If you do nothing: you stay in the settlement class and are bound by its release of claims against Visa and Mastercard whether or not you ever file for payment — the court’s order says that applies “whether or not such person or entity makes a claim upon the settlement funds.” Filing a claim is the only way to actually get money from this settlement; doing nothing means giving up your right to sue over these fees separately, with nothing in return. Excluding yourself (opting out) by December 11, 2026 preserves your right to sue Visa and Mastercard on your own over these fees, but it also means you can’t file a claim here. For an ordinary ATM surcharge or two, filing the free claim and staying in usually makes more sense than opting out to preserve a lawsuit most people will never actually file.
Even after final approval, the notice says payments are expected within six months if nobody appeals — with the final approval hearing set for February 17, 2027, that points to sometime in the six months after that, realistically mid-to-late 2027, not sooner. This is not a fast-money settlement. It’s a “file it, forget about it, and it shows up eventually” settlement, and I’d rather you know that going in than feel jerked around six months from now. If you want a sense of how these digital-payment class actions typically play out, I walked through a similar timeline in the TransUnion bankruptcy-remark settlement — same “file now, get paid later” structure, different company.
What to Think About Doing
File directly at nonbankatmsurchargesettlement.com — that’s the domain named in the court’s own order granting preliminary approval, so it’s the one to type in yourself rather than click from an email or text. Provide a current email address and mobile number, since payments go out digitally — by PayPal, virtual debit card, or similar — and a stale email address is a common, avoidable reason people never see money they’re owed. If you have questions, the settlement notice lists a real phone line and mailing address through the claims administrator, A.B. Data — not the court itself. The notice is explicit that the court and the clerk’s office cannot answer questions about the case, so don’t waste time calling them.
And if you’re not sure whether you qualify — whether that machine you used at the gas station counted as “independent” or was secretly bank-owned — file a claim anyway if you have a genuine, good-faith belief you paid an ATM or PIN-debit surcharge at a non-bank ATM, that your own bank never fully reimbursed, sometime in the last nineteen years. One thing to take seriously: the claim form is submitted under penalty of perjury, and the administrator can ask you for bank statements to back it up. That’s not a reason to hold back if your belief is honest — it’s a reason not to guess wildly or claim transactions you don’t actually remember, including ones your bank already refunded. I’ve seen the same pattern with other recent claim windows — two credit unions settling overdraft and NSF fee claims and a $120 million homebuyer commission settlement both work the same way: file directly, pay nothing, and don’t expect an overnight check.
Frequently Asked Questions
Do I need a receipt or bank statement to file a claim?
No. The official settlement notice states you don’t need to provide documentation when you file, though the claims administrator may ask for additional proof later if your claim needs verification. Old bank statements can help if that happens, but they aren’t required to submit your claim.
How much money will I actually get?
Nobody knows yet, including the settlement administrator. Each valid claim receives a pro rata share of the net settlement fund, so your payment depends on the total number of qualifying surcharged transactions submitted across every claim, not just yours. Treat any specific dollar figure you see online as a guess, not a promise.
Is this the same settlement where people already got paid earlier this year?
No. That was the separate Mackmin case, covering fees at bank-owned ATMs, which reached final approval in June 2025 with digital payments issued between April and June 2026. The official Mackmin site now says those digital payments have all been canceled and warns of fraudulent emails impersonating that payment — so if you’re waiting on that one, don’t click payment links in unexpected emails. This settlement, the Burke case, covers independent, non-bank ATMs only and has its own, separate claim window.
What if I only ever used my own bank’s ATM?
Then this particular settlement likely doesn’t cover you — it’s specifically for surcharges at independent ATMs not owned by a bank or financial institution. Filing a claim for transactions that don’t meet that definition won’t get you a payment.
Do I have to pay anything to file a claim or receive my payment?
No, never. Filing through the official settlement website is free, and you should never pay anyone — a “recovery service,” a text message sender, a website asking for an upfront fee — to file on your behalf or to “release” a payment. That is a scam pattern, not how legitimate class action settlements work.
This is what I’m seeing after more than 30 years of helping people untangle exactly this kind of confusing money news. Take it as one informed perspective, not a directive — you know your own situation better than any settlement notice does. Verify the details yourself on the official site before you act, and don’t let anyone, including me, tell you what to do with your money.
If this saved you from filling out the wrong form — or from a scam site pretending to be the real thing — send it to someone else who’s seen the “$167 million ATM settlement” headlines and isn’t sure if it applies to them.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



